REV 27-0032
Zero emission buses bought by a transit agency or federally recognized tribe
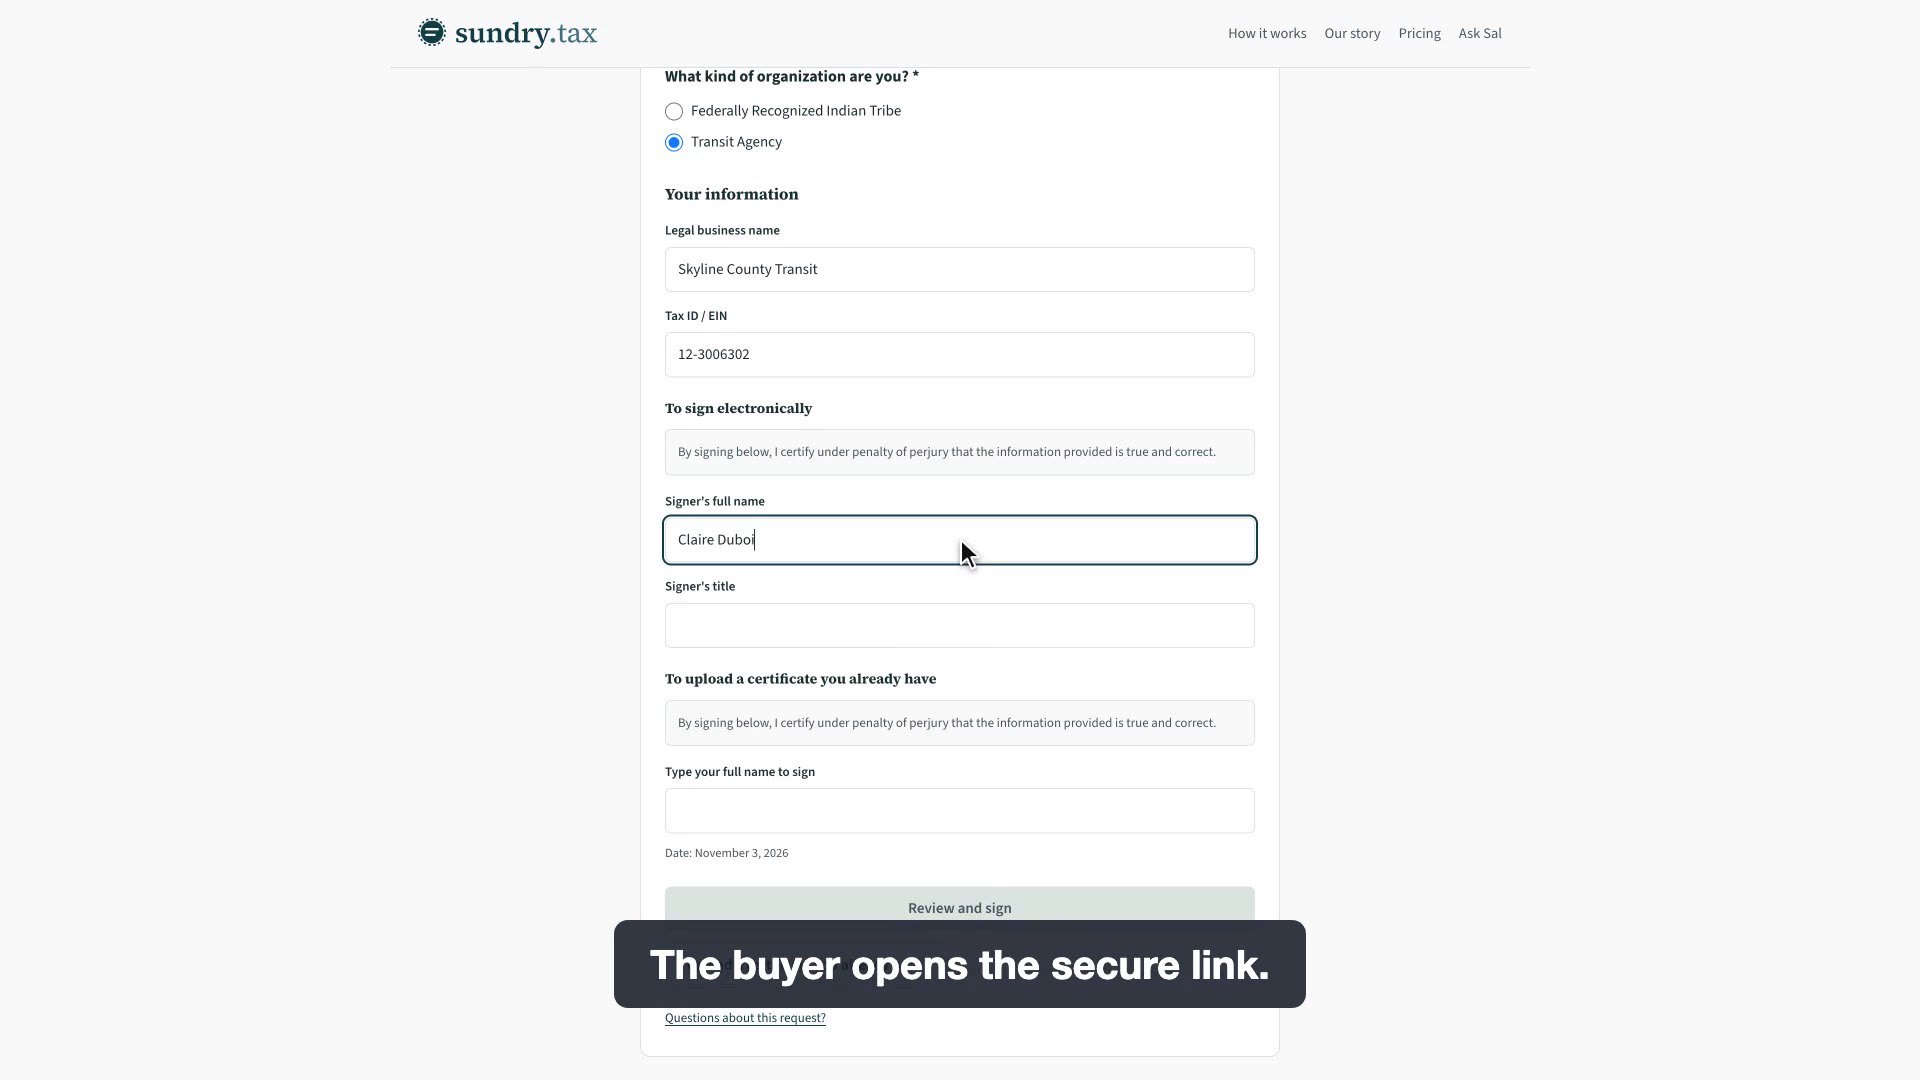
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Washington transit agencies, and federally recognized tribes buying for public transportation, pay no sales or use tax on zero emission buses. The exemption has a dollar cap: it ends after the department finds that $14 million in state sales and use tax has been exempted, so a buyer should check the department's monthly notice before relying on it.
Who qualifies
- A transit agency: a city-owned transit system, county transportation authority, metropolitan municipal corporation, public transportation benefit area, unincorporated transportation benefit area, or regional transit authority.
- A federally recognized Indian tribe buying the bus to provide public transportation services.
What qualifies
- Zero emission buses: buses that emit no exhaust gas from the onboard source of power, other than water vapor.
Not covered
- Buses that emit exhaust gas other than water vapor from the onboard power source.
- Buses bought by anyone not on the statute's list, such as private bus operators.
- Buses bought by a tribe for purposes other than providing public transportation services.
- Charging or fueling infrastructure. The form lines for electric vehicle infrastructure (2b) and the earlier zero emissions bus line (2c) expired July 1, 2025.
- Sales after the cap is reached: the exemption expires after the last day of the month following the month the department determines exemptions under RCW 82.08.994 and 82.12.994 reach $14,000,000.
What the buyer gives
Form REV 27 0032 (revision 6/17/25), line 2f: "Zero emission buses purchased by a transit agency or federally recognized Indian tribe for providing transportation services (effective July 1, 2025)." Do not check line 2c, "Zero emissions buses (expired July 1, 2025)." The buyer ticks single use or blanket, enters the seller's name and address and the date, checks 2f, lists the buses, and completes the certification block (type of entity, type of business, Account ID, name, title, address, signature). RCW 82.08.994(2): sellers may sell tax exempt "only if the buyer provides the seller with an exemption certificate in a form and manner prescribed by the department."
What the seller keeps
RCW 82.08.994(2): "The seller must retain a copy of the certificate for the seller's files." Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Checking line 2c. It is the earlier zero emissions bus exemption and expired July 1, 2025; the current line is 2f.
- Not checking the cap. The department must post monthly on its website the amount of exemptions issued and remaining, and the date the exemption expires once the limit is reached.
- Treating a hybrid as zero emission. The definition allows no exhaust gas from the onboard source of power other than water vapor.
Common questions
- Can a public transportation benefit area buy battery-electric buses without sales tax?
- Yes. A public transportation benefit area is a transit agency under the statute, and a battery-electric bus that emits no exhaust gas qualifies, until the $14 million cap is reached.
- Can a tribe use the exemption?
- Yes, a federally recognized Indian tribe buying the bus to provide public transportation services.
- Is a hydrogen fuel cell bus covered?
- The test is the exhaust: a bus qualifies if it emits no exhaust gas from the onboard source of power other than water vapor.
- When does the exemption end?
- After the last day of the calendar month following the month the department determines total state sales and use tax exemptions under RCW 82.08.994 and 82.12.994 reach or exceed $14,000,000. A new version of RCW 82.08.994 takes effect July 1, 2027; it changes only the state account used for the transfer and keeps the same buyers, buses and cap.
Sources
- RCW 82.08.994 (1)-(5); version effective until and version effective July 1, 2027
- RCW 82.12.994 Matching use tax exemption and cap
- RCW 82.38.030 (notes) Effective date note for 2025 c 417 ss 808-814: July 1, 2025
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 2 lines 2b, 2c, 2f; page 4 certification
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.994(1)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal