REV 27-0032
Weatherization assistance program materials (become part of the residence)
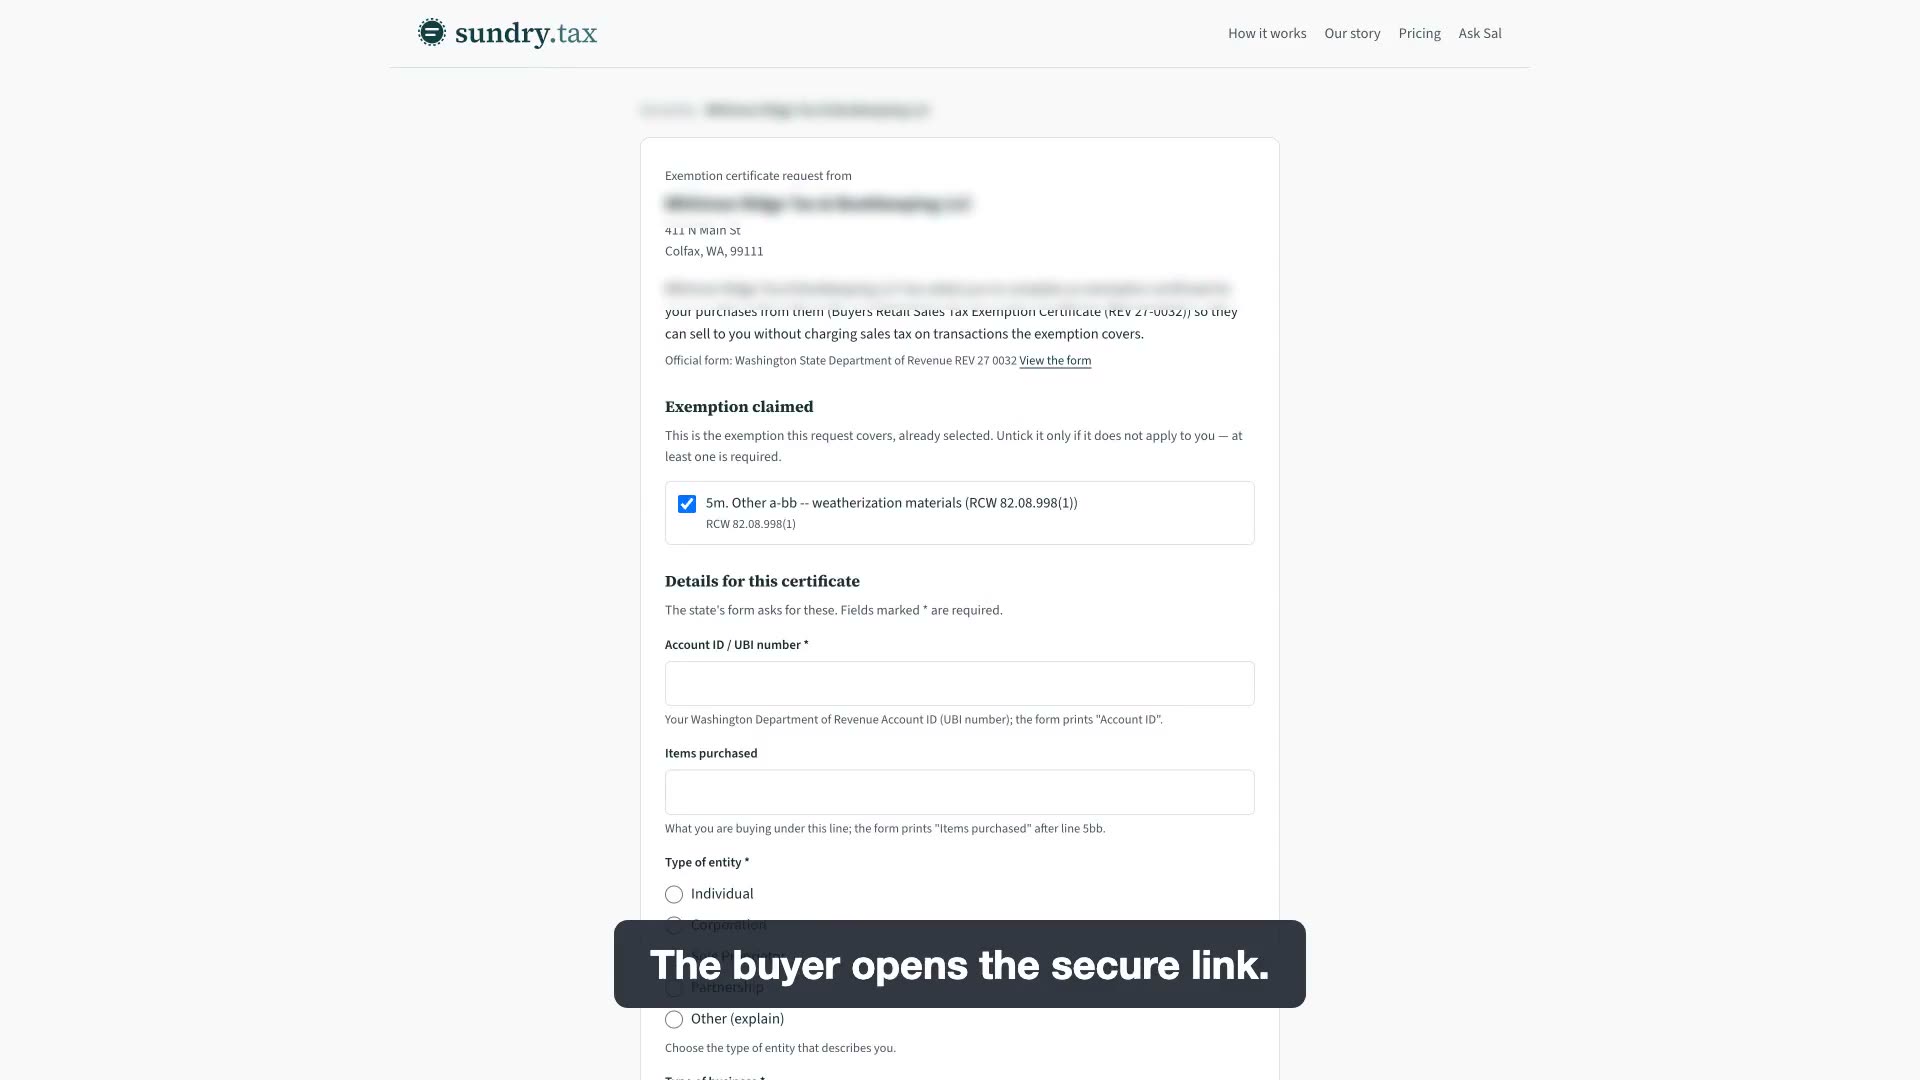
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Materials installed in a home under Washington's state-administered weatherization assistance program are exempt from sales and use tax, but only the materials that become part of the residence. The tools, labor and equipment a crew brings and takes away are not covered, and the same materials bought for a private retrofit job are taxable.
Who qualifies
- The statute limits the use, not the type of buyer: the property must be used in the weatherization of a residence under the weatherization assistance program, chapter 70A.35 RCW.
- "Weatherization" under that chapter means activities that use funds administered by the Department of Commerce for conservation, energy efficiency improvements, repairs, indoor air quality and health and safety improvements, client education, or community scaled projects.
- Those funds may be used only to preserve a dwelling unit occupied by a low-income household (income no more than 80 percent of county median, adjusted for household size), except for units in a community scaled project.
- The work is carried out under a "weatherizing agency": an approved department grantee, tribal nation, utility or other entity approved by the department to be responsible for the weatherization.
What qualifies
- Tangible personal property used in weatherizing a residence under the program.
- Only property that becomes a component of the residence. "Residence" means a dwelling unit as defined by the Department of Commerce.
Not covered
- Property that does not become a component of the residence, such as tools and equipment the crew uses and removes, and materials used for energy audits or client education.
- Labor and services. The statute exempts sales of tangible personal property only.
- Materials for weatherization work done outside the program, such as a contractor's ordinary retrofit for a private customer.
What the buyer gives
Form REV 27 0032 (revision 6/17/25), line 5m: "Tangible personal property under the weatherization assistance program." The instructions say "The tangible personal property must become a component part of the residence." The buyer ticks single use or blanket, enters the seller's name and address and the date, checks 5m, lists the materials, and completes the certification block (type of entity, type of business, Account ID, name, title, address, signature). RCW 82.08.998(2): the exemption "is available only when the buyer provides the seller with an exemption certificate in a form and manner prescribed by the department."
What the seller keeps
RCW 82.08.998(2): "The seller must retain a copy of the certificate for the seller's files." Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Using one blanket certificate for program and private jobs alike. Only materials for program weatherization qualify.
- Putting tools, ladders, testing equipment or other items the crew keeps on the certificate. They do not become a component of the residence.
- Expecting the installation labor to be exempt. The statute covers tangible personal property, not services.
Common questions
- Is a contractor working for a community action agency exempt on the insulation it installs?
- The materials are exempt if they are used in weatherizing a residence under the program in chapter 70A.35 RCW and become a component of the residence, and the buyer gives the seller a completed REV 27 0032 with line 5m checked.
- Does the home have to be low-income?
- Program funds may be used only to preserve a dwelling unit occupied by a low-income household, except for dwelling units that are part of a community scaled project.
- Is there a use tax exemption too?
- Yes. RCW 82.12.998 exempts the use of the same property on the same terms.
Sources
- RCW 82.08.998 (1)-(3) exemption, certificate and definitions
- RCW 82.12.998 Matching use tax exemption
- RCW 70A.35.020 (7) low income; (9) residence; (12) weatherization; (13) weatherizing agency
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 3 line 5m; page 4 certification; page 6 line 5m instructions
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.998(1)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal