REV 36-0001
Sale to a federally recognized tribe, delivered in the tribe's Indian country
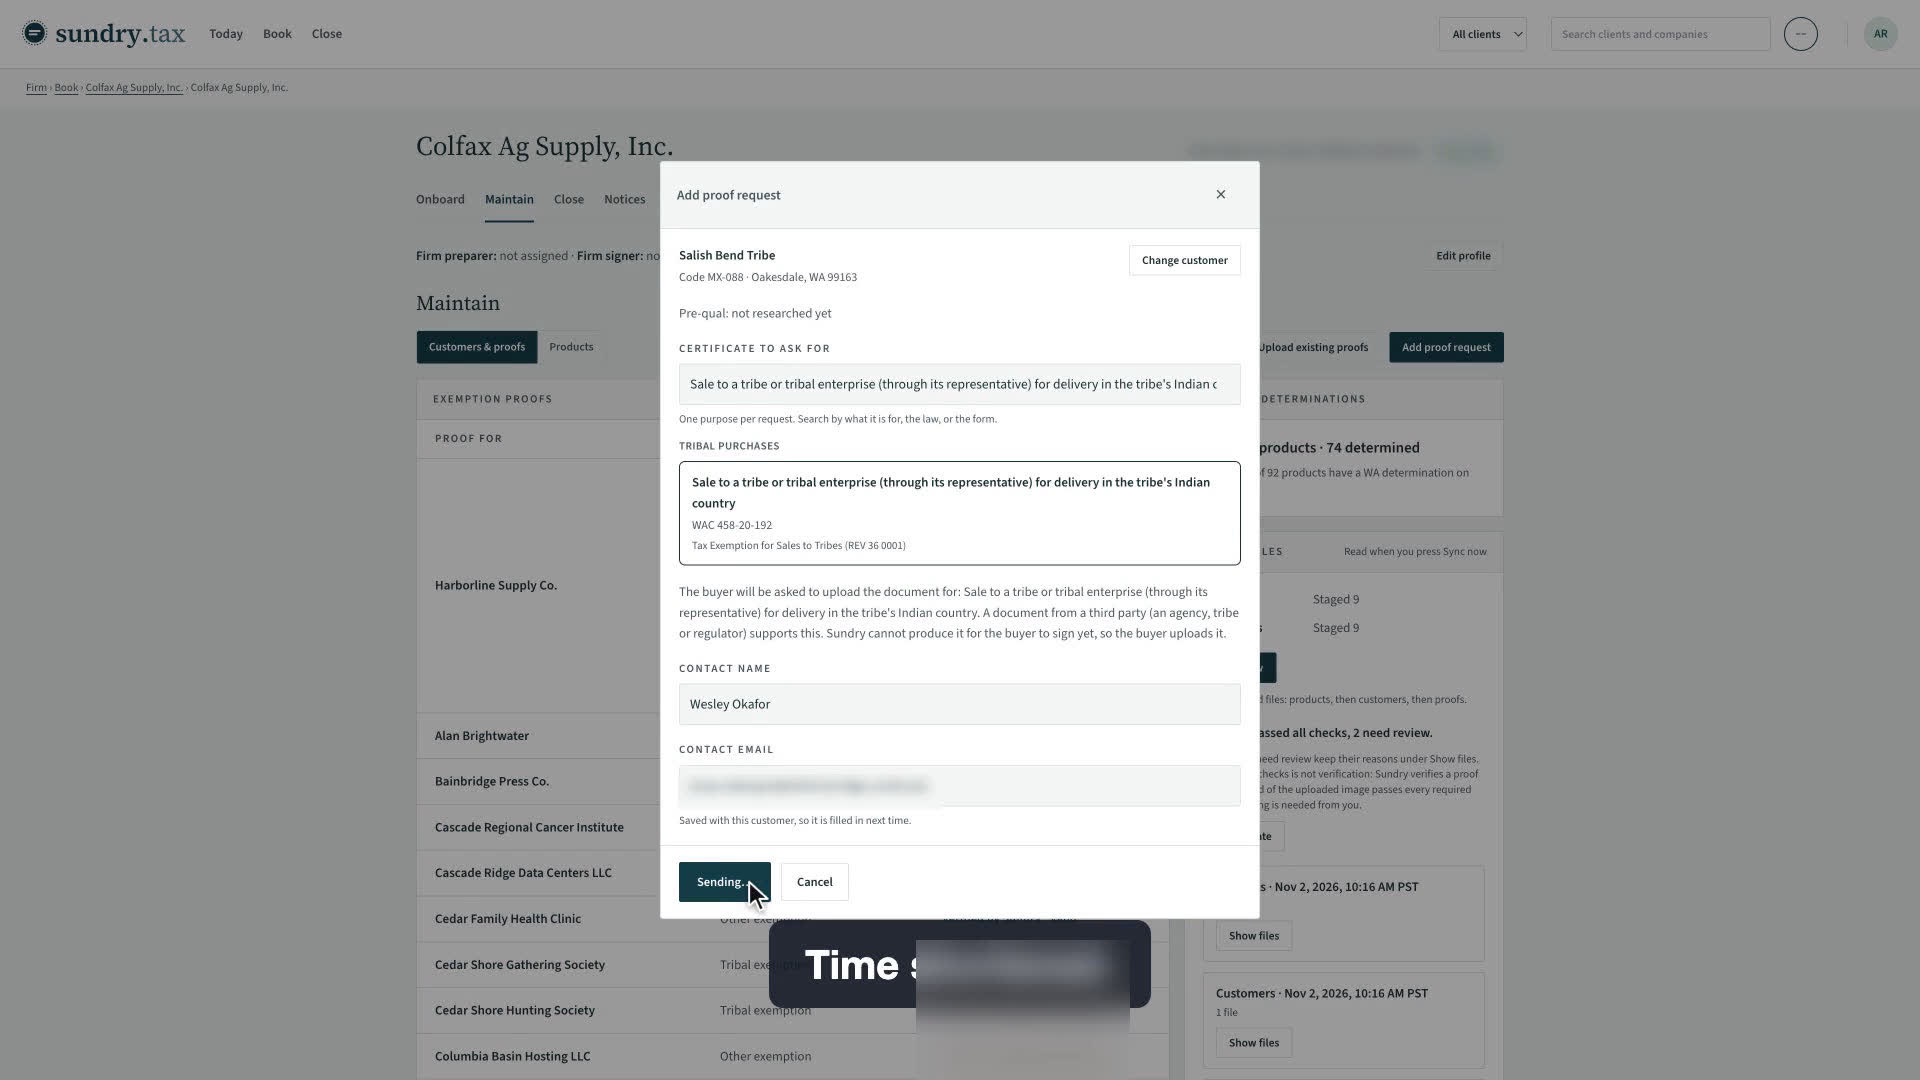
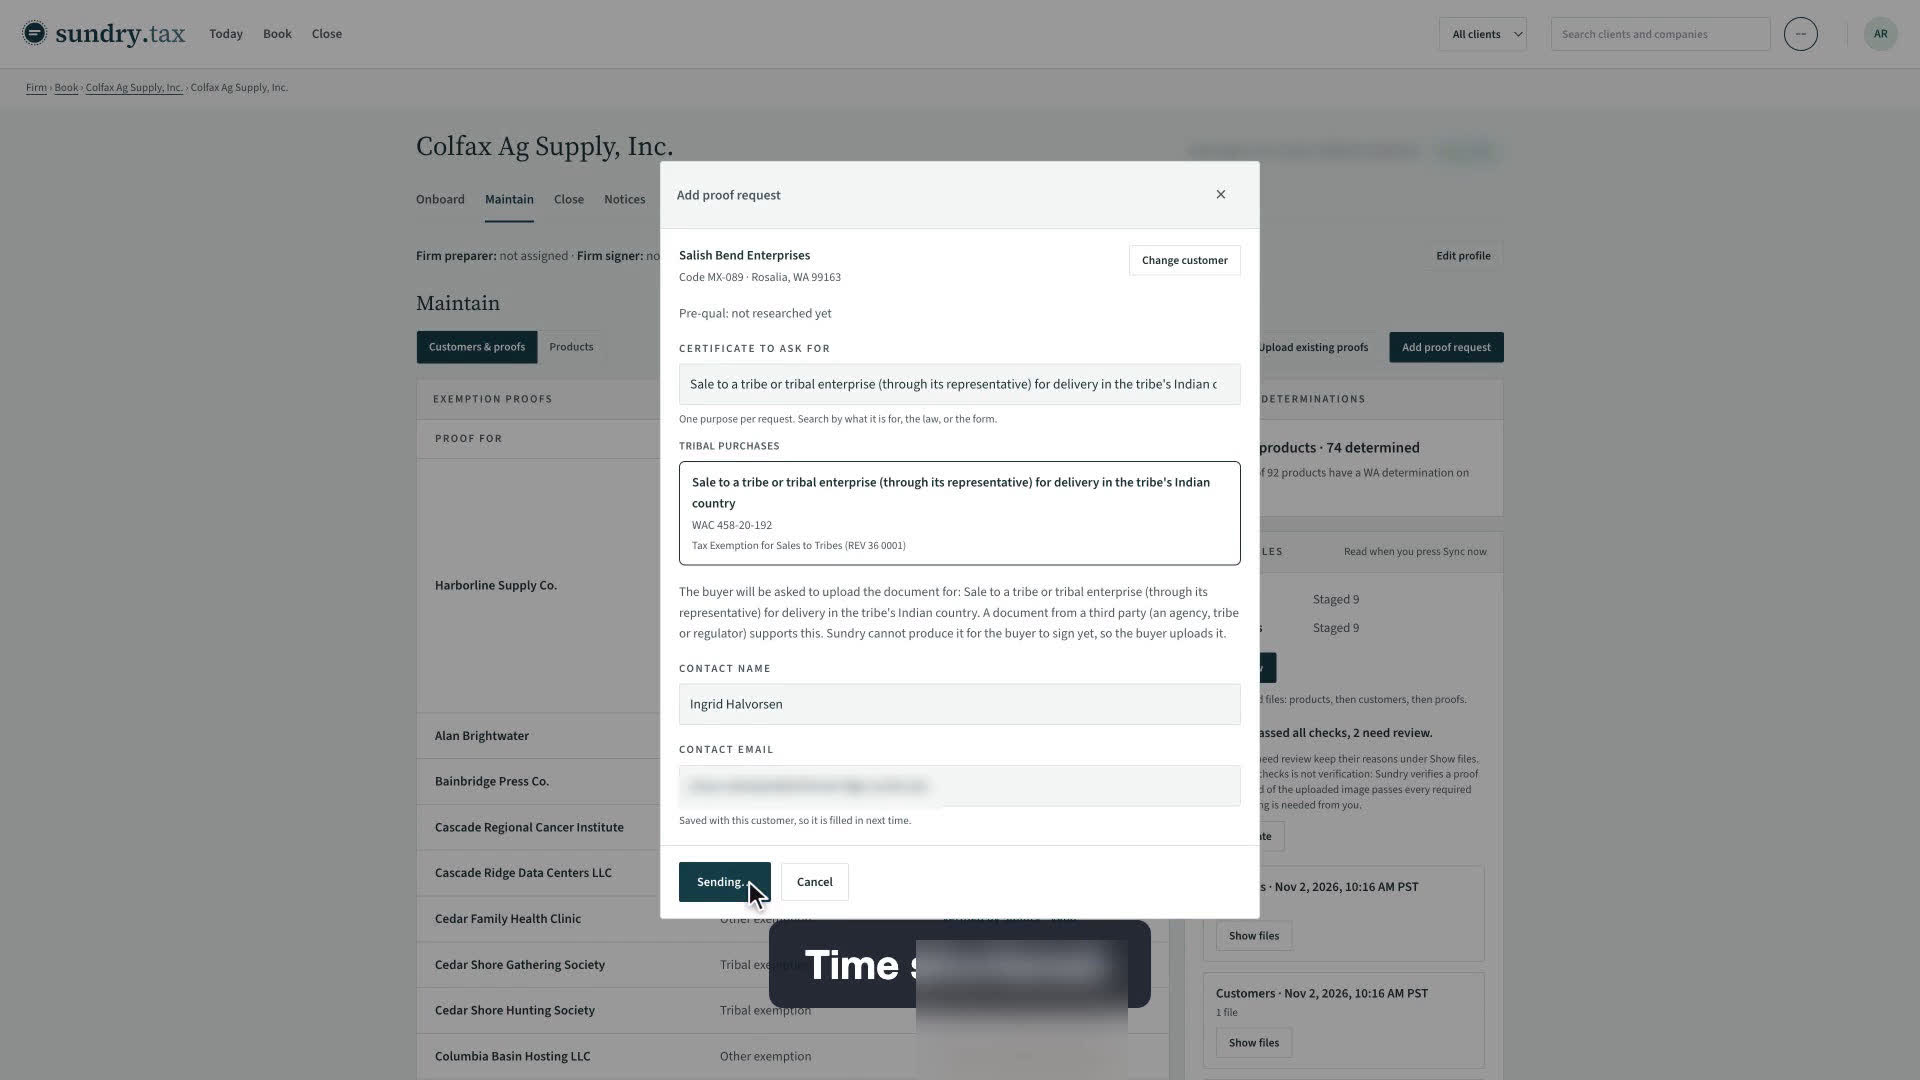
A firm asks for proof that the tribe made the purchase, the buyer uploads a payment record from the tribe, such as a copied check, from the emailed link, and Sundry reads it.
Tribe
Tribal enterprise
A sale to a federally recognized Indian tribe or tribal enterprise, or to a contractor hired by one, is free of Washington retail sales tax when the goods are delivered to the worksite in that tribe's Indian country (or the sale or service takes place there). The seller keeps DOR form REV 36 0001 and the proof the buyer's representative showed.
Who qualifies
- A federally recognized Indian tribe, a tribal enterprise, or a contractor hired by one, buying through a representative, with delivery to the worksite in that tribe's Indian country (or the sale or service taking place there).
- "Indian country" means land within a reservation (including rights of way), dependent Indian communities, and Indian allotments whose Indian titles have not been extinguished.
What qualifies
- Goods sold to the tribe, tribal enterprise or its contractor and delivered to the worksite in the tribe's Indian country, or a sale or service that takes place there. REV 36 0001 has boxes for the enterprise and the contractor; WAC 458-20-192(5)(a) covers the tribe.
- Form REV 36 0001 also covers refuse tax, public utility tax and telephone or 911 taxes on services the seller provides to the buyer in its Indian country.
Not covered
- Goods the buyer takes delivery of outside Indian country.
- Sales to a person or business that is not a federally recognized tribe, a tribal enterprise, or a contractor hired by one, for goods delivered to the worksite in that tribe's Indian country (or a sale or service taking place there).
- Vehicles, and treaty fishing, hunting and gathering purchases. DOR lists separate forms for these on page 2 of REV 36 0001.
What the buyer gives
Proof that the buyer is the tribe or its enterprise: the form accepts a letter from a tribal representative, payment from the tribe or tribal enterprise (such as a copied check), or a receipt or other proof of a tribal credit card. The seller ticks "A representative of the ___ Tribe or Tribal enterprise" and the proof shown. Form REV 36 0001 is completed by the seller, not signed by the buyer: the seller enters its name and UBI, the buyer's name and the delivery address in Indian country, and ticks who the buyer is and which proof was shown.
What the seller keeps
Form REV 36 0001: "You must keep this form as proof that they meet the exemption criteria below." WAC 458-20-192(4): taxpayers "are required to maintain appropriate records on the tax exempt status of transactions." Keep the delivery record too; the exemption turns on delivery in Indian country. RCW 82.32.070(1) requires five years of records.
Common mistakes
- Exempting a delivery made outside the tribe's Indian country. Without delivery in Indian country, sales tax applies.
- Keeping no record of the proof the representative showed. Note which proof was shown on REV 36 0001.
Common questions
- Do I charge Washington sales tax on goods sold to a tribe and delivered to its reservation?
- No. WAC 458-20-192(5)(a) provides that sales of goods to a federally recognized tribe, delivered in the tribe's Indian country, are exempt from retail sales tax; REV 36 0001 has boxes for a tribal enterprise and for a contractor hired by one. Keep form REV 36 0001 and note the proof shown.
- Does the buyer have to sign form REV 36 0001?
- The form has no buyer signature line. The seller fills it in, records the proof the buyer showed, and keeps it.
Sources
- WAC 458-20-192 (2) definitions; (4) recordkeeping; (5)(a)
- DOR form REV 36 0001 (2/9/23), Tax Exemption for Sales to Tribes Page 1 buyer types and proof; page 2 tax boxes, other forms
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 36-0001: Tax Exemption for Sales to Tribes
- Statute
- WAC 458-20-192(5)(a)
- Category
- Entity