REV 27-0049
Tribal hunting (including trapping): goods and services used directly
A firm asks a customer for proof of tribal enrollment, the buyer uploads a photo of their tribal ID from the emailed link, and Sundry shows it received and checked.
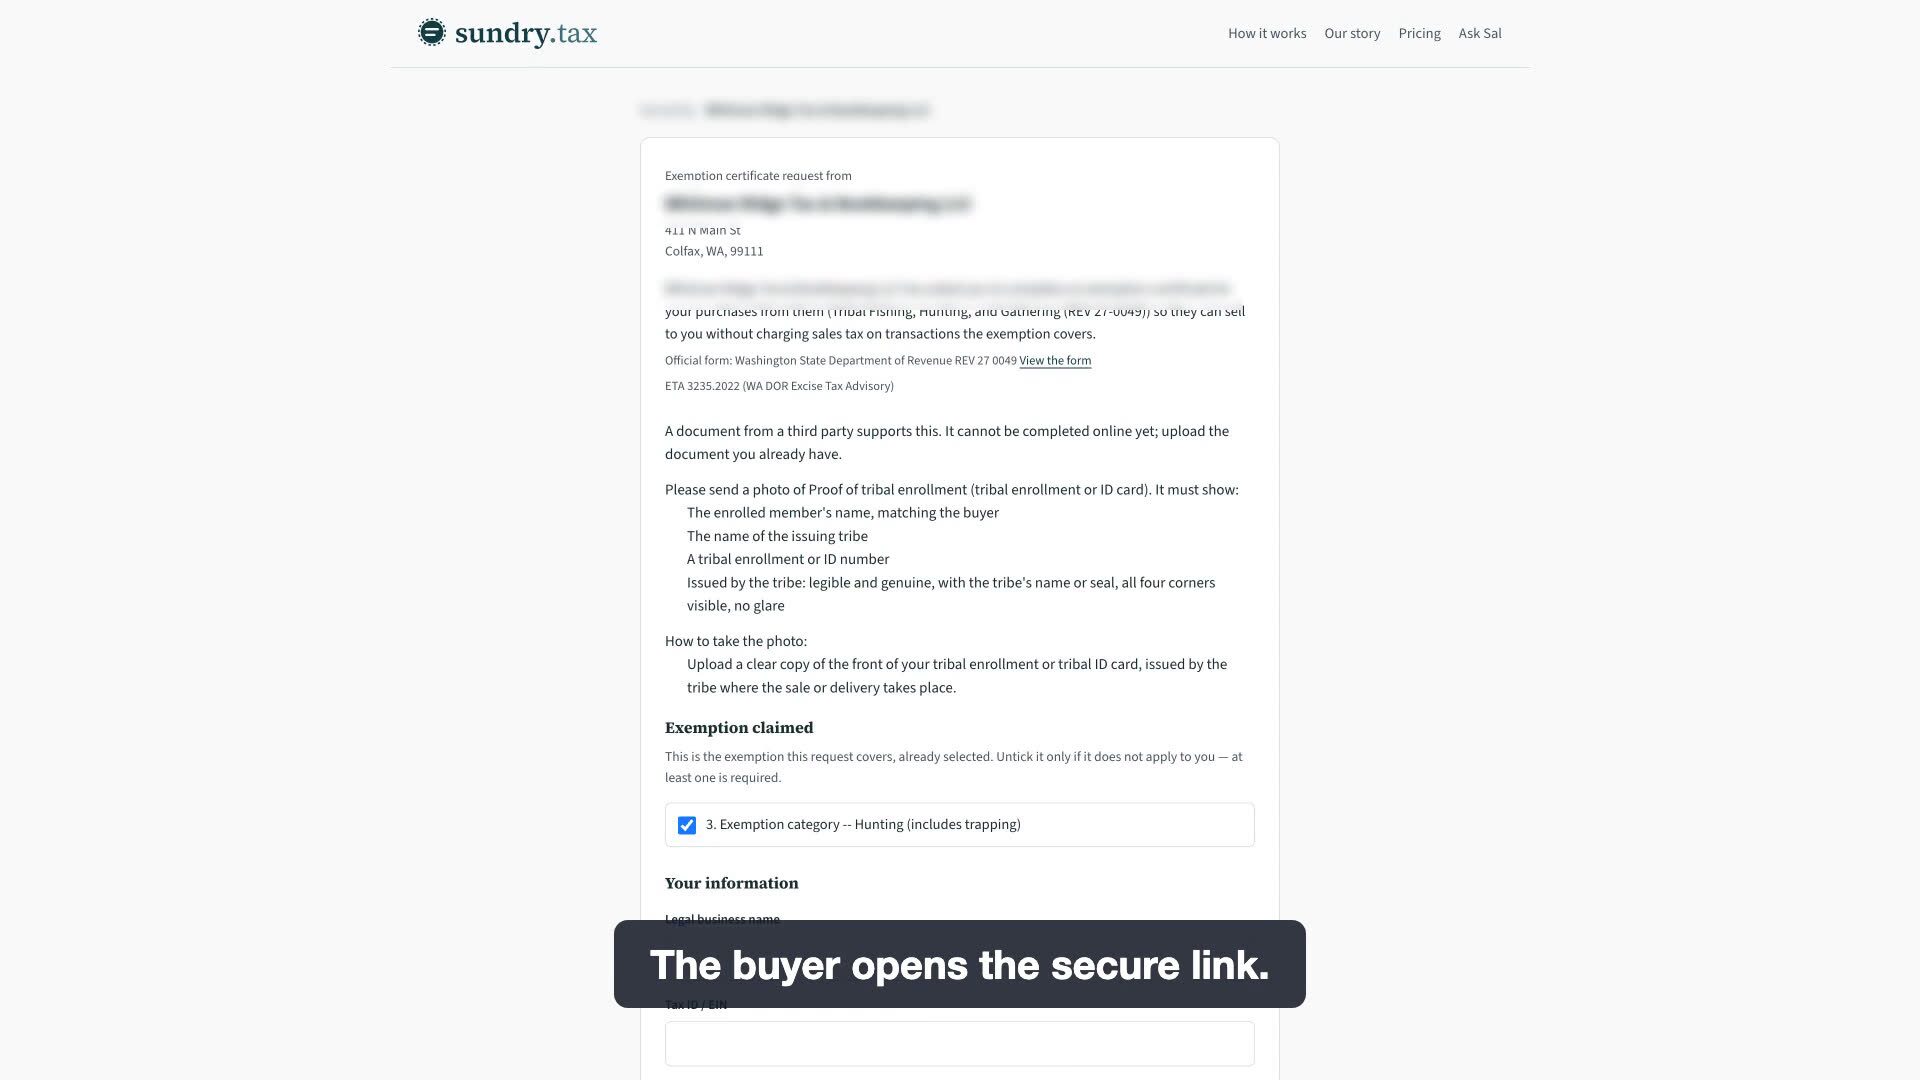
Goods and retail services directly used in tribal hunting, which includes trapping, are exempt from Washington retail sales tax when sold to a qualified tribe, a member of a qualified tribe, or a qualified intertribal organization. The exemption applies wherever the item is delivered or the service performed, on or off a reservation. The seller documents it on form REV 27 0049.
Who qualifies
- A "qualified purchaser": a qualified tribe, a tribal member of a qualified tribe, or a qualified intertribal organization.
- DOR lists 32 qualified tribes, including tribes based outside Washington such as the Confederated Tribes of the Umatilla Indian Reservation, the Confederated Tribes of the Warm Springs Reservation of Oregon and the Nez Perce Tribe.
- DOR's list of qualified intertribal organizations is nonexclusive: Columbia River Inter-tribal Fishery Commission, Northwest Indian Fisheries Commission, Point No Point Treaty Council and Skagit River Systems Cooperative.
- The activity must be within the scope of the hunting rights of the qualified tribe. DOR: "hunting" includes trapping.
What qualifies
- Retail goods and retail services used directly in tribal hunting activities. The form lists the kinds of activity: harvesting, processing, transporting, selling, management, enforcement and other activities.
- Examples from DOR's hunting list: rifles, shotguns, handguns, muzzleloaders and air-powered rifles; hunting ammunition; scopes, suppressors and reloading supplies; bows, arrows, calls and decoys; hunting blinds; game cameras and memory cards; binoculars; knives and knife sharpeners.
- Processing and storage: processing equipment and tools, butcher paper, canning jars, dehydrators, drying racks, food sealers, coolers, freezers, ice and refrigeration equipment.
- Trapping equipment: leg holds and body traps, snares and live wire traps, fur stretching frames, pelt scrapers, predator calls, scents, baits, wire, and home tanning and taxidermy chemicals.
- Off-road vehicles not listed for on-road use (ATVs, UTVs, quads, motorcycles) and their accessories; camping gear; specialized hunting clothing for adults and children; parking charges incurred during hunting.
- DOR says the list is not exclusive.
Not covered
- Goods and services not used directly in hunting activities.
- Sales to a buyer who is not a qualified tribe, a member of one, or a qualified intertribal organization.
- Activities outside the scope of the tribe's hunting rights. DOR states that its guidance does not create or expand any tribal rights beyond potential tax liability.
- The retailing B&O tax. DOR: there is no corresponding B&O deduction; the seller still reports the gross sale under retailing B&O.
- Vehicles for on-road use are not on DOR's list; the vehicle entry is limited to off-road vehicles not listed for on-road use.
What the buyer gives
The buyer shows tribal-issued identification: a tribal identification card, a tribal fishing card, or documentation issued by the tribe on tribal stationery. The seller, not the buyer, fills in form REV 27 0049, Tribal Fishing, Hunting, and Gathering (revision 03/30/22): single use or blanket; the seller's name, UBI, date and address; the buyer's name and phone, and the qualified tribe or intertribal organization "as shown on the tribal-issued identification card or other tribal documention"; the "Hunting (includes trapping)" box; and the items sold. The form has no buyer signature line. As a blanket certificate it covers a recurring relationship (at least one sale in 12 months), and for recurring sales to a known customer it "need only be completed on an annual basis."
What the seller keeps
The form says: "The seller must keep a copy of the Tribal Fishing, Hunting and Gathering form in its records for five years after its last use," and must document the tribal buyer's name, tribe or intertribal organization, items purchased and date of purchase. DOR: the retailer does not need to keep a copy of the identification; noting the required information on the form is enough. Do not send the form to the Department. A seller that accepts the form in good faith for qualified goods or services sold to a qualified purchaser "will not be held liable for any uncollected sales tax." Reporting: report the gross sale under retail sales tax and retailing B&O, then take the "Tribal fishing, hunting, gathering" deduction from the state portion of retail sales tax. RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when the department asks; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Charging sales tax because the sale is off the reservation. DOR says the exemption applies no matter whether delivery occurs in Indian country.
- Taking a B&O deduction as well. There is a retail sales tax deduction only; retailing B&O applies to the gross sale.
- Leaving the item list blank or ticking only "Fishing" for hunting gear. The seller must document the items purchased, and the form has a separate hunting box.
- Photocopying the tribal ID and filing it instead of completing the form. DOR says the copy is not needed; the completed form is the record.
- Assuming a tribe qualifies without checking DOR's list of qualified tribes.
Common questions
- Is a rifle bought by a tribal member for hunting exempt from Washington sales tax?
- Yes, if the buyer is a member of a qualified tribe and the rifle will be used directly in hunting within the tribe's rights. Guns and hunting ammunition are on DOR's list. The seller completes form REV 27 0049 from the buyer's tribal ID.
- Does the tribal hunting exemption cover trapping supplies?
- Yes. DOR defines hunting to include trapping and lists traps, snares, fur stretching frames, pelt scrapers, scents and tanning chemicals.
- What if an item is not on DOR's list?
- The list is not exclusive. If you are unsure whether an item qualifies, DOR encourages you to request a tax ruling.
- A tribal member paid sales tax on hunting gear. Can it be refunded?
- DOR publishes a Sales Tax Refund Request for Tribes and Tribal Members/Citizens form on the same page as the exemption form.
Sources
- DOR: Tribal fishing, hunting, and gathering Sales tax; How to document; How to report; Who qualifies; Seller information; Definitions; Resources (ETA 3235, WAC 458-20-192, refund form)
- DOR: Tribal fishing, hunting, and gathering list of exempt goods and services Hunting (including trapping)
- DOR form REV 27 0049 (03/30/22), Tribal Fishing, Hunting, and Gathering Pages 1-2
- WAC 458-20-192 (6)(b) treaty fishery (background; the rule does not address hunting)
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0049: Tribal Fishing, Hunting, and Gathering
- Statute
- ETA 3235.2022
- Category
- Entity