REV 27-0049
Tribal gathering: goods and services used directly
A firm asks a customer for proof of tribal enrollment, the buyer uploads a photo of their tribal ID from the emailed link, and Sundry shows it received and checked.
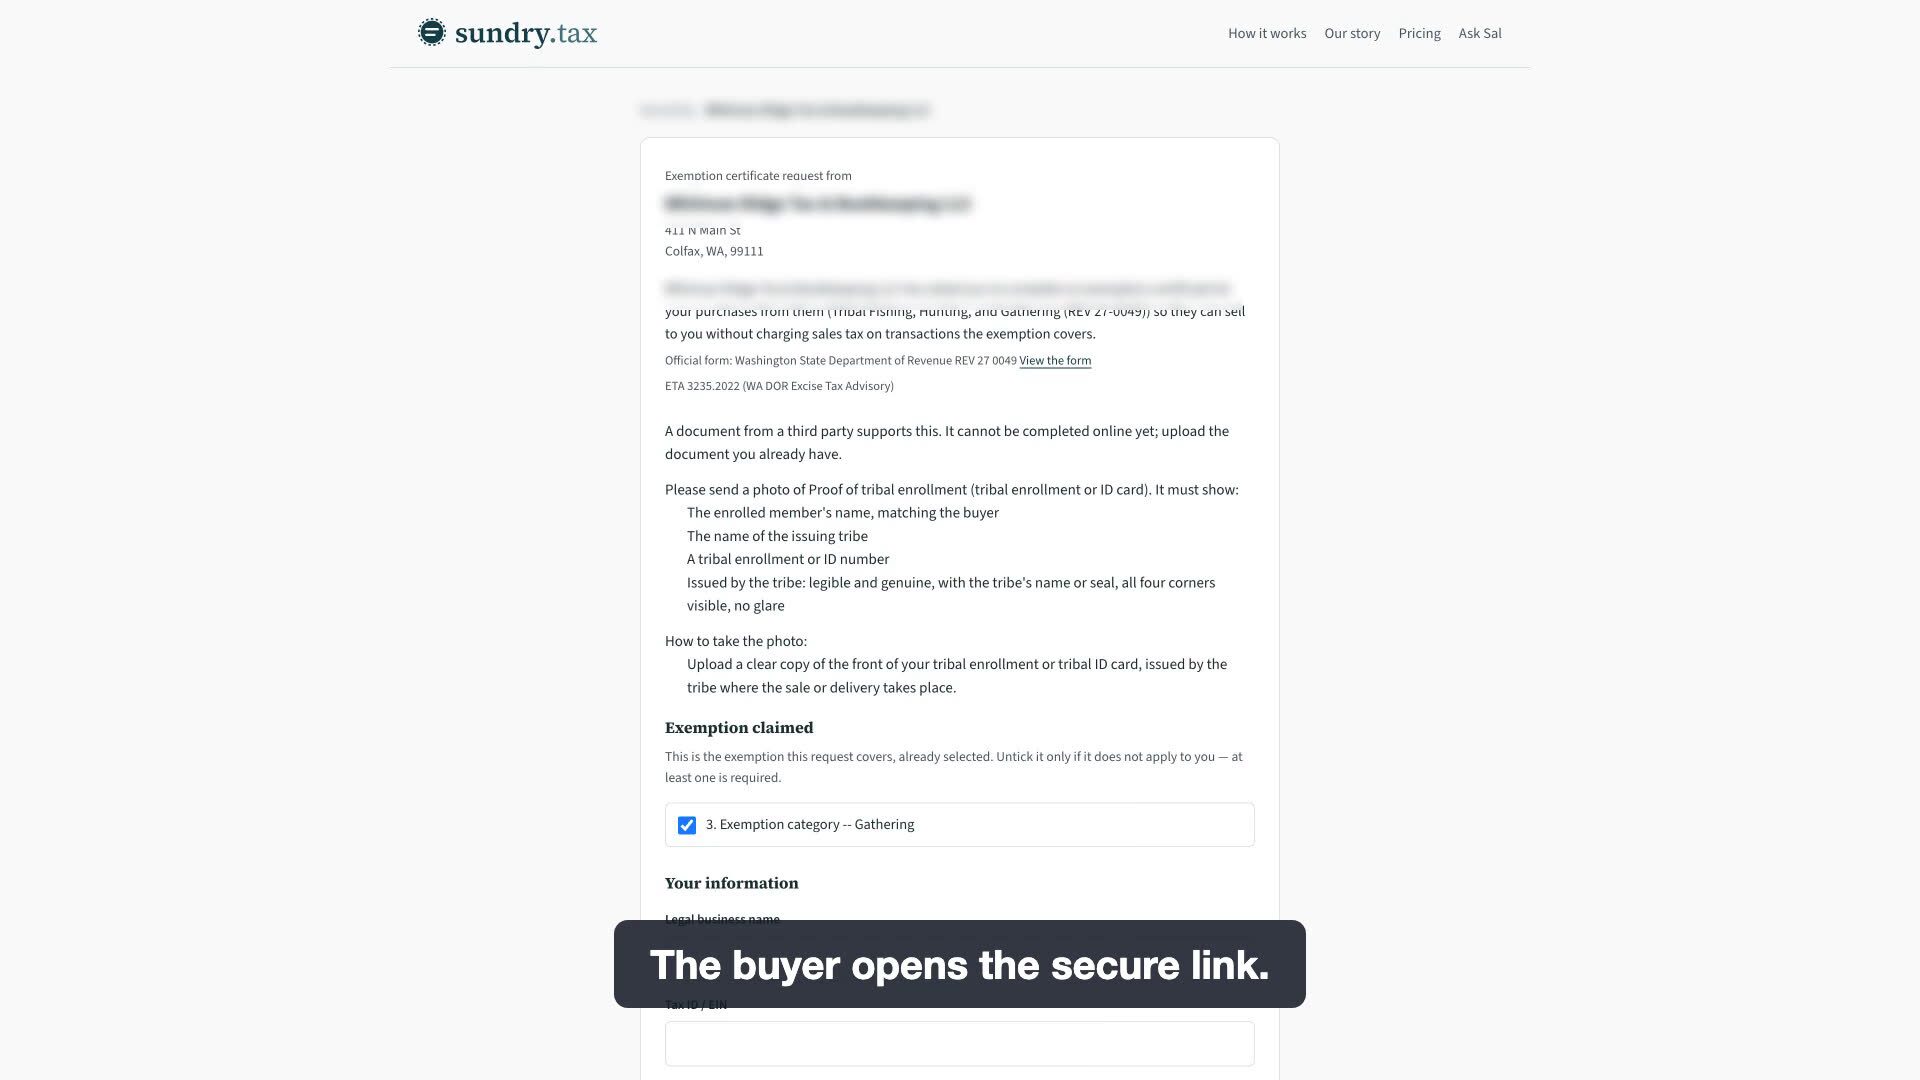
Retail sales tax does not apply to goods and retail services sold to a qualified tribe, a member of a qualified tribe, or a qualified intertribal organization and used directly in tribal gathering activities, wherever in Washington the sale or delivery takes place. Unlike most exemptions, the seller fills in the form, from the buyer's tribal identification.
Who qualifies
- A "qualified purchaser": a qualified tribe, a tribal member of a qualified tribe, or a qualified intertribal organization.
- The qualified tribes are the 32 listed in ETA 3235.2022 and on DOR's tribal fishing, hunting and gathering page, from the Confederated Tribes and Bands of the Yakama Nation to the Upper Skagit Indian Tribe.
- Qualified intertribal organizations include, in a nonexclusive list, the Columbia River Inter-tribal Fishery Commission (CRITFC), the Northwest Indian Fisheries Commission (NWIFC), the Point No Point Treaty Council and the Skagit River Systems Cooperative (SRSC).
- The gathering must be within the scope of the qualified tribe's gathering rights.
What qualifies
- Retail goods and retail services used directly in qualified gathering activities. DOR describes these activities as including harvesting, processing, transporting, selling, management, enforcement and other related activities.
- Examples on DOR's nonexclusive gathering list: axes and hatchets and their maintenance; digging equipment such as root diggers, plant snippers, scissors and shovels; lace cutters; draw knives and other knives; saws and their parts and service.
- Weaving materials: dyes, fabrics, measuring devices, needles, raffia, ribbon, twine, waxed cord and yarn.
- Wood gathering materials: axes, peaveys, prying bars, pulleys, saws, splitting mauls, wedges and winches.
- Food preparation and storage: canning jars, dehydrators, drying racks, food sealers, coolers, freezers, ice and containers; also camping gear, backpacks, binoculars, GPS and maps, rope and twine, cardboard, duct tape, seeds, repellants, safety gear, specialized gathering clothing, and parking charges incurred during gathering.
Not covered
- Purchases by members of tribes not on the qualified list, or by organizations that are not qualified intertribal organizations.
- Goods and services not used directly in tribal gathering (or fishing or hunting) activities.
- Taxes other than retail sales tax. ETA 3235.2022 is limited to the preemption of retail sales tax, and DOR says retailers still report the sale under retailing B&O tax, with no B&O deduction.
What the buyer gives
The buyer shows tribal identification. DOR: the retailer may confirm the purchaser's information "by either looking at a copy of their tribal identification card, tribal fishing card, or any documentation issued by the tribe on tribal stationery," and "does not need to keep a copy of the identification or documentation." The seller then completes form REV 27 0049 (revision 03/30/22), Tribal Fishing, Hunting, and Gathering: single use or blanket; seller's name, UBI, date and address; the buyer's name and phone "as shown on the tribal-issued identification card or other tribal documention"; the qualified tribe or intertribal organization; the category "Gathering"; and the items sold. The form has no buyer signature line. ETA 3235.2022: "the seller must complete the Tribal Fishing, Hunting, and Gathering form and maintain it in their records."
What the seller keeps
Form REV 27 0049: "The seller must keep a copy of the Tribal Fishing, Hunting and Gathering form in its records for five years after its last use," and "Seller must document tribal buyer's name, tribe, or intertribal organization, item(s) purchased, and date of purchase." Do not send it to the Department. For a blanket certificate, "For reoccuring sales to a known customer, this certificate need only be completed on an annual basis." Good faith: "A seller accepting a Tribal Fishing, Hunting and Gathering form in good faith for retail sales of qualified goods or services made to a qualified purchaser will not be held liable for any uncollected sales tax." Reporting, per DOR: report the gross sale under retail sales tax and retailing B&O tax, then take the deduction "Tribal fishing, hunting, gathering" from the state portion of retail sales tax; there is no B&O deduction. RCW 82.32.070(1) requires records for five years.
Common mistakes
- Asking the buyer to fill in and sign the form. REV 27 0049 is the seller's record, completed from the buyer's tribal documentation.
- Refusing the exemption because the store is off-reservation. It applies regardless of where delivery of the item or performance of the service occurs.
- Leaving the item list blank. The seller must document the items purchased.
- Taking a B&O deduction. DOR says there is no corresponding deduction for retailing B&O tax.
Common questions
- Can a tribal member buy gathering tools tax-free at a hardware store in Washington?
- Yes, if the buyer is a member of a qualified tribe and the tools are used directly in gathering within the tribe's gathering rights. Draw knives, lace cutters, root diggers and saws are on DOR's nonexclusive gathering list. The store completes REV 27 0049 from the buyer's tribal ID.
- Do I need to keep a copy of the tribal ID?
- No. DOR says the retailer does not need to keep a copy of the identification; noting the required information on the form is enough.
- What if an item is not on DOR's list?
- The list is not exclusive. If you are unsure whether a good or service qualifies, DOR encourages a request for a letter ruling.
- Is this exemption in a Washington statute?
- No. ETA 3235.2022, issued November 22, 2022, recognizes the preemption of retail sales tax on these purchases. DOR states it does not create or expand any rights beyond potential tax liability.
Sources
- DOR Excise Tax Advisory ETA 3235.2022 (issued 11/22/2022) Purpose; Scope; Preemption; How to Document; Definitions; Seller Information
- DOR Tribal fishing, hunting, and gathering Sales tax; How to document; How to report; Who qualifies; Seller information; Definitions
- DOR Tribal fishing, hunting, and gathering list of exempt goods and services Gathering
- DOR form REV 27 0049 (03/30/22), Tribal Fishing, Hunting, and Gathering Pages 1-2
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0049: Tribal Fishing, Hunting, and Gathering
- Statute
- ETA 3235.2022
- Category
- Entity