REV 27-0063
Live presentations bought by a school or library
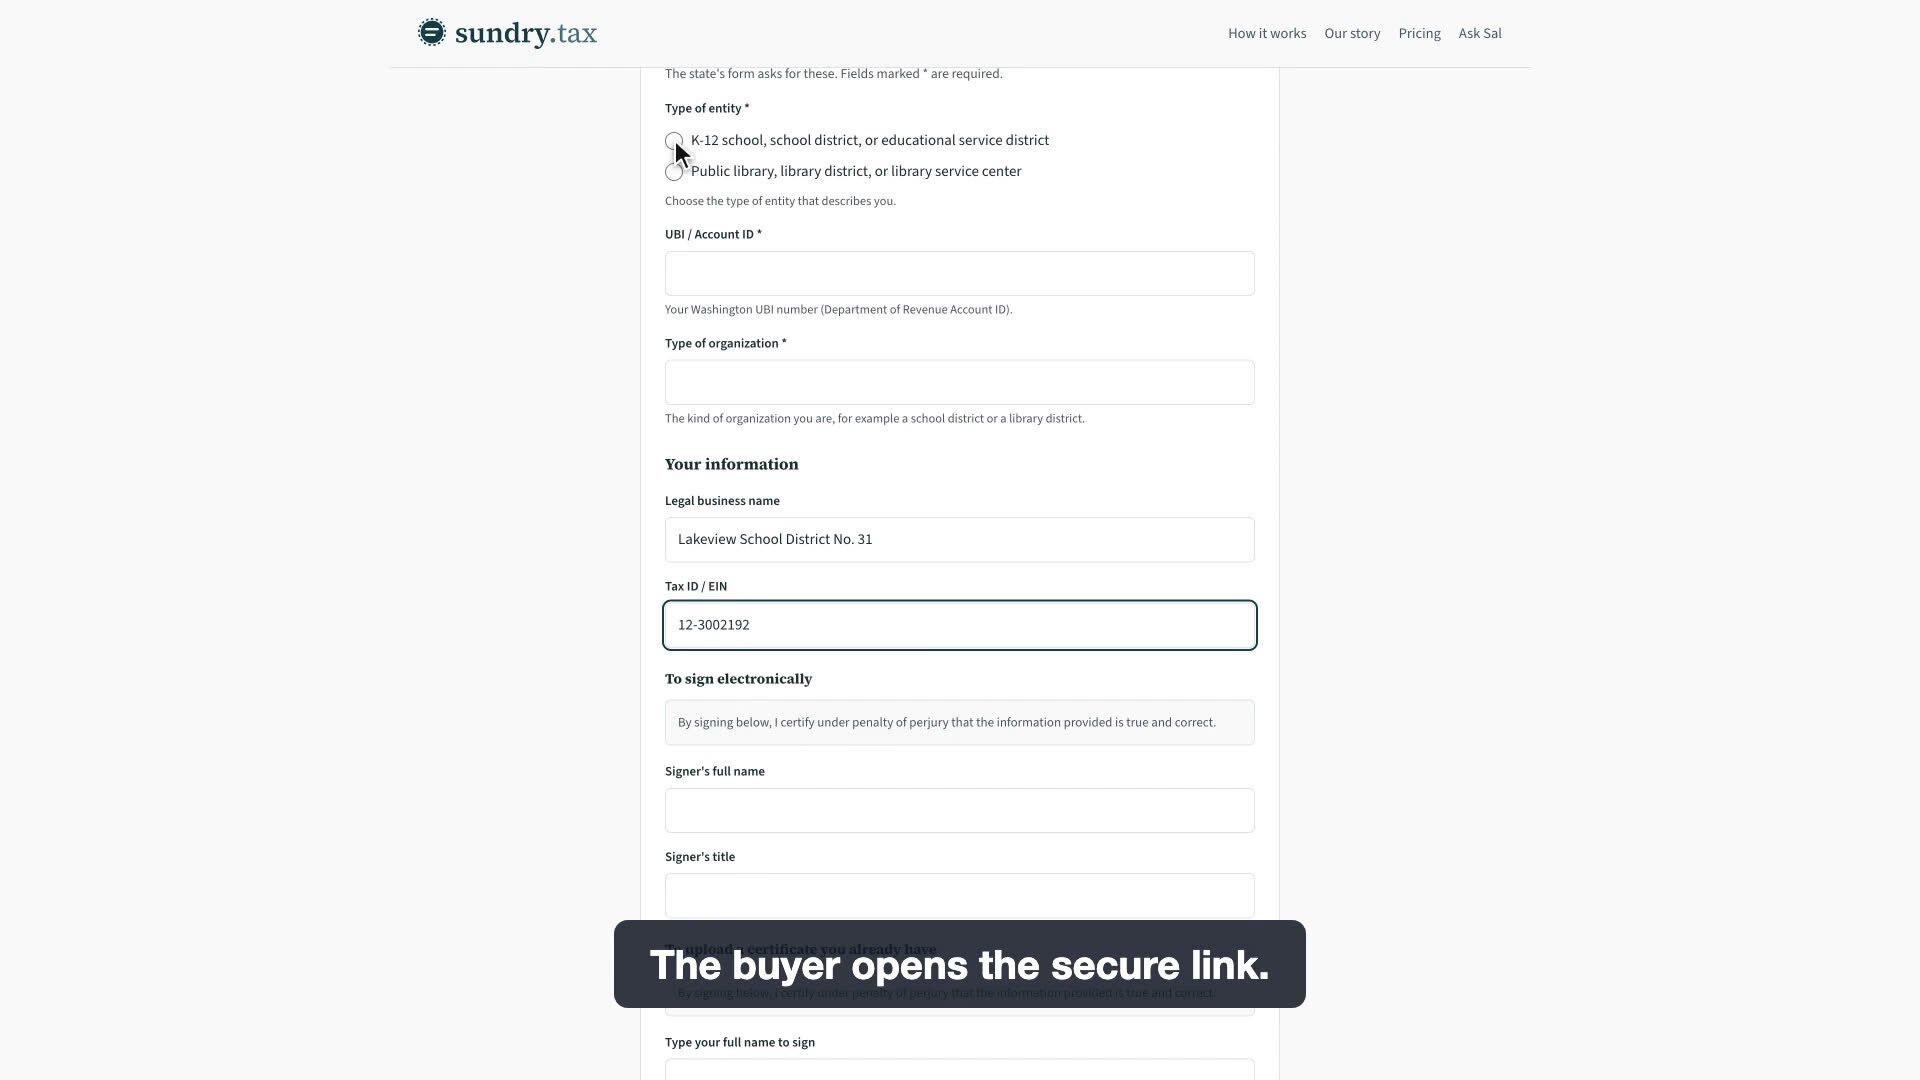
A firm asks the school or library for a signed REV 27-0063, the buyer fills in and signs it from the emailed link, and Sundry shows it signed and Verified by Sundry.
From July 1, 2026, public libraries, library districts, library service centers, K-12 schools, school districts and educational service districts pay no Washington sales tax on live presentations they buy: paid lectures, seminars, workshops and courses with real-time interaction, such as a staff training day or an author talk. The use tax statute does not list live presentations. Many events are not live presentations at all, so check the definition first.
Who qualifies
- Public libraries, library districts and library service centers.
- K-12 schools, school districts and educational service districts.
- On form REV 27 0063 the buyer ticks one of two entity boxes: "K-12 school, school district, or educational service district" or "Public library, library district, or library service center."
What qualifies
- Live presentations: lectures, seminars, workshops or courses that participants attend in person or online, where the audience and the presenter can give, receive and discuss information with each other in real time.
- DOR says the activity is meant to inform, explain, persuade or educate; is a seminar, lecture, workshop, course or similar event; allows real-time participation (though participation is not required); and allows more than one attendee.
- Examples DOR gives of live presentations: continuing education for teachers, CPR classes, and workshops or courses for personal or professional enrichment.
Not covered
- Events that are not live presentations in the first place, so no tax and no certificate is needed: musical, dramatic, comedic or similar performances (an assembly with a band or a play); one-on-one tutoring, consulting and music lessons.
- From July 1, 2026, DOR says these are also excluded from live presentations: presentations given by a nonprofit exempt under section 501(c) of the Internal Revenue Code, music lessons regardless of the number of participants, and incidental instruction tied to a performance.
- The preschool, school-class and property-tax-exempt-facility exclusions are in the text of RCW 82.04.050 as amended by 2026 c 250 s 2 and on DOR's live presentations page. The text of 2026 c 238 s 1101, effective July 1, 2026, lists different exclusions. A school or preschool class should ask DOR for a ruling.
- Content the school buys to watch later. DOR says presentations bought as a recording are generally digital goods, not live presentations.
- Use tax. RCW 82.12.710 lists IT services, website development, security, temporary staffing and custom software, but not live presentations.
What the buyer gives
Form REV 27 0063 (revision 9/2/26). The buyer ticks single use or blanket, enters the presenter's or seller's name, mailing address and date, ticks "Live presentations" under line 1 and its entity type under line 2, and signs the certification with organization name, UBI/Account ID, buyer name, title and address. A single-use certificate fits a one-off speaker; a blanket certificate fits a training provider used throughout the year.
What the seller keeps
RCW 82.08.710(2): sellers "must obtain an exemption certificate from the purchaser in a form and manner prescribed by the department" and "must retain a copy of the exemption certificate for the seller's files." Form REV 27 0063 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." DOR's special notice says to keep the form for five years, and RCW 82.32.070(1) requires records to be kept for five years. Under RCW 82.08.050(7)(a) a seller is relieved of the tax if it obtains a fully completed certificate within 90 days after the sale; (7)(b) allows 120 days after a department request. DOR: report the sale under Retailing B&O and Retail Sales, then take the "Sales of Exempt Services to Libraries and Schools" deduction from Retail Sales. The retailing B&O tax still applies. The seller should first confirm the event is a live presentation at all: if it is a performance, a one-on-one lesson, or a presentation by a 501(c) nonprofit, it is not a retail sale of a live presentation and the exemption is not needed.
Common mistakes
- Collecting a certificate for a school assembly performance. Musical, dramatic and comedic performances are not live presentations, so the sale is not taxed as one.
- Using the certificate for one-on-one coaching or tutoring. These are excluded from live presentations.
- Assuming use tax is exempt too. RCW 82.12.710 does not list live presentations; DOR's notice describes the exemption as sales and use tax, so ask DOR if use tax is at issue.
- Applying the exemption to a teacher training day held before July 1, 2026. DOR's interim guidance example of a third-party trainer presenting to a school's teachers says the trainer collects sales tax; the exemption starts July 1, 2026.
Common questions
- Does a school district pay sales tax on a paid professional development workshop?
- Not from July 1, 2026. A workshop with real-time interaction is a live presentation under RCW 82.04.050, and RCW 82.08.710(1)(c) exempts live presentations bought by school districts.
- Is a paid author talk at a public library exempt?
- If it is a lecture or discussion with real-time audience interaction, it is a live presentation and the library can give the presenter form REV 27 0063. If the presenter is a 501(c) nonprofit, DOR says the presentation is excluded from live presentations from July 1, 2026, so no sales tax applies anyway.
- Is a concert for students a live presentation?
- No. RCW 82.04.050 says live presentations do not include musical, dramatic, comedic or similar performances.
- Do schools charge sales tax on classes they teach?
- DOR's interim guidance says public and private elementary and secondary schools are not providing live presentations when they offer lectures, courses or other programs, so those charges are not retail sales.
Sources
- RCW 82.08.710 (1)(c), (2); effective July 1, 2026 (2026 c 238)
- RCW 82.12.710 (1)(a)-(e): live presentations not listed
- RCW 82.04.050 (as amended by 2026 c 250 s 2 and 2026 c 238 s 1101) (3)(l)(i)-(ii)
- DOR form REV 27 0063 (9/2/26), Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries Page 1 single use/blanket, line 1 type of purchase, line 2 type of entity; page 2 certification and retention
- DOR Special Notice (April 3, 2026): New sales/use tax exemption for purchases of certain retail services by schools and libraries Whole notice: reporting, documentation, pre-July 2026 sales, guidance status
- DOR: Live presentations What is a live presentation?; What's included; What's NOT included
- DOR: Live presentations (services newly subject to retail sales tax) Exclusions
- DOR Special Notice (April 3, 2026): Live presentations: New exclusions from retail sales What are the new exclusions?
- DOR Interim statement: live presentations for schools and institutions of higher education (revised November 14, 2025) Public and private elementary and secondary schools; Example 3
- RCW 82.08.050 (4), (7)(a)-(c)
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0063: Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries
- Statute
- RCW 82.08.710(1)
- Category
- Entity
- How the buyer provides it
- Signs the state form in the buyer portal