REV 27-0063
Information technology services bought by a school or library
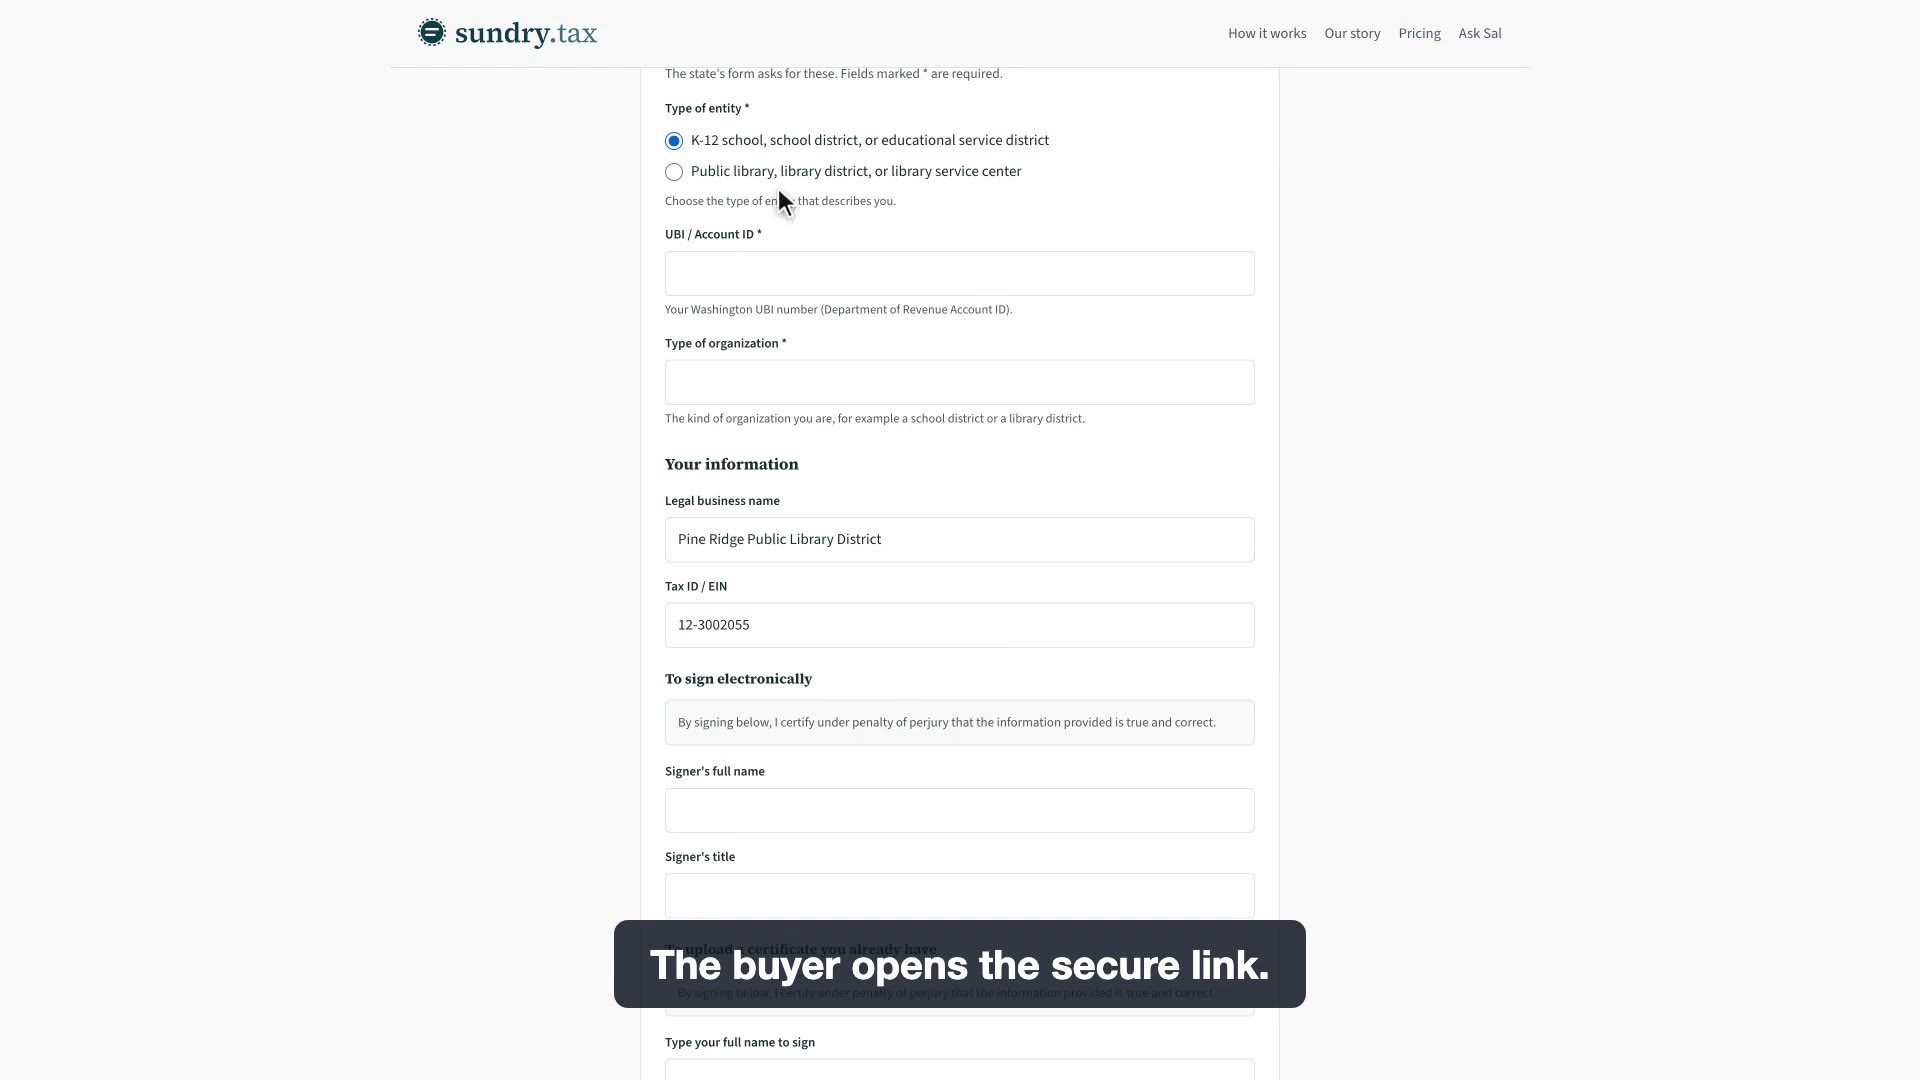
A firm asks the school or library for a signed REV 27-0063, the buyer fills in and signs it from the emailed link, and Sundry shows it signed and Verified by Sundry.
From July 1, 2026, public libraries, library districts, library service centers, K-12 schools, school districts and educational service districts pay no Washington sales or use tax on information technology services, such as help desk, network support, IT training, managed IT, data entry and data processing. Software subscriptions are not IT services and stay taxable. Web hosting and domain names are not IT services either, and DOR does not treat them as retail sales. The buyer gives the seller form REV 27 0063.
Who qualifies
- Public libraries, library districts and library service centers.
- K-12 schools, school districts and educational service districts.
- On form REV 27 0063 the buyer ticks one of two entity boxes: "K-12 school, school district, or educational service district" or "Public library, library district, or library service center."
What qualifies
- Information technology services as the statute defines them: IT training services, technical support, assisting with network operations and support, help desk services, in-person training on hardware or software, network system support, data entry and data processing.
- DOR's interim guidance counts any service that supports or assists IT infrastructure, for example network assessments, planning, design and migration; network security; system upgrades and maintenance; onboarding and offboarding users; managed IT services; IT consulting and project management; troubleshooting hardware and software.
- Use of IT services is also exempt from use tax (RCW 82.12.710(1)(a)).
Not covered
- Payment processing (DOR: not an IT service). Web hosting and domain name registration are not IT services either, but DOR does not treat them as retail sales, so no sales tax or certificate is involved.
- Digital automated services, including software as a service, and remote access software. DOR classifies these separately, and the exemption list in RCW 82.08.710 does not name them.
- Telecommunications services.
- Custom website development and custom software or customization of prewritten software. These are exempt too, but they are separate services with their own boxes on line 1 of form REV 27 0063; tick each one bought.
- IT services bought before July 1, 2026, unless DOR's existing contract treatment applied.
What the buyer gives
Form REV 27 0063 (revision 9/2/26). The buyer ticks single use or blanket, enters the seller's name, mailing address and date, ticks "Information technology services" under line 1 (and any other line 1 boxes that apply, such as "Custom website development services"), ticks its entity type under line 2, and completes the certification block with UBI/Account ID, organization name, buyer name, title, address and signature. A blanket certificate suits a managed IT contract: it works while there is at least one sale within 12 months.
What the seller keeps
RCW 82.08.710(2): sellers "must obtain an exemption certificate from the purchaser in a form and manner prescribed by the department" and "must retain a copy of the exemption certificate for the seller's files." Form REV 27 0063 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." DOR's special notice says to keep the form for five years, and RCW 82.32.070(1) requires records to be kept for five years. Under RCW 82.08.050(7)(a) a seller is relieved of the tax if it obtains a fully completed certificate within 90 days after the sale; (7)(b) allows 120 days after a department request. DOR: report the sale under Retailing B&O and Retail Sales, then take the "Sales of Exempt Services to Libraries and Schools" deduction from Retail Sales. The retailing B&O tax still applies.
Common mistakes
- Using the certificate for a software subscription. DOR treats software as a service as a digital automated service, not an IT service, and the statute does not exempt it for schools and libraries.
- Billing exempt IT support and taxable items for one price. DOR's IT guidance says two distinct products sold for one nonitemized price are generally a bundled transaction taxed as a retail sale, while separately itemized products are each taxed by their own classification. Itemize the IT service.
- Ticking only the IT box for a website build. Custom website development is a separate line 1 box.
- Charging the district on a contract signed before July 1, 2026 for services delivered after that date without checking the date of service. The exemption covers purchases on or after July 1, 2026; the form says so.
Common questions
- Does a Washington school district pay sales tax on managed IT services?
- Not from July 1, 2026. RCW 82.08.710(1)(a) exempts information technology services bought by school districts, and DOR's guidance lists managed IT services as IT services.
- Is our library's cloud software subscription exempt under this certificate?
- No. DOR classifies software as a service as a digital automated service, separate from IT services, and the school and library exemption does not list digital automated services.
- Does in-person training on new classroom software count?
- Yes. The statute names in-person training related to hardware or software as an IT service.
- Do we need a separate certificate for each IT invoice?
- No. Form REV 27 0063 can be a blanket certificate, valid while the buyer and seller have at least one sale within 12 months.
Sources
- RCW 82.08.710 (1)(a)-(f), (2); effective July 1, 2026 (2026 c 238)
- RCW 82.12.710 (1)(a)-(e), (2) use tax
- RCW 82.04.050 (as amended by 2026 c 250) (3)(g), (i), (j), (l)
- DOR form REV 27 0063 (9/2/26), Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries Page 1 single use/blanket, line 1 type of purchase, line 2 type of entity; page 2 certification and retention
- DOR Special Notice (April 3, 2026): New sales/use tax exemption for purchases of certain retail services by schools and libraries Whole notice: reporting, documentation, pre-July 2026 sales, guidance status
- DOR Interim guidance: ESSB 5814 information technology services (September 12, 2025) What is the tax treatment of IT Services?; IT Services do not include; bundled sales question; Do state and local governments have to pay
- DOR: Services newly subject to retail sales tax Services now taxable table; Can these services be resold?
- RCW 82.08.050 (4), (7)(a)-(c)
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0063: Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries
- Statute
- RCW 82.08.710(1); RCW 82.12.710(1)
- Category
- Entity
- How the buyer provides it
- Signs the state form in the buyer portal