REV 27-0063
Investigation, security and armored car services bought by a school or library
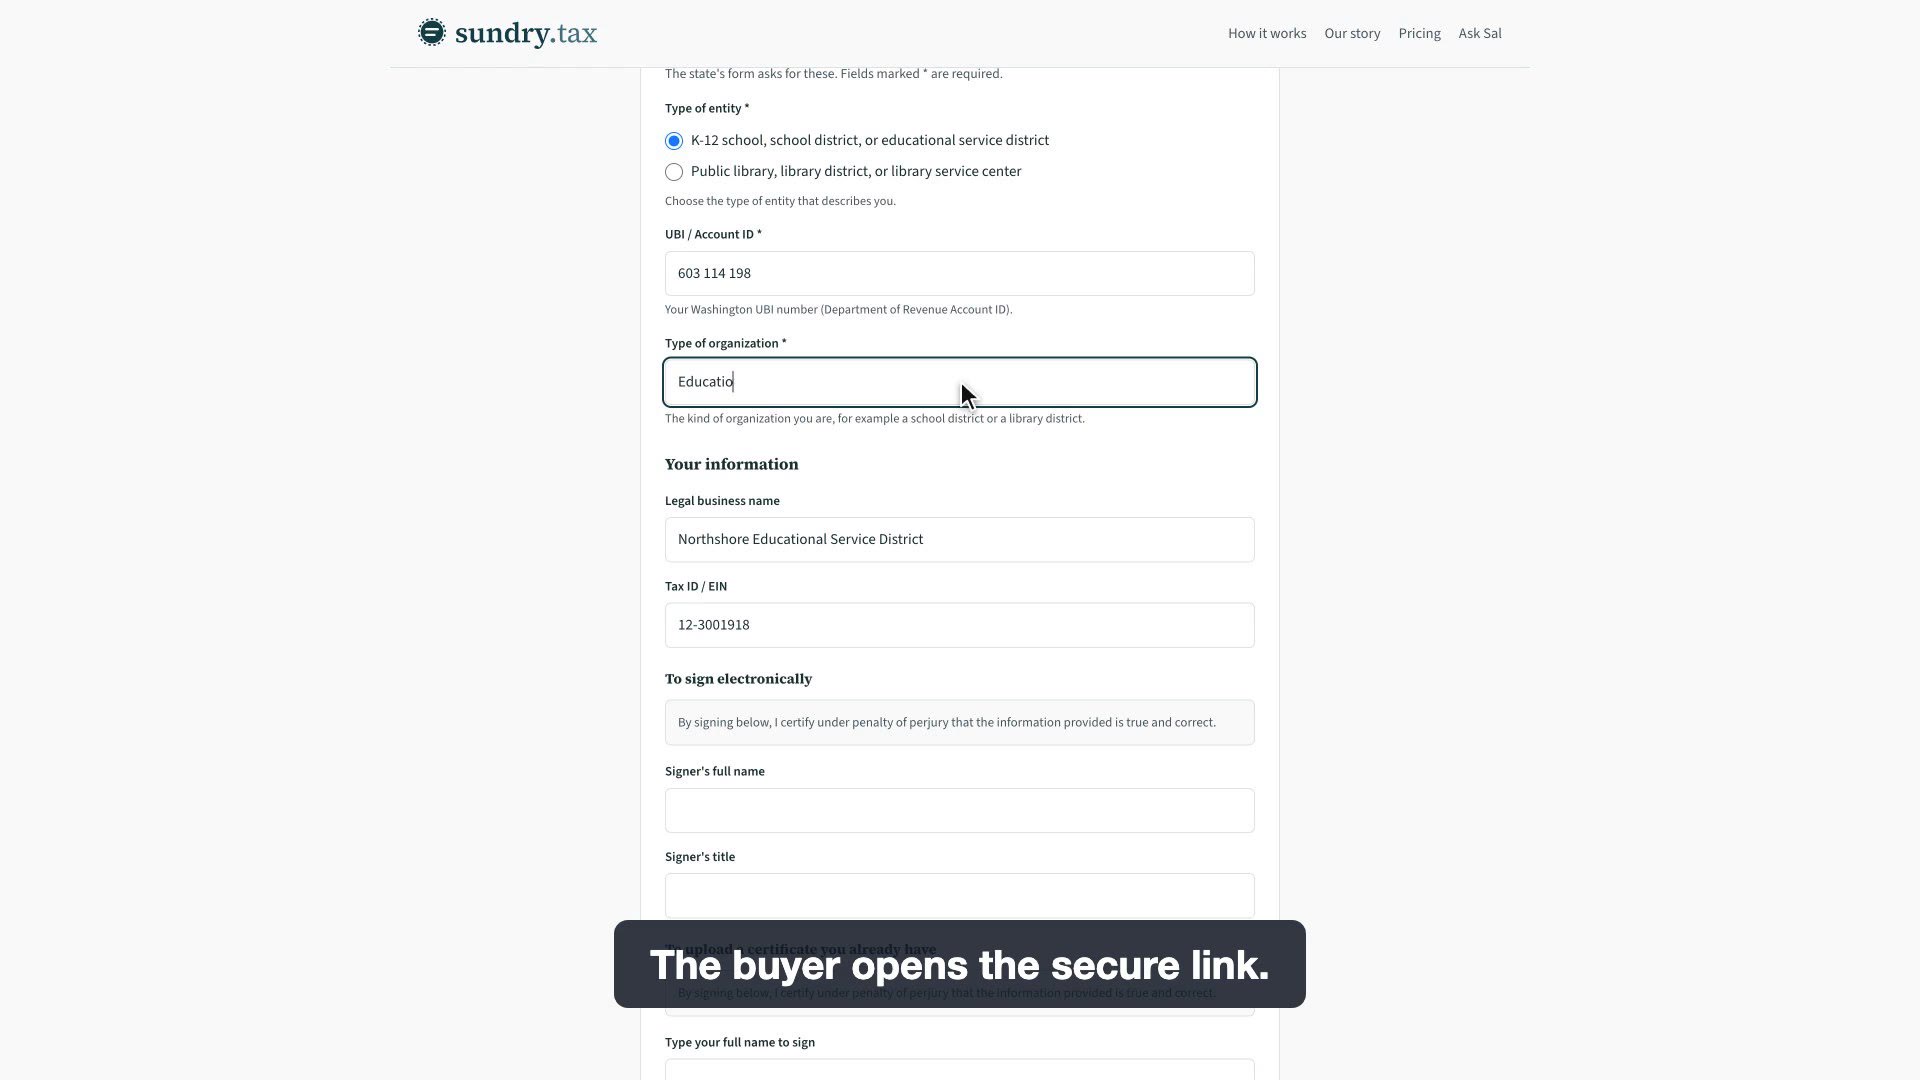
A firm asks the school or library for a signed REV 27-0063, the buyer fills in and signs it from the emailed link, and Sundry shows it signed and Verified by Sundry.
From July 1, 2026, public libraries, library districts, library service centers, K-12 schools, school districts and educational service districts pay no Washington sales or use tax on investigation, security, security monitoring and armored car services. Examples are guard and patrol services, background checks on job candidates, event security, and armored car pickups of cash. The buyer gives the seller form REV 27 0063.
Who qualifies
- Public libraries, library districts and library service centers.
- K-12 schools, school districts and educational service districts.
- On form REV 27 0063 the buyer ticks one of two entity boxes: "K-12 school, school district, or educational service district" or "Public library, library district, or library service center."
What qualifies
- Security guard and patrol services, and personal and event security, such as guards for a school event or a library after hours.
- Security system services and security monitoring.
- Armored car transportation of cash and valuables.
- Investigation services, which the statute defines as investigation, detective and personal background check services: private detective services, background checks, fingerprint services, bounty hunting, private investigation, lie detection and polygraph services, missing person tracing and skip tracing. DOR treats this as the complete list of investigation services for now.
- Use of these services is also exempt from use tax (RCW 82.12.710(1)(c)).
Not covered
- Locksmith services (excluded by the statute).
- Forensic accounting, process servers, and internal HR investigations not bought from a third party (DOR interim guidance says these are not investigation or security services at all).
- Cyber security services. DOR classifies these as information technology services, which is a different box on the same form.
- Security services bought before July 1, 2026. DOR says tax applied through June 30, 2026 unless the sale met its existing contract treatment.
- Buyers that are not on the statute's list, such as colleges and universities, nonprofits and other local governments. DOR says state and local governments otherwise pay retail sales tax on these services.
What the buyer gives
Form REV 27 0063 (revision 9/2/26), which "Can be used for purchases on or after July 1, 2026." The buyer ticks single use or blanket, enters the seller's name, mailing address and the date, ticks "Investigation, security, and armored car services" under line 1, ticks its entity type under line 2, and completes the certification: type of organization, UBI/Account ID, organization name, buyer name and title, street address and signature. A blanket certificate works while the buyer and seller have at least one sale within 12 months.
What the seller keeps
RCW 82.08.710(2): sellers "must obtain an exemption certificate from the purchaser in a form and manner prescribed by the department" and "must retain a copy of the exemption certificate for the seller's files." Form REV 27 0063 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." DOR's special notice says to keep the form for five years, and RCW 82.32.070(1) requires records to be kept for five years. Under RCW 82.08.050(7)(a) a seller is relieved of the tax if it obtains a fully completed certificate within 90 days after the sale; (7)(b) allows 120 days after a department request. DOR: report the sale under Retailing B&O and Retail Sales, then take the "Sales of Exempt Services to Libraries and Schools" deduction from Retail Sales. The retailing B&O tax still applies.
Common mistakes
- Treating a locksmith job as security work. The statute excludes locksmith services, so they get no exemption under this certificate.
- Ticking only "Investigation, security, and armored car services" for network security work. DOR classifies cyber security as an IT service; tick the IT box for that work.
- Assuming alarm monitoring is always a security service. DOR's interim guidance addresses alarm monitoring separately; ask DOR for a ruling.
- Leaving the seller's name or the buyer's UBI/Account ID blank. RCW 82.08.050(7)(a) relieves the seller only for a fully completed certificate.
Common questions
- Does a school district pay sales tax on security guards in Washington?
- Not from July 1, 2026. RCW 82.08.710 exempts security guard and patrol services bought by K-12 schools, school districts and educational service districts. The district gives the guard company form REV 27 0063.
- Are background checks for new library or school staff exempt?
- Yes. Background check services are investigation services under RCW 82.04.050, and RCW 82.08.710(1)(d) exempts investigation services bought by these buyers.
- Is armored car pickup of cafeteria or library fine cash covered?
- Yes. The statute lists armored car transportation of cash and valuables as an armored car service, and the exemption covers armored car services.
- Does the exemption cover rekeying locks?
- No. RCW 82.04.050 says investigation and security services do not include locksmith services.
Sources
- RCW 82.08.710 (1)(a)-(f), (2); effective July 1, 2026 (2026 c 238)
- RCW 82.12.710 (1)(a)-(e), (2) use tax
- RCW 82.04.050 (as amended by 2026 c 250) (3)(g), (i), (j), (l)
- DOR form REV 27 0063 (9/2/26), Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries Page 1 single use/blanket, line 1 type of purchase, line 2 type of entity; page 2 certification and retention
- DOR Special Notice (April 3, 2026): New sales/use tax exemption for purchases of certain retail services by schools and libraries Whole notice: reporting, documentation, pre-July 2026 sales, guidance status
- DOR Interim guidance: ESSB 5814 investigation, security, security monitoring, and armored car services What are investigation, security, security monitoring, and armored car services?; Alarm monitoring services; do not include
- DOR: Services newly subject to retail sales tax Services now taxable table; Can these services be resold?
- RCW 82.08.050 (4), (7)(a)-(c)
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0063: Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries
- Statute
- RCW 82.08.710(1); RCW 82.12.710(1)
- Category
- Entity
- How the buyer provides it
- Signs the state form in the buyer portal