REV 27-0063
Custom website development bought by a school or library
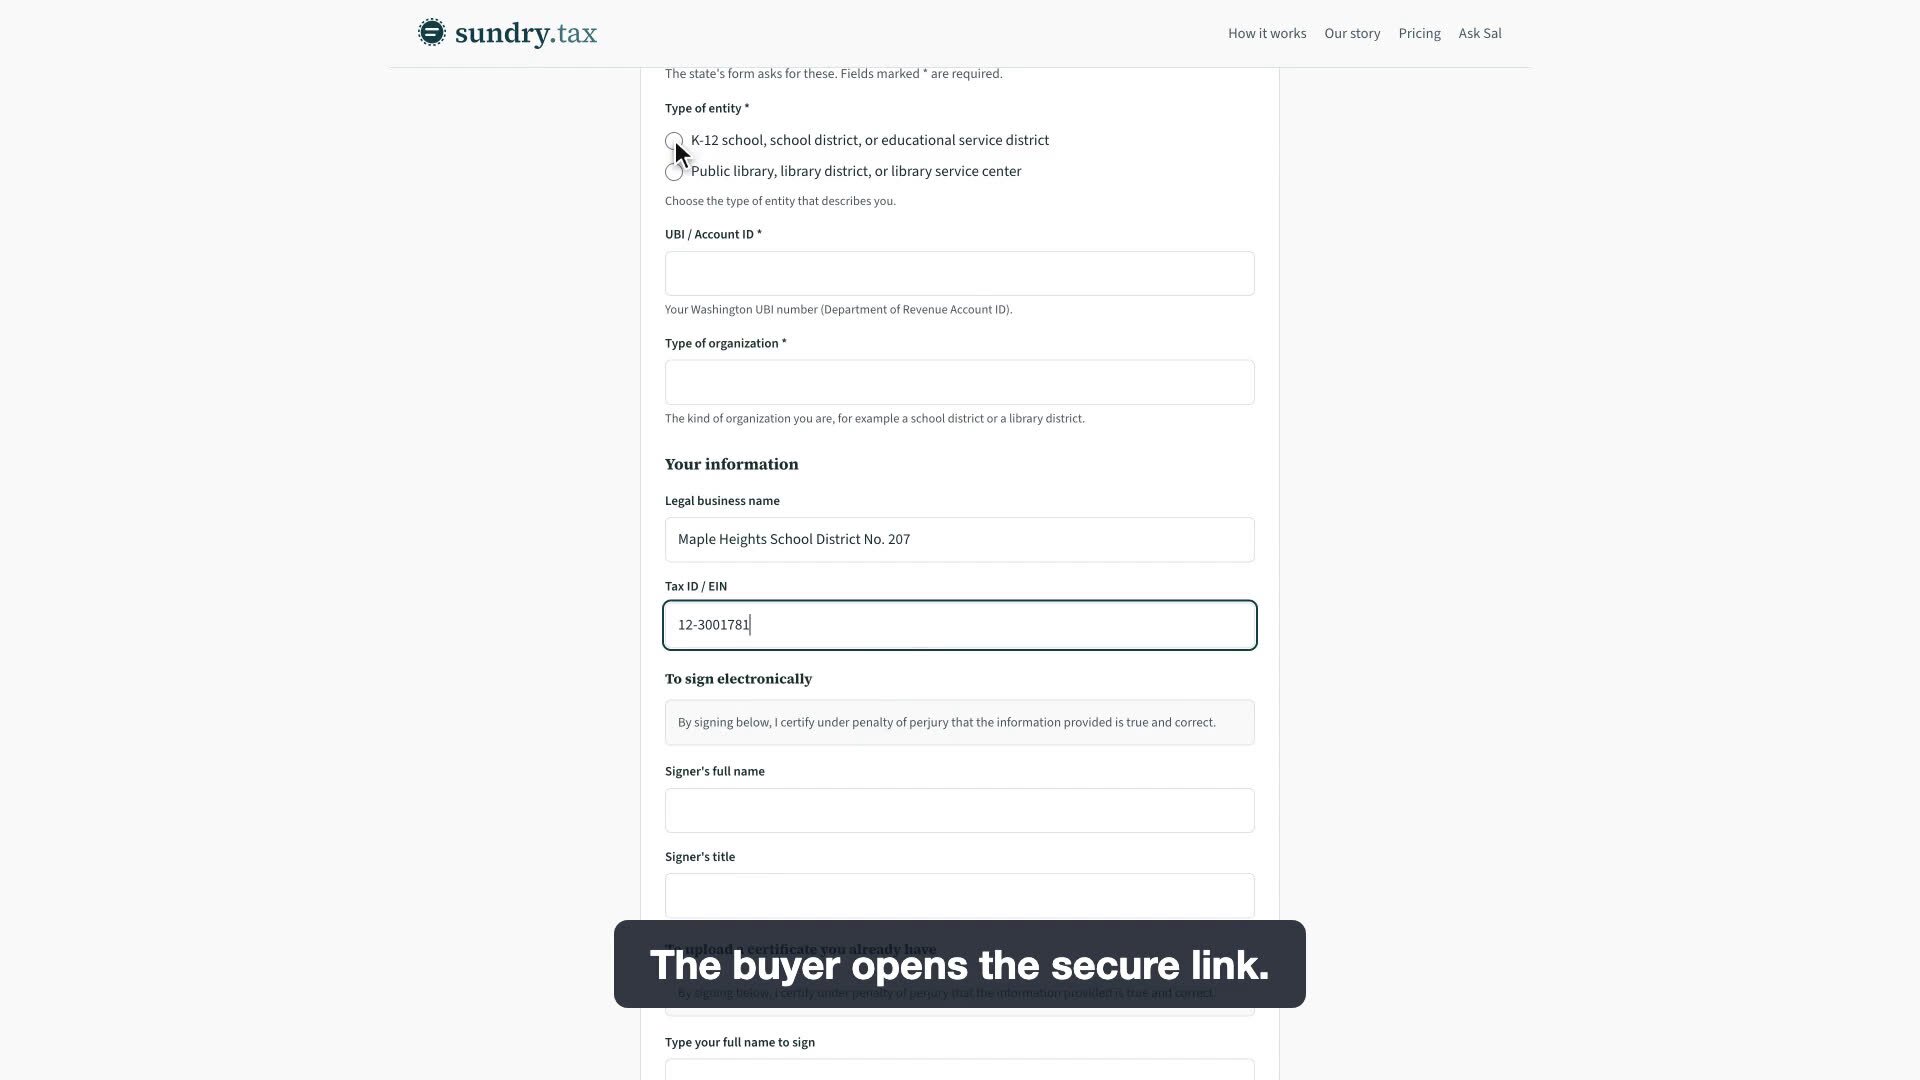
A firm asks the school or library for a signed REV 27-0063, the buyer fills in and signs it from the emailed link, and Sundry shows it signed and Verified by Sundry.
From July 1, 2026, K-12 schools, school districts, educational service districts, public libraries, library districts and library service centers pay no Washington sales or use tax on custom website development: design, development and support of their websites, including website consulting and training. Hosting, domain names and online advertising services are separate and outside this exemption.
Who qualifies
- Public libraries, library districts, library service centers, K-12 schools, school districts and educational service districts (RCW 82.08.710(1), 82.12.710(1)).
- Colleges and universities are not on the list.
- Purchases on or after July 1, 2026 (2026 c 238, ESSB 6346).
What qualifies
- "Website development services": the design, development and support of a website provided by a website developer to a customer (RCW 82.04.050(3)(h)).
- DOR: website design (planning, analysis, engineering, programming, testing, deployment), frontend, backend or full-stack development, and support such as testing new applications, monitoring site performance and website optimization.
- Website consulting and training that support the site's functionality and operation, for example training staff to update the site (DOR interim guidance, Example 2).
- Work on new and existing websites.
- Sales tax: RCW 82.08.710(1)(b). Use tax: RCW 82.12.710(1)(b).
Not covered
- Web hosting and domain name registration, which DOR says are not website development services.
- Advertising services such as search engine marketing, online referrals, lead generation optimization, web campaign planning and monitoring site traffic to measure an advertising campaign. These are "advertising services" in RCW 82.04.050(3)(k), a separate category not on the exemption list.
- Purchases before July 1, 2026, unless they met DOR's existing contract treatment.
- Buyers not on the list, such as colleges and other local governments.
What the buyer gives
Form REV 27 0063, Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries (revision 9/2/26), which says it "Can be used for purchases on or after July 1, 2026." The buyer ticks single use or blanket (at least one sale within 12 months), enters the vendor's name, mailing address and the date, ticks the type of purchase, ticks the type of entity ("K-12 school, school district, or educational service district" or "Public library, library district, or library service center"), and completes the certification: type of organization, UBI/Account ID, organization name, buyer name and title, street address and signature. For this purpose the type of purchase is "Custom website development services." The buyer must make sure it is entitled to the exemption before using the certificate.
What the seller keeps
RCW 82.08.710(2): sellers "must obtain an exemption certificate from the purchaser in a form and manner prescribed by the department" and "must retain a copy of the exemption certificate for the seller's files." Form REV 27 0063 says the seller "must retain the original of this certificate for their records" and not send it to the Department. DOR's special notice of April 3, 2026: keep the form five years; report the sale under the retailing B&O and retail sales tax classifications, then take the "Sales of Exempt Services to Libraries and Schools" deduction from retail sales tax. Retailing B&O tax still applies. If the developer subcontracts part of the job, DOR interim guidance allows it to give the subcontractor its reseller permit when it is contractually responsible for the services to the school or library and has no intervening use of them. Document in the contract where the service is received, which is where it is sourced. RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when the department asks; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Including search engine marketing or ad campaign work. That is an advertising service, not website development.
- Including hosting or domain renewals in the exempt line.
- Ticking "Information technology services" for a website project. The form has a separate "Custom website development services" box; tick each that applies.
- Relying on DOR's 2025 website interim guidance statement that state and local governments pay sales tax on these services. For the listed schools and libraries the 2026 exemption applies from July 1, 2026.
Common questions
- Do public libraries in Washington pay sales tax on website design?
- Not for purchases on or after July 1, 2026. Custom website development services bought by public libraries, library districts and library service centers are exempt under RCW 82.08.710. The library gives the developer form REV 27 0063.
- Is website training for school staff exempt?
- Yes, from July 1, 2026. DOR treats website consulting and training that support the site's functionality as website development services.
- Is web hosting for a school website exempt under this certificate?
- Hosting is not website development and is not covered by this exemption. DOR's digital products page says charges for web hosting are subject to service and other activities B&O tax and that sales tax does not apply.
Sources
- RCW 82.08.710 (1)(b), (2); notes (effective July 1, 2026)
- RCW 82.12.710 (1)(b), (2)
- RCW 82.04.050 (3)(h) website development; (3)(k) advertising services (as amended by 2026 c 250)
- DOR form REV 27 0063 (9/2/26), Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries Pages 1-2
- DOR special notice: New sales/use tax exemption for purchases of certain retail services by schools and libraries (Apr. 3, 2026) Whole notice
- DOR interim guidance: custom website development services (Sept. 12, 2025) Background; Examples 1-2; sourcing; resale; state and local governments
- DOR: Custom website development Whole page
- DOR: Digital products including digital goods Digital automated services exclusions (storage and hosting)
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0063: Sales Tax Exemption Certificate for Purchases Certain Retail Services by Schools and Libraries
- Statute
- RCW 82.08.710(1); RCW 82.12.710(1)
- Category
- Entity
- How the buyer provides it
- Signs the state form in the buyer portal