REV 27-0032
Ride-sharing vehicles for qualifying rideshare programs
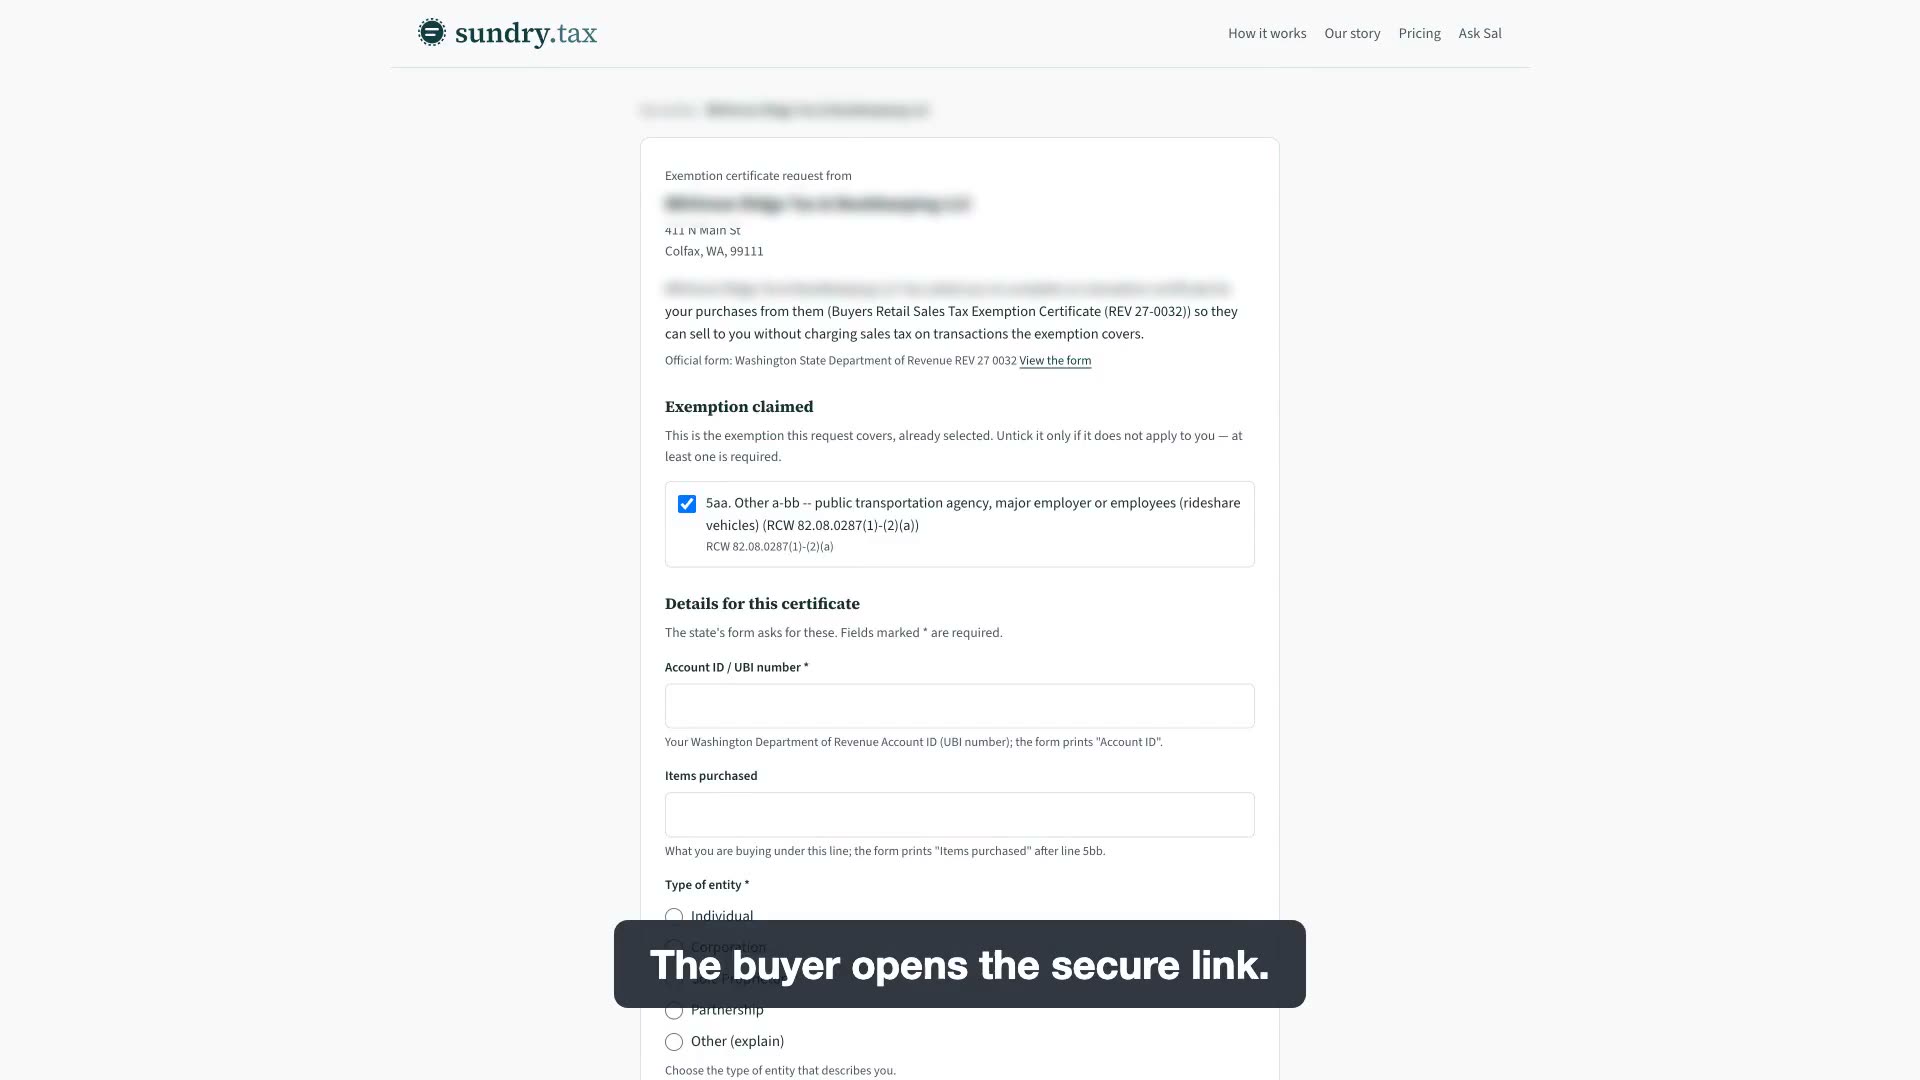
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Carpool and vanpool vehicles bought for a commute trip reduction program or a public transit ride-share program are exempt from Washington sales and use tax, if they stay in ride-share service for 36 consecutive months. Who operates the vehicle, where it runs and how many people ride all matter, and ordinary passenger transport businesses are excluded.
Who qualifies
- A public transportation agency operating the vehicle for the benefit of the general public.
- A major employer, as defined in RCW 70A.15.4010, using the vehicle as an element of its commute trip reduction program. The employer must certify that the arrangement conforms to a carpool or vanpool element of that program.
- An individual employee who owns and operates the vehicle and registers it with the employer's commute trip reduction program or with a public transportation agency. The employee needs certification of that registration.
- For vehicles carrying three or more people including the driver: the vehicle must run in one of the eight largest counties required to have commute trip reduction plans, in another county or city that adopts such a plan, or in a county where it is registered with or operated by a public transportation agency.
- Unless a public transportation agency operates it, the vehicle must carry at least five passengers in ride sharing.
What qualifies
- Passenger motor vehicles used primarily for "ride sharing": a carpool or vanpool for groups of three to 15 people including drivers, in a passenger motor vehicle with a gross vehicle weight of 10,000 pounds or less.
- Vehicles used for ride sharing for persons with special transportation needs: groups transported by a public social service agency or private nonprofit transportation provider in small buses, cutaways and modified vans not more than 28 feet long.
- The vehicle must be used as a ride-sharing vehicle for 36 consecutive months from the date of purchase (for use tax, from the date of first use).
Not covered
- Transportation provided in the normal course of business by entities regulated under chapters 46.72A, 48.177, 81.66, 81.68, 81.70 and 81.72 RCW. The definition of ride sharing excludes them.
- Vehicles offered for peer-to-peer car sharing, where owners rent their vehicles to others for short periods.
- Passenger vehicles over 10,000 pounds gross vehicle weight, or groups over 15 people, for ordinary ride sharing.
- A vehicle that leaves ride-share service before 36 consecutive months. The exemption is conditioned on that period of use.
- An employee-owned car that is not registered with the employer's program or a public transportation agency.
What the buyer gives
Form REV 27 0032 (revision 6/17/25), line 5aa: "Ride-sharing vehicles to be used in certain rideshare programs." The instructions say 5aa applies to purchases "by a public transportation agency, a major employer, or employees of major employers, to be primarily used for ride sharing or ride sharing for persons with special transportation needs," and that the vehicle and its use must meet RCW 82.08.0287. List the vehicle under "Items purchased" and complete the certification block (type of entity, type of business, Account ID, name, title, address, signature). Line 5s of the same form ("Paratransit vehicles purchased by paratransit service providers") also cites RCW 82.08.0287 and describes small buses, cutaways and modified vans bought by a public social service agency or private nonprofit provider.
What the seller keeps
RCW 82.08.0287 has no certificate clause of its own; the department's certificate is form REV 27 0032. Keep with it the employer's or the employee's certification that the statute requires, where one applies. Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Assuming any company van qualifies. The vehicle must serve a commute trip reduction program or a public transportation agency, in a qualifying county, and carry at least five riders unless an agency operates it.
- Selling or repurposing the vehicle before it has been used as a ride-sharing vehicle for 36 consecutive months.
- Skipping the paperwork for an employee-owned vehicle. The statute requires certification that it is registered with a major employer or a public transportation agency.
- Using it for a passenger transport business. Transportation provided in the normal course of business by entities under the listed chapters is outside the definition of ride sharing.
Common questions
- Can an employee buy a minivan for a vanpool without sales tax?
- Yes, if the employee owns and operates it, registers it with the employer's commute trip reduction program or a public transportation agency, operates it in a qualifying county, carries at least five riders, and keeps it in ride-share service for 36 consecutive months.
- How many people have to ride?
- Ride sharing means groups of three to 15 including drivers. Unless a public transportation agency operates the vehicle, it must transport at least five passengers.
- Is this exemption permanent?
- No. The reviser's note on RCW 82.08.0287 says the tax preference expires January 1, 2032.
- Is there a matching use tax exemption?
- Yes. RCW 82.12.0282 exempts the use of the same vehicles if they are used as ride-sharing vehicles for 36 consecutive months from the date of first use.
Sources
- RCW 82.08.0287 (1)-(2); reviser's note on 2032 expiration
- RCW 82.12.0282 Matching use tax exemption
- RCW 46.74.010 (2) "ride sharing"; (3) ride sharing for persons with special transportation needs
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 3 lines 5s and 5aa; page 4 certification; page 7 line 5s and 5aa instructions
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.0287
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal