SSTGB F0003
Streamlined sales tax certificate of exemption (resale)
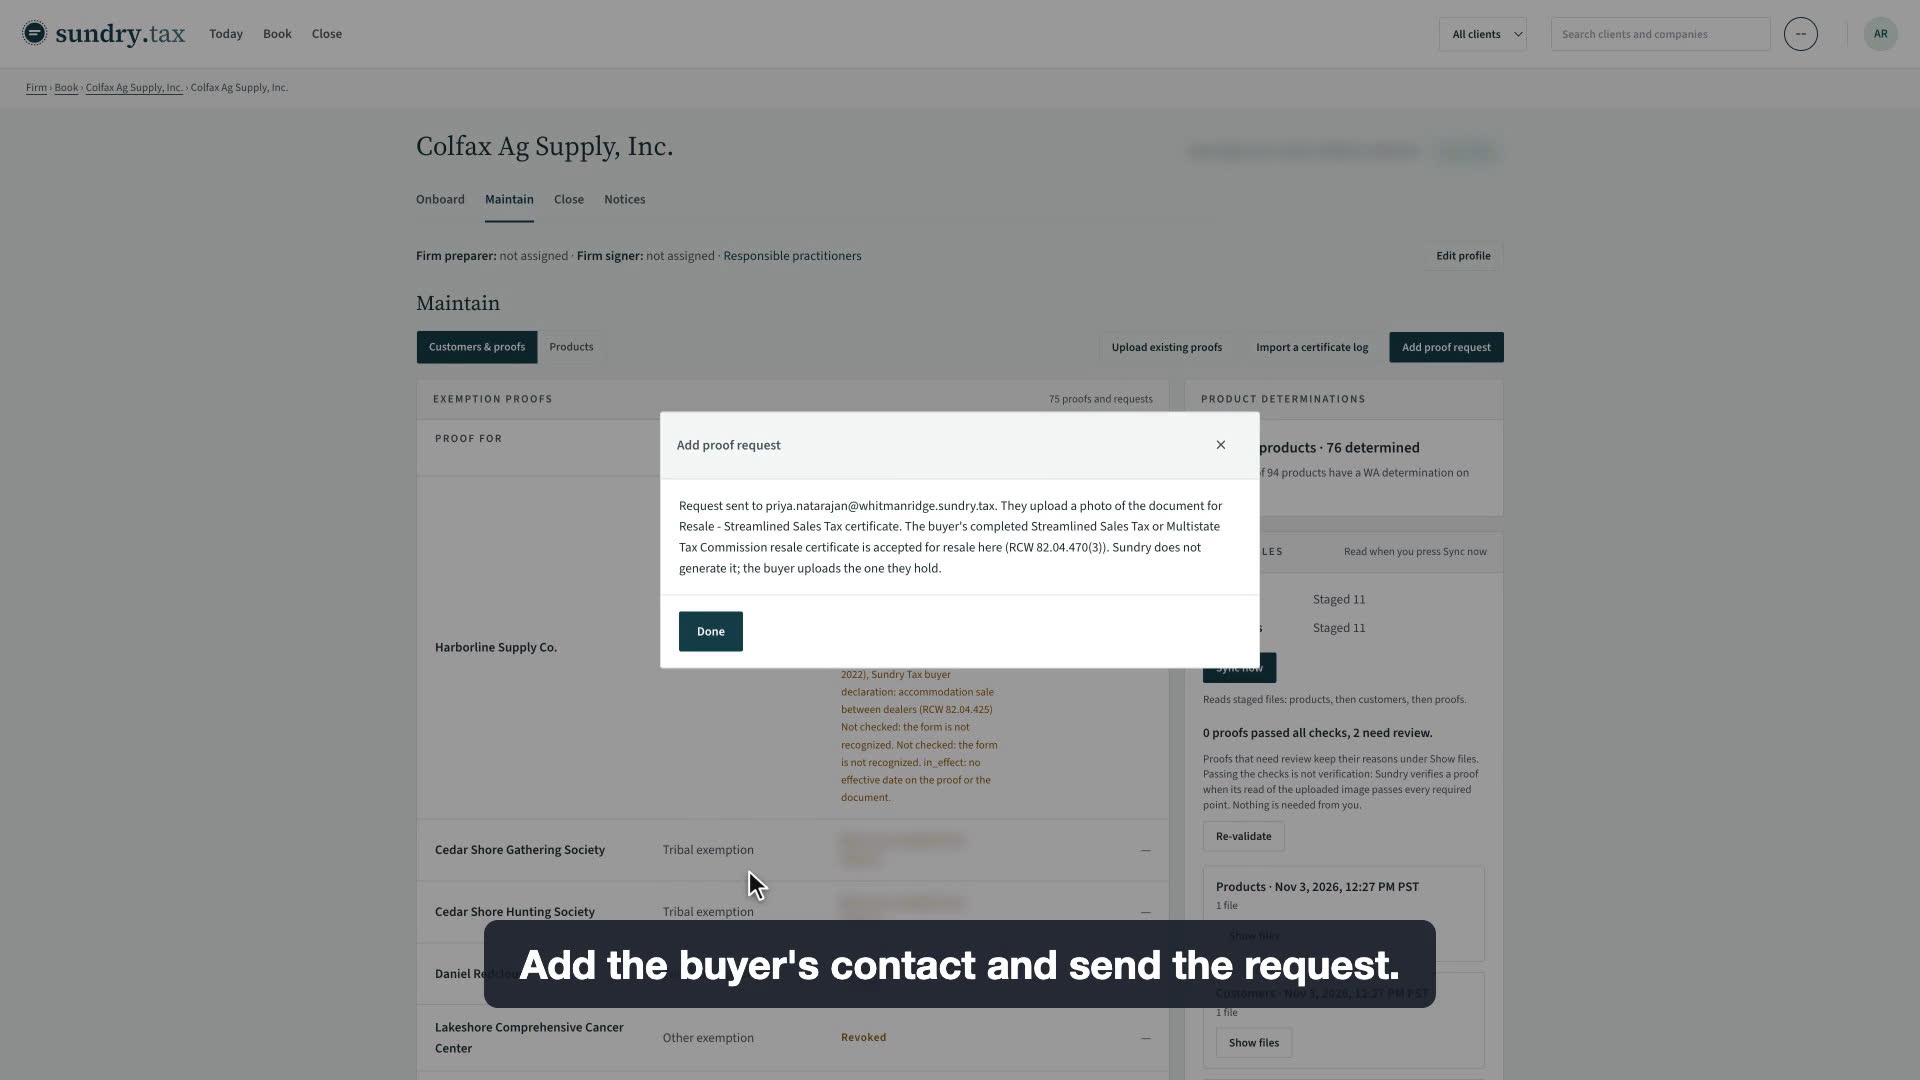
A firm asks the buyer for a completed Streamlined Sales and Use Tax Certificate of Exemption, the buyer uploads it from the emailed link, and Sundry reads it.
A seller can document a wholesale sale with the Streamlined Sales and Use Tax Agreement Certificate of Exemption instead of a copy of the buyer's reseller permit. WAC 458-20-102(7) lets a seller accept it from a buyer that is required to be registered with the Department of Revenue, with the buyer's reseller permit number on it, and from a buyer that is not required to be registered.
Who qualifies
- A buyer that is required to be registered with the department under RCW 82.32.030. WAC 458-20-102(7)(a)(i) lets the seller accept the certificate in lieu of a permit copy, and (7)(b) says it must include the reseller permit number the department issued to the buyer.
- A buyer that is not required to be registered with the department. WAC 458-20-102(7)(d)(ii) lets the seller accept the same certificate in lieu of a permit copy.
- In both cases the purchase must be a wholesale purchase. WAC 458-20-102(6): "The buyer may use a reseller permit only when making wholesale purchases."
What qualifies
- Purchases for resale. WAC 458-20-102(5) treats every sale as a retail sale unless the seller takes a reseller permit, a Streamlined Sales and Use Tax Agreement Certificate of Exemption or other certificate authorized by RCW 82.04.470, or the data elements described in subsection (7).
Not covered
- Tax-exempt retail purchases. WAC 458-20-102(6): "The reseller permit may not be used when making tax-exempt retail purchases." Those need the exemption's own certificate.
- A certificate that is not properly completed. The rule accepts "a properly completed" certificate.
What the buyer gives
A properly completed Streamlined Sales and Use Tax Agreement Certificate of Exemption (SSTGB form F0003, Washington-revised 5/25/2022). A buyer that is required to be registered with the department must put its reseller permit number on it (WAC 458-20-102(7)(b)). In Sundry the buyer uploads the completed certificate and Sundry reads it.
What the seller keeps
The completed certificate. WAC 458-20-102(7): the seller has the burden of proving the sale was at wholesale, and may meet it by taking the document at the time of sale or within one hundred twenty days after the sale. A seller that accepts the certificate is not required to verify with the department whether the buyer is required to be registered (WAC 458-20-102(7)(c) and (7)(e)). If a buyer that is not required to be registered gives the certificate more than one hundred twenty days after the sale and it does not name the sales, the buyer must identify the sales it covers in other documentation the buyer signs (WAC 458-20-102(7)(l)). If the seller has none of these documents, the seller is liable for the tax unless it proves by facts and circumstances that the sale was made at wholesale (WAC 458-20-102(7)(h)).
Common mistakes
- Accepting a certificate from a Washington-registered buyer with no reseller permit number on it. WAC 458-20-102(7)(b) requires the number.
- Accepting a certificate for something the buyer will use rather than resell. WAC 458-20-102(7)(h) asks whether the items are consistent with the buyer's business and of a type it would normally buy at wholesale.
- Checking the resale box for a purchase that is not for resale. Under WAC 458-20-102(6) the reseller permit may be used only for wholesale purchases; the form's other exemptions follow their own rules (RCW 82.08.050).
Common questions
- Does a seller have to check whether the buyer is required to be registered in Washington?
- No. WAC 458-20-102(7)(c) and (7)(e) say a seller that accepts the certificate is not required to verify with the department whether the buyer is required to be registered.
- How long does a seller have to collect the certificate?
- At the time of sale or within one hundred twenty days after it (WAC 458-20-102(7)). If a single order is billed in stages, the one hundred twenty days run from the first billing (WAC 458-20-102(7)(k)).
- Where does a buyer get the certificate?
- WAC 458-20-102(7)(d) says the Streamlined Sales and Use Tax Agreement Certificate of Exemption may be obtained on the department's website at dor.wa.gov.
Sources
- WAC 458-20-102 (5), (6), (7)(a)-(e), (7)(h), (7)(k), (7)(l)
- RCW 82.04.470 (2)(a)(i), (2)(b), (2)(c), (3)(a)(ii)
- Form
- SSTGB F0003: Streamlined Sales and Use Tax Certificate of Exemption (SSTGB Form F0003, WA-revised 5/25/2022)
- Statute
- RCW 82.04.470(2)(a)(i), (3)(a)(ii); WAC 458-20-102(7)(a), (7)(d)(ii)
- Category
- Resale permit
- How the buyer provides it
- Uploads a photo of the Department-issued certificate