REV 27-0032
Computer equipment bought by printers and publishers
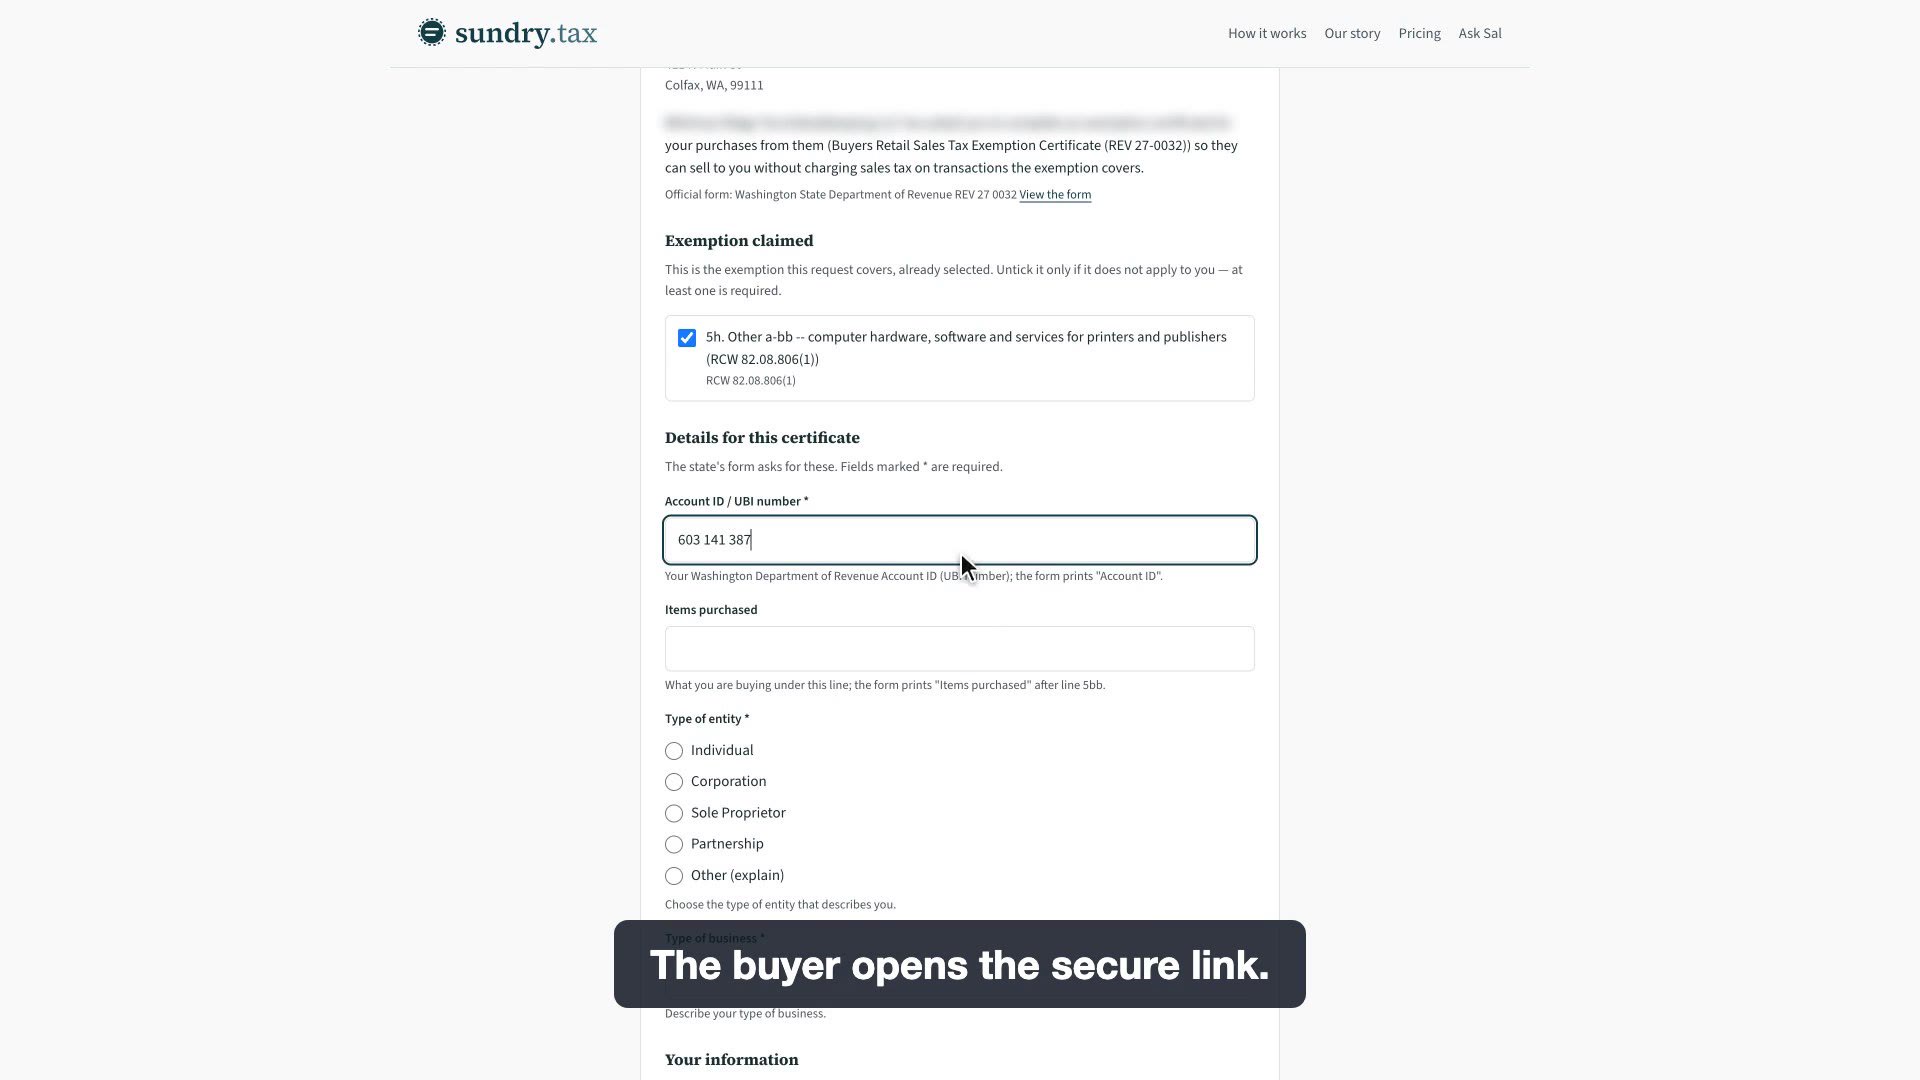
A firm asks the printer or publisher for a signed REV 27-0032, the buyer fills in and signs it from the emailed link, and Sundry shows it signed and Verified by Sundry.
Commercial printers and publishers pay no Washington sales or use tax on computers, peripherals, digital cameras and software used more than half the time in printing or publishing printed material, or on installing and repairing that equipment. It fills the gap left by the manufacturing machinery exemption: equipment that already qualifies as manufacturing machinery uses that certificate instead, and front-office computers stay taxable.
Who qualifies
- A "printer or publisher": a person subject to B&O tax under RCW 82.04.280(1)(a), which covers printing materials other than newspapers and publishing periodicals or magazines.
- A person eligible for the newspaper exemption in RCW 82.04.759 (printing or publishing a newspaper, and certain publishers of eligible digital content).
- From January 1, 2034 the definition changes to a person subject to tax under RCW 82.04.260(14) or 82.04.280(1)(a); see the pending version noted in the sources.
- The buyer must keep the records the department needs to check eligibility.
What qualifies
- "Computer equipment": a computer and the components of the computer system, including monitors, keyboards, printers, modems, scanners, pointing devices and other peripherals, cables, servers and routers.
- Digital cameras and computer software.
- Repair parts and replacement parts for the equipment.
- Labor and services to install, repair, clean, alter or improve the equipment.
- Only equipment used "primarily," meaning more than 50 percent as measured by time, in printing or publishing printed material.
Not covered
- Equipment used primarily for administrative purposes, including payroll processing, accounting, customer service, telemarketing and collection.
- Equipment that already qualifies for the manufacturing machinery and equipment exemption under RCW 82.08.02565. This exemption applies only to equipment not otherwise exempt there.
- Equipment used 50 percent of the time or less in printing or publishing printed material.
- Purchases by a business that is not a printer or publisher as defined, even if it prints or designs material for its own use.
What the buyer gives
Form REV 27 0032 (revision 6/17/25), line 5h: "Computer hardware, peripherals, software and related installation, purchased by publishers and printers." The form instructions say 5h covers hardware, peripherals, digital cameras, software and related installation "not otherwise eligible for the M&E exemption that is used primarily in the printing or publishing of printed materials," including repairs and replacement parts. The buyer ticks single use or blanket, enters the seller's name and address and the date, checks 5h, lists the items, and completes the certification block (type of entity, type of business, Account ID, name, title, address, signature). RCW 82.08.806(2): the exemption "is available only when the purchaser provides the seller with an exemption certificate in a form and manner prescribed by the department."
What the seller keeps
RCW 82.08.806(2): "The seller must retain a copy of the certificate for the seller's files." Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Putting accounting, billing or customer service computers on the certificate. The statute excludes equipment used primarily for administrative purposes.
- Missing the simultaneous use rule. When a machine is used for administrative and production work at the same time, the administrative use is disregarded for that period in deciding whether it is used primarily for administrative purposes.
- Using line 5h for equipment that qualifies as manufacturing machinery. Printers of newspapers or other materials count as manufacturers under RCW 82.08.02565(2)(d); equipment that qualifies there is not covered by this exemption and goes on form REV 27 0021.
- Keeping no time records. "Primarily" is measured by time, and the buyer must keep the records needed to show eligibility.
Common questions
- Can a magazine publisher buy design workstations and software without sales tax?
- Yes, if the publisher is taxed under RCW 82.04.280(1)(a) and the workstations are used more than half the time in printing or publishing printed material, not mainly for administrative work, and they do not already qualify for the manufacturing machinery exemption.
- Is a repair call on a prepress server exempt?
- Yes, for qualifying equipment. The exemption covers repair and replacement parts and labor to install, repair, clean, alter or improve the computer equipment.
- Are digital cameras included?
- Yes. RCW 82.08.806(3)(b) says computer equipment "also includes digital cameras and computer software."
- Does use tax apply if we buy from an out-of-state seller?
- Not on qualifying equipment. RCW 82.12.806 gives a matching use tax exemption on the same terms.
Sources
- RCW 82.08.806 (1)-(4); version effective until and version effective January 1, 2034; findings note, 2004 c 8 s 1
- RCW 82.12.806 Matching use tax exemption
- RCW 82.04.280 (1)(a) printing materials other than newspapers, publishing periodicals or magazines
- RCW 82.04.759 (1) newspaper and eligible digital content B&O exemption
- RCW 82.08.02565 (2)(d) printers as manufacturers (fetched for the pilot)
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 3 line 5h; page 4 certification; page 6 line 5h instructions
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.806(1)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal