REV 27-0036
Poultry used to produce poultry or poultry products for sale
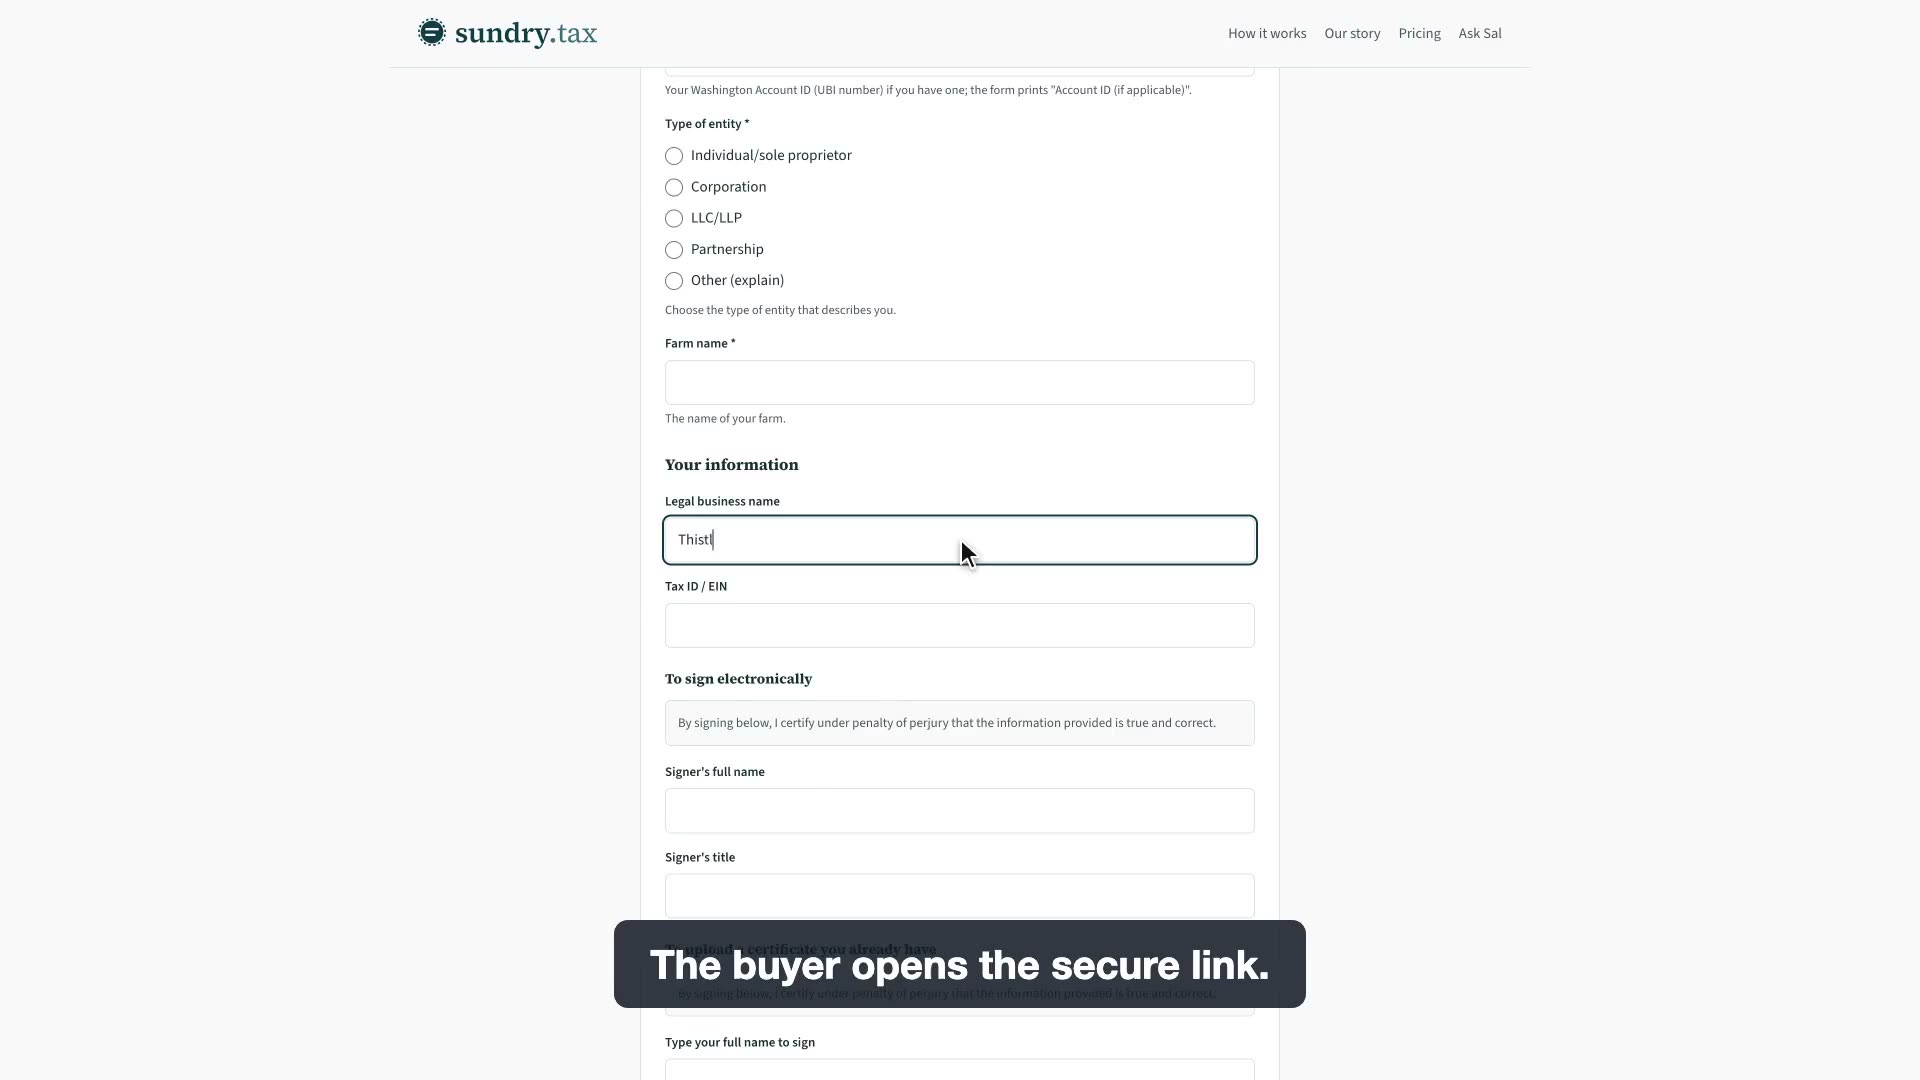
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Poultry sold for use in producing poultry or poultry products for sale is exempt from Washington sales and use tax: chicks sold to an egg farm, breeder stock sold to a hatchery, birds sold to a grower who raises them for market. A hatchery selling to farmers is the typical seller. Birds bought as pets or for a family's own eggs and meat are taxable.
Who qualifies
- A buyer that will use the poultry in producing poultry or poultry products for sale. The statute is written around the use, not the type of buyer; the department's certificate for it is the farmer's certificate.
- WAC 458-20-210, Example 8: a hatchery produces poultry from eggs and sells it to egg producers; those sales are exempt.
What qualifies
- Sales of poultry for use in the production for sale of poultry.
- Sales of poultry for use in the production for sale of poultry products, such as eggs.
Not covered
- Poultry bought to produce eggs or meat for the buyer's own consumption; the production must be for sale.
- Pet birds. Pet animals are not agricultural products.
- Feed, bedding, heating fuel and equipment for the flock. Those have their own rules: feed is a wholesale purchase (Section A), and bedding and heating fuel for chickens have separate lines (4a and 4b).
What the buyer gives
Form REV 27 0036 (revision 7/13/23), Section B line 4c: "Poultry used in the production or sale of poultry products." The instructions describe it as "the purchase of poultry for the use in the production for sale of poultry or poultry products." The signature block asks for Account ID (if applicable), type of entity, name of buyer, farm name, mailing address, authorized signature, date, title and phone number. By signing, the buyer states it qualifies, that it "must keep records to verify the exempt nature of the sale," and that misuse "will result in taxes due, applicable interest, and possible penalties." The form has no field for the seller's name. The buyer ticks single use or blanket; a blanket certificate stays valid while there is at least one sale within 12 months. Cannabis growers and producers cannot use the form.
What the seller keeps
WAC 458-20-210(10): sellers "must retain a copy of the exemption certificate or the data elements in their files." On the B&O side, farmers producing hatching eggs or poultry are exempt from B&O tax on sales of hatching eggs or poultry for use in the production for sale of poultry or poultry products (WAC 458-20-210(8)(d)(iii), citing RCW 82.04.410). Form REV 27 0036 says the seller "must retain the original of this certificate for their records" and must not send a copy to the Department, and: "A seller who accepts this completed certificate is relieved of the responsibility to collect retail sales or use tax unless the seller fraudulently fails to collect the tax or solicits the purchaser to participate in unlawfully claiming the exemption." The certificate does not expire while buyer and seller have at least one sale within twelve consecutive months; after a longer gap the seller must obtain a new form. WAC 458-20-210(10): "Without proper documentation, sellers are liable for payment of the retail sales tax on sales claimed as exempt." RCW 82.32.070(1) requires records to be kept for five years, and RCW 82.08.050(7)(a)-(b) gives the 90-day and 120-day windows for obtaining a fully completed certificate.
Common mistakes
- Selling chicks tax-free to a backyard keeper. The poultry must be used in production for sale.
- Reading the form's shorthand as broader than the law. Line 4c says "production or sale"; the statute and the form's own instructions say "production for sale."
- Assuming the chicken-only lines apply to all poultry. Lines 4a and 4b are limited to chickens; line 4c covers poultry used in production for sale.
Common questions
- Does a hatchery charge sales tax on pullets sold to an egg farm in Washington?
- No. Sales of poultry for use in producing poultry products for sale are exempt; WAC 458-20-210 Example 8 describes a hatchery selling to egg producers. The hatchery keeps the farm's completed REV 27 0036 with line 4c checked.
- Is there use tax on poultry bought from an out-of-state hatchery?
- Not when the poultry is used in production for sale. RCW 82.12.0262 exempts the use of poultry in the production for sale of poultry or poultry products.
- Does the hatchery owe B&O tax on these sales?
- A farmer producing hatching eggs or poultry is exempt from B&O tax on those sales when the agricultural products are for use in the production for sale of poultry or poultry products.
Sources
- RCW 82.08.0267 Sales tax exemption
- RCW 82.12.0262 Matching use tax exemption
- RCW 82.04.213 (1) agricultural product; (3) farmer
- WAC 458-20-210 (3) agricultural product; (8)(d)(iii) B&O on hatching eggs and poultry; (9)(f) poultry and Example 8; (10)
- DOR form REV 27 0036 (7/13/23), Farmer's Certificate for Wholesale Purchases and Sales Tax Exemptions Page 1 line 4c; page 2 signature and seller text; page 4 line 4c instructions
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0036: Farmer's Certificate for Wholesale Purchases and Sales Tax Exemptions
- Statute
- RCW 82.08.0267
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal