REV 27-0002
Vehicle, trailer or camper bought by a nonresident and licensed in the buyer's home state
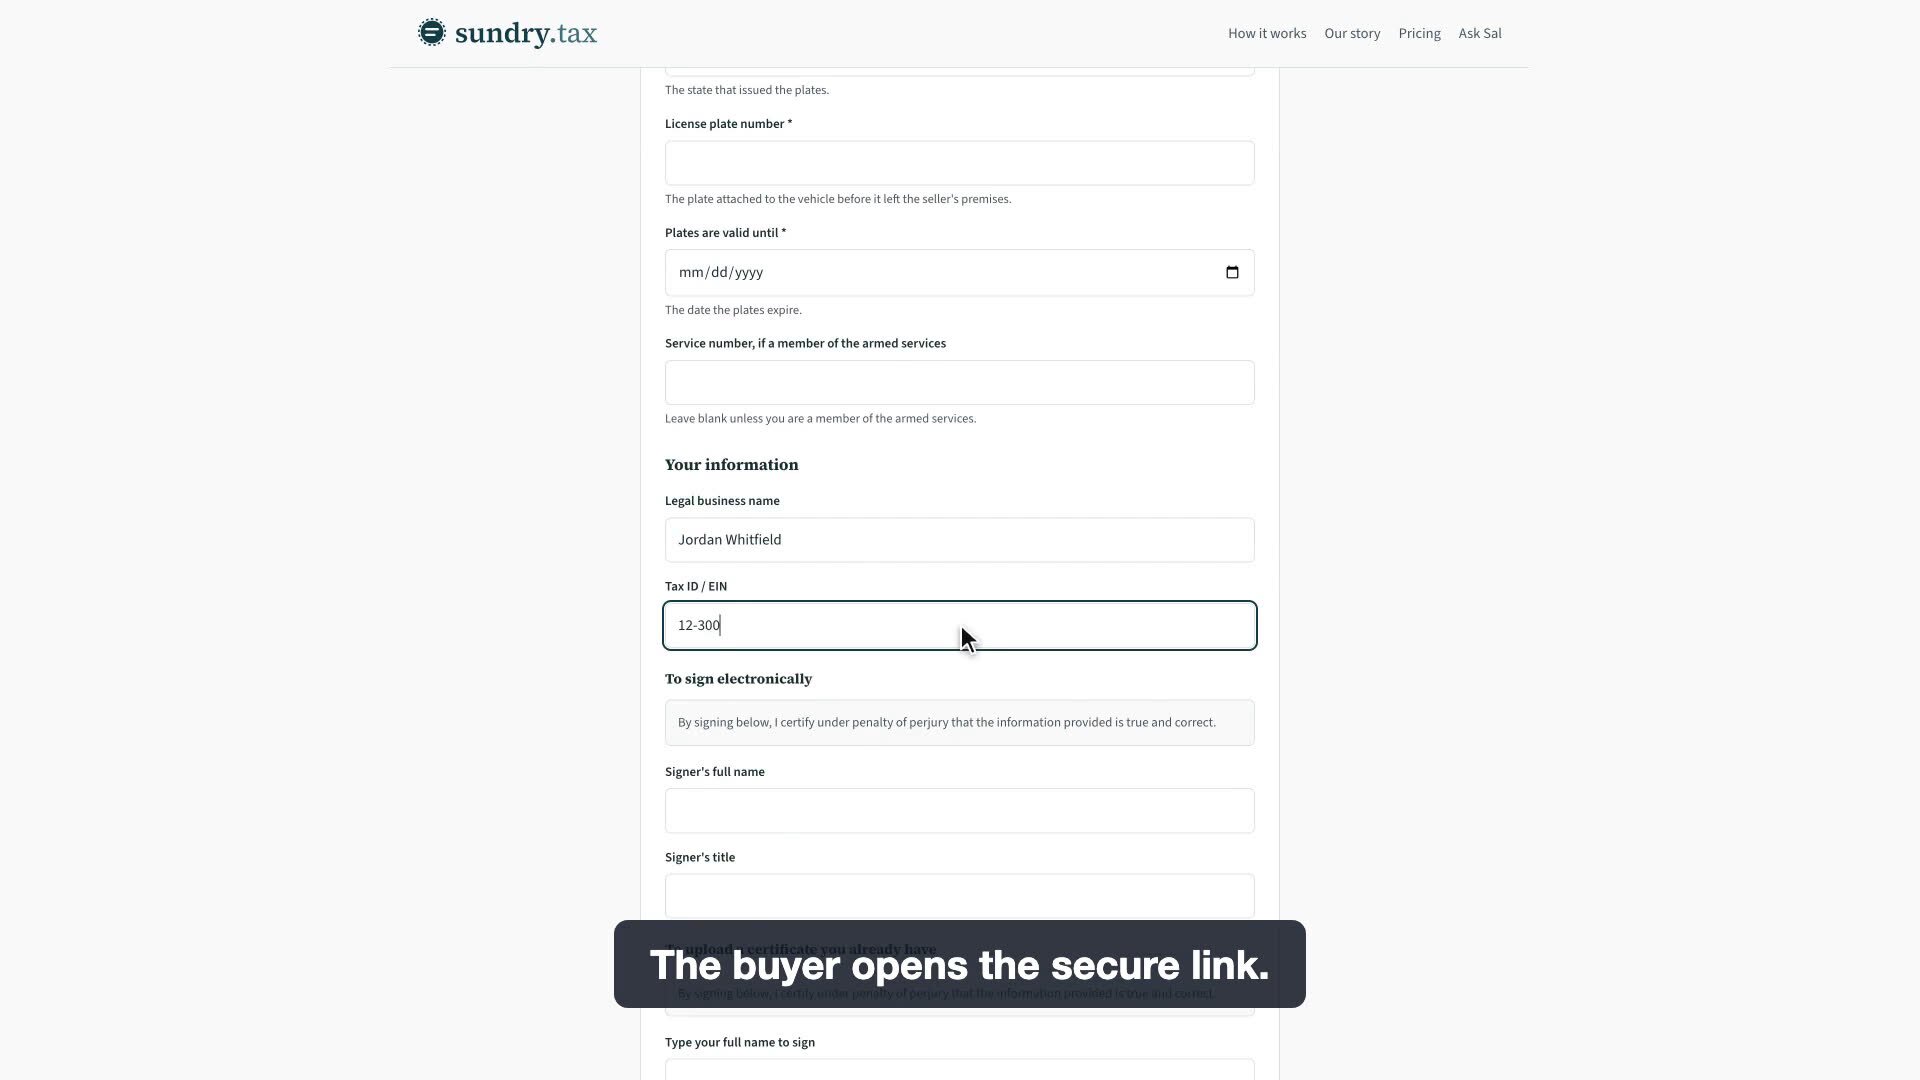
A firm asks the buyer for a signed REV 27-0002, the buyer signs it from the emailed link, the dealer witnesses the buyer's signature and completes the seller's REV 27-0003, and Sundry shows it signed and Verified by Sundry.
A nonresident who takes delivery of a motor vehicle, trailer or camper in Washington pays no Washington sales tax if the vehicle is registered and licensed right away in the buyer's home state, will not be used in Washington more than three months, and is not required to be registered here. The dealer keeps the buyer's affidavit (REV 27 0002), its own seller's certificate (REV 27 0003) and copies of the buyer's ID and proof of an out-of-state address.
Who qualifies
- A buyer who is not a resident of Washington and buys the vehicle for use outside Washington.
- A nonresident corporation, if the corporation is the purchaser: paid for by corporate check and registered in its name. The exemption still applies when a Washington-resident officer or employee buys on its behalf. A corporation with places of business in other states may count as a nonresident.
- A member of the armed services temporarily stationed in Washington is presumed to be a nonresident, unless the member was a Washington resident when enlisted or inducted. The presumption does not cover civilian employees of the armed services. Members of the armed forces of a NATO-member nation stationed in Washington are nonresidents for this exemption.
- Cosigners and others who back the purchase financially are not the "buyer" unless they are listed as a registered owner on the title.
What qualifies
- Any vehicle of a type that may be licensed under chapter 46.16A RCW for use on a public highway: cars, trucks, campers, trailers, buses, motorhomes, and motorcycles equipped for road use.
- Delivered to the buyer in Washington, where the vehicle will be registered and licensed immediately under the laws of the buyer's state of residence, will not be used in Washington more than three months, and will not be required to be registered and licensed in Washington.
- The buyer's affidavit states that the home-state plates were attached to the vehicle before it left the seller's premises.
Not covered
- Farm tractors, bicycles, mopeds, motorized scooters, snowmobiles and vehicles made only for off-road use. These are not "vehicles" under the rule.
- A vehicle the buyer will use in Washington for more than three months, even with home-state plates. The rule's example: a California buyer with California plates who will drive the car here for four months does not qualify.
- Any sale where the seller licenses or registers the vehicle in Washington on the buyer's behalf. Sales tax applies.
- A buyer with dual residency, for example one who lives part of each year in Washington and part in Arizona, even with an Arizona license.
- A military buyer who registers in the home state but keeps the vehicle in Washington more than three months.
- The separate nonresident remittance in RCW 82.08.0273 does not apply to vehicles.
- The retailing B&O tax. No B&O deduction is allowed when a nonresident takes delivery in Washington, even when the sale is exempt from sales tax.
What the buyer gives
The Buyer's Affidavit for In-State Delivery of Motor Vehicles, form REV 27 0002 (5/25/21). The buyer gives name, resident state and home address; the purchase date, seller name, make, model, year and VIN; ticks the second option ("The vehicle will not be used in Washington state for more than three months and has been licensed in another state. The plates have been attached to the vehicle before it left the seller's premises.") and enters the state, the license plate number and the date the plates are valid until; adds a service number if a member of the armed services; and signs and dates in front of a witness, who also prints a name, signs and dates. With it the buyer hands over a copy of a currently valid out-of-state driver's license or other official picture ID issued outside Washington, and a copy of one document showing an out-of-state address: a current residential rental agreement, a property tax statement from the current or previous year, a utility bill dated within two months, last year's state income tax return, a voter registration card, a current credit report, or another document the rule accepts (for example a bank statement, government check or pay check within two months, mortgage documents, or a current vehicle insurance card). A military buyer also gives a copy of orders showing temporary station in Washington, or reassignment outside Washington, and departure within three months of the purchase.
What the seller keeps
The seller completes the Seller's Certificate for In-State Delivery of Motor Vehicles, form REV 27 0003 (5/25/21): it certifies that the Washington plates were removed before final delivery, ticks "License plates were issued and affixed to the vehicle" with the plate number, issuing state and expiry, enters the buyer's resident state, ticks at least one address document from column A and the driver's license or picture ID number in column B, and signs with title and date. RCW 82.08.0264(2): the seller "is not required to collect and shall not be found liable for the tax" if it retains the ID copy, the address document, the witnessed declaration and the seller's certification, "which must be made available upon request of the department." Under (5)(a), a seller that sells without those documents, or does not keep them for the period in RCW 82.32.070 (five years), "is personally liable for the amount of tax due." WAC 458-20-177(5): do not send the documents to the department; keep them five years; without them the exemption claim is disallowed. Documents in substantially the same form as DOR's are accepted. If the vehicle had Washington plates, keep evidence that they were removed. If the department later finds the buyer was not eligible, it collects the tax from the buyer; the seller is not liable unless it lacked the documents or knew they were fraudulent. RCW 82.04.470 governs reseller permits and wholesale sales; it is not the documentation rule for this sale.
Common mistakes
- Accepting home-state plates from a buyer who says the vehicle will stay in Washington longer than three months.
- Registering the vehicle in Washington for the buyer. That makes the sale taxable.
- Skipping the reasonable-care check. The rule says lack of good faith is indicated when the seller knows the buyer lives in Washington, the buyer gives a Washington address for financing, or service is set up under a Washington address or phone number.
- Taking documents with different addresses without question. If the addresses don't match, the department may contact the buyer.
- Using the out-of-state delivery forms (REV 27 0004 and 27 0005). Those are for vehicles the seller delivers outside Washington; in-state delivery needs the affidavit and the in-state seller certificate.
- Taking a B&O deduction. In-state delivery to a nonresident is still subject to retailing B&O tax.
Common questions
- Does an Oregon buyer who registers the car in Oregon pay Washington sales tax?
- Not if the car is licensed in Oregon right away, the plates are on before it leaves the lot, it will not be used in Washington more than three months, and the dealer keeps the affidavit, its seller certificate, a copy of the buyer's ID and one proof of an Oregon address.
- Is a service member stationed in Washington a nonresident for this exemption?
- Presumed so, unless the member was a Washington resident on enlisting. The dealer must also keep a copy of orders showing the member leaves Washington within three months of the purchase. If the vehicle will stay here more than three months, sales tax is due. A member may instead qualify under RCW 46.16A.340 with a 45-day nonresident military temporary permit from the Department of Licensing.
- What happens if the buyer gave false information?
- A buyer who makes fraudulent statements to buy without sales tax is guilty of perjury, and one who uses someone else's or counterfeit ID owes the tax plus a penalty. A seller is liable only if it did not keep the required documents or knew they were fraudulent.
- Can the dealer sign the witness line?
- The statute requires a witnessed declaration and DOR's affidavit has witness name, signature and date lines. Neither RCW 82.08.0264 nor WAC 458-20-177 says who may be the witness. In Sundry the dealer's signer witnesses the buyer's signature, after the buyer signs.
Sources
- RCW 82.08.0264 (1)(b), (2)(a)-(d), (3), (4), (5)(a)-(b), (6)
- WAC 458-20-177 (2), (3)(a)-(d), (5), (6), (7), (9), (10)(a), (10)(f)-(g), (11)
- DOR form REV 27 0002 (5/25/21), Buyer's Affidavit for In-State Delivery Sections 1-3
- DOR form REV 27 0003 (5/25/21), Seller's Certificate for In-State Delivery Page 1
- DOR Forms by subject: Vehicle sales Form list (27 0002, 27 0003, 27 0004, 27 0005)
- RCW 82.32.070 (1) five-year record retention
- RCW 82.04.470 (1), (7) reseller permits and wholesale sales
- Form
- REV 27-0002: Nonresident Motor Vehicle/Trailer/Camper In-State Delivery Certificates
- Statute
- RCW 82.08.0264(1)(b)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal