REV 27-0055
Medicines prescribed or administered by a licensed naturopath
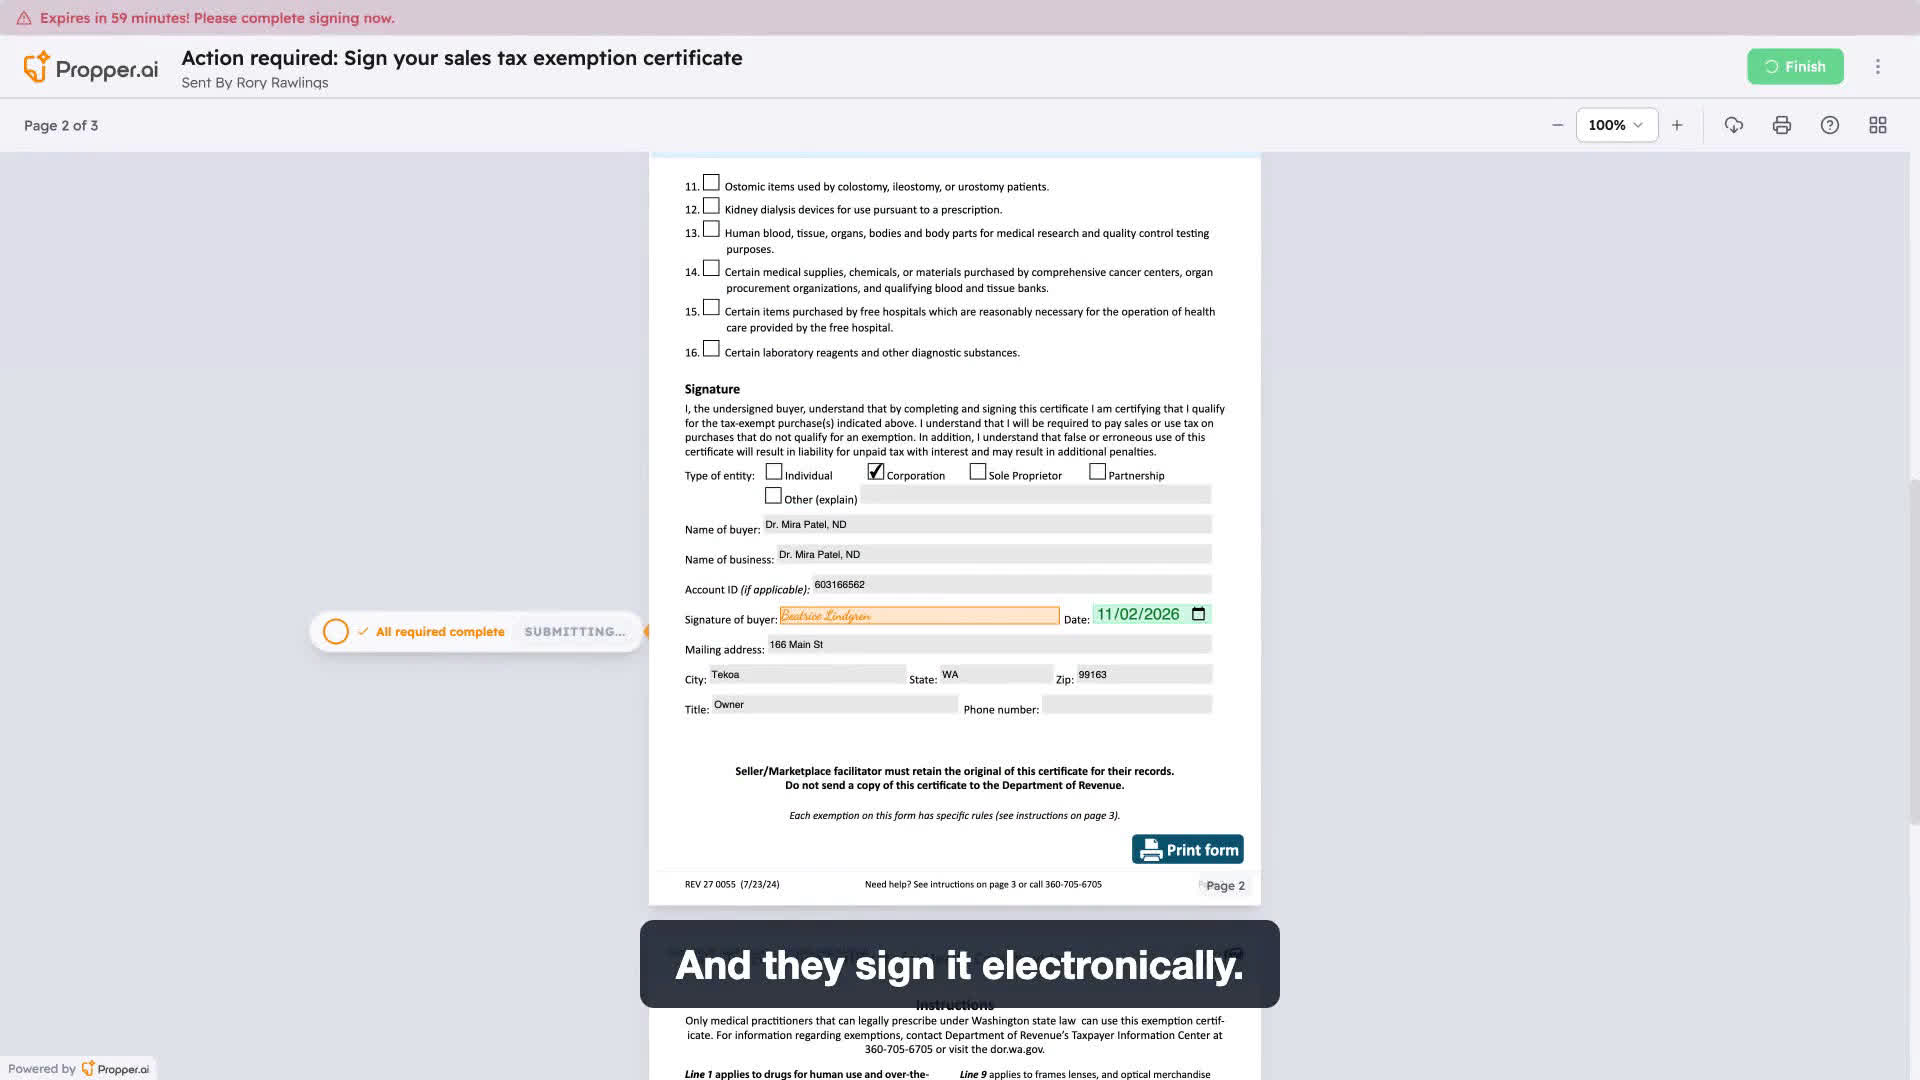
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Medicines of mineral, animal and botanical origin are exempt from Washington sales and use tax when a licensed naturopath prescribes, administers, dispenses or uses them in treating an individual. The exemption follows the naturopath's license and the treatment of a patient, not the product alone.
Who qualifies
- A person licensed under chapter 18.36A RCW (naturopathy).
- The form is limited to practitioners who can legally prescribe; it names chiropractors, East Asian medicine practitioners and massage practitioners as unable to use it.
What qualifies
- Medicines of mineral, animal and botanical origin prescribed, administered, dispensed or used in the treatment of an individual by a licensed naturopath (RCW 82.08.0283(1)(b)).
- WAC: naturopathic medicines are vitamins, minerals, botanical medicines, homeopathic medicines, hormones, and legend drugs and controlled substances consistent with naturopathic practice under Department of Health rules. Controlled substances are limited to codeine and testosterone products in Schedules III, IV and V.
- The matching use tax exemption is RCW 82.12.0277(1)(b).
Not covered
- The same products bought by someone not licensed under chapter 18.36A RCW.
- Products not used in treating an individual, such as clinic or office supplies and equipment.
- Durable medical equipment and mobility enhancing equipment (RCW 82.08.0283(3)).
What the buyer gives
Form REV 27 0055, Sales Tax Exemption Certificate for Health Care Providers (revision 7/23/24), line 4, "Medicines of mineral, animal and botanical origin prescribed, administered, dispensed, or used in the treatment of an individual by a licensed Naturopath." The buyer ticks single use or blanket (valid while buyer and seller have at least one sale within 12 months), names the seller and the date, ticks the line for the exemption, and completes the signature block: type of entity, name of buyer, name of business, Account ID if any, signature, date, mailing address, title and phone. Only practitioners who can legally prescribe under Washington law may use the form; the form names chiropractors, East Asian medicine practitioners and massage practitioners as unable to use it.
What the seller keeps
Form REV 27 0055 says the seller or marketplace facilitator "must retain the original of this certificate for their records" and not send a copy to the Department of Revenue. WAC 458-20-18801(304): sellers to medical practitioners, nursing homes and hospitals must obtain an approved exemption form, capture the streamlined sales tax data elements, or otherwise meet RCW 82.08.050(7) for any exempt sale. Line 4 is for licensed naturopaths; a buyer outside that license should not be using it. RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when the department asks; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Using line 4 for dietary supplements dispensed under a prescription by other practitioners. Those use line 3 (RCW 82.08.925).
- A practitioner without a chapter 18.36A RCW license using line 4.
- Buying general clinic supplies on the certificate.
Common questions
- Do naturopaths pay sales tax on herbs and supplements in Washington?
- Not on medicines of mineral, animal or botanical origin they prescribe, administer, dispense or use in treating a patient, if they are licensed under chapter 18.36A RCW. They give the seller form REV 27 0055 with line 4 ticked.
- Are homeopathic medicines included?
- Yes. The WAC lists homeopathic medicines among naturopathic medicines.
Sources
- RCW 82.08.0283 (1)(b), (3)
- RCW 82.12.0277 (1)(b)
- WAC 458-20-18801 (304); (403)(e)-(f)
- DOR form REV 27 0055 (7/23/24), Sales Tax Exemption Certificate for Health Care Providers Header; lines 3-4; page 3 instructions, lines 3-4
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0055: Sales Tax Exemption Certificate for Health Care Providers
- Statute
- RCW 82.08.0283
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal