REV 27-0032
Motion picture and video production: equipment rental and production services
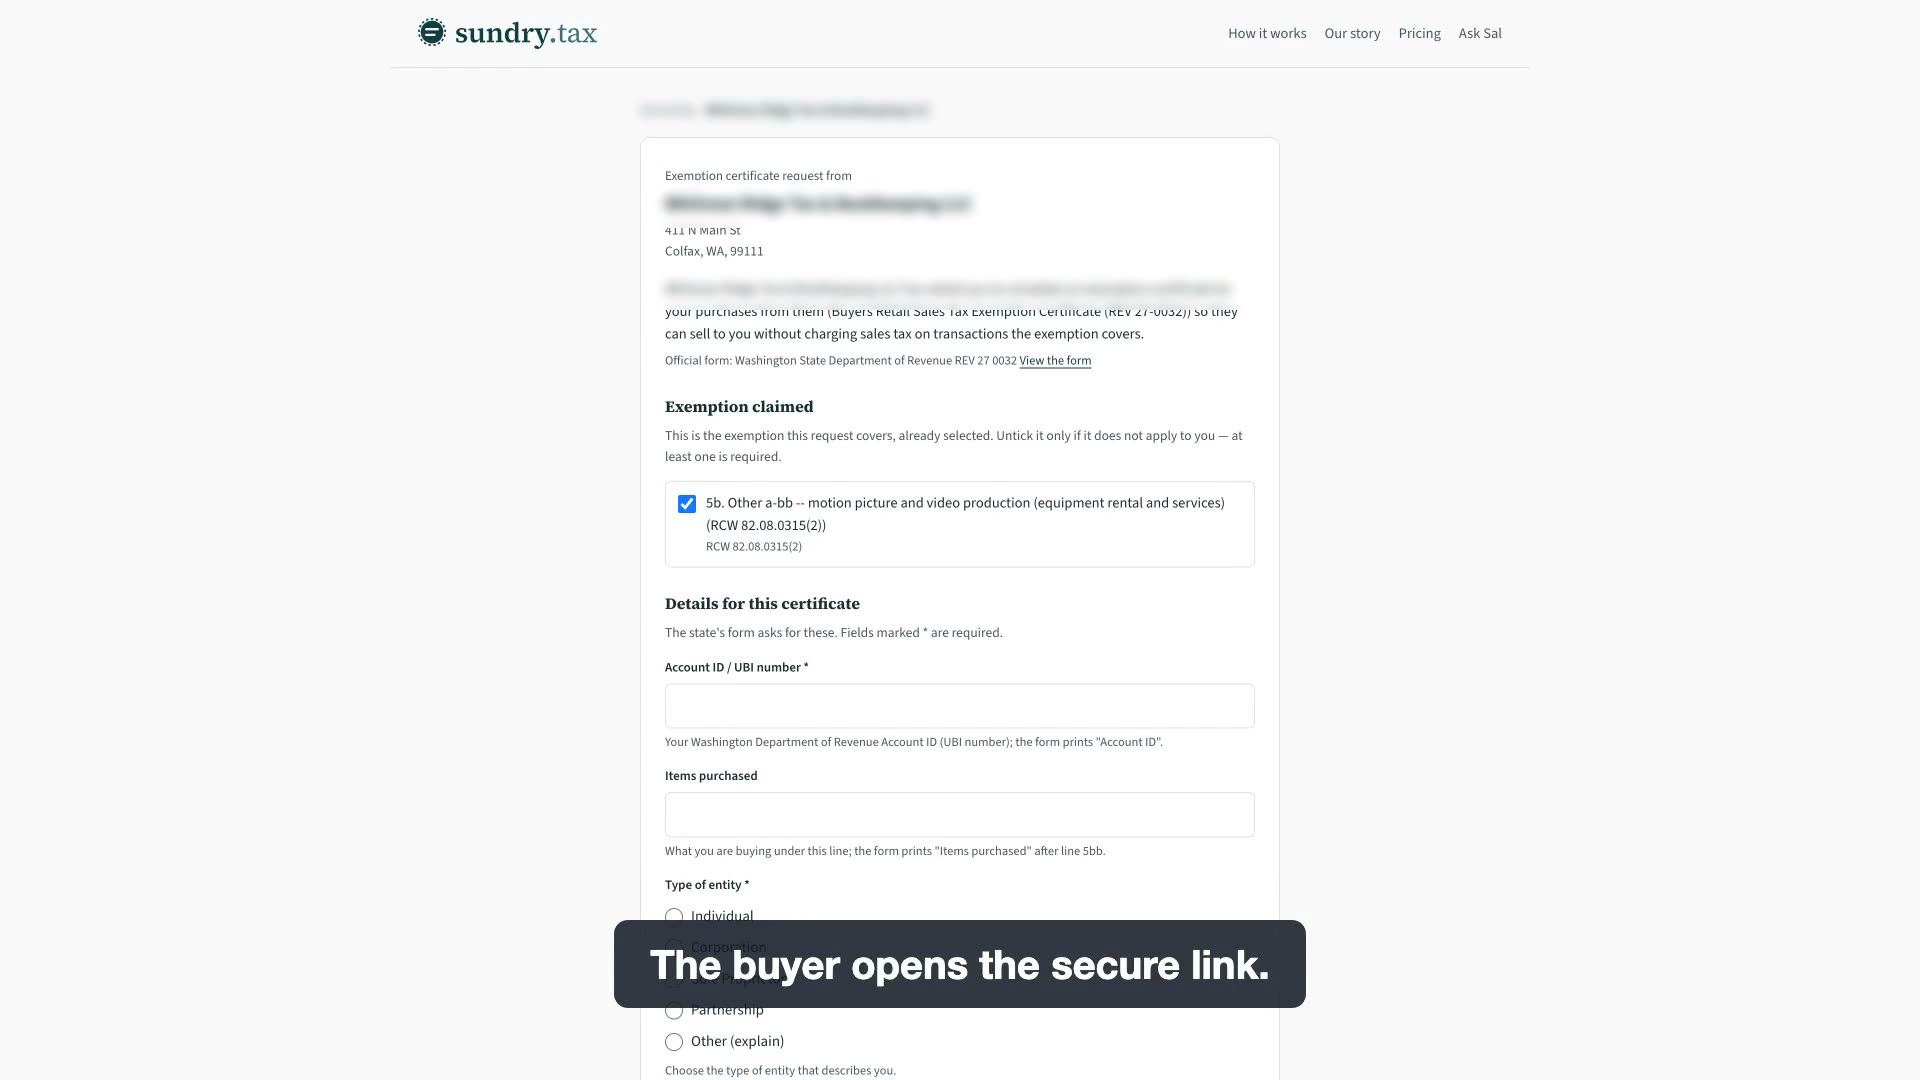
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Motion picture and video production businesses pay no Washington sales tax when they rent production equipment or buy production services such as editing, effects and sound mixing. Buying equipment outright is not covered, and a business involved to any degree in erotic material does not qualify.
Who qualifies
- A "motion picture or video production business": a person producing motion pictures and videotapes for exhibition, sale or broadcast by someone other than the producer.
- Not a business engaged, to any degree, in producing erotic material as defined in RCW 9.68.050.
What qualifies
- Rental of production equipment used in production or postproduction: grip and lighting equipment, cameras, camera mounts (tripods, jib arms, steadicams), cranes, dollies, generators, helicopter mounts, helicopters rented for production, walkie-talkies, vans, trucks and other vehicles specially equipped for production or used solely for production, wardrobe and makeup trailers, special effects and stunt equipment, video assists, videotape recorders, cables and connectors, teleprompters, sound recording equipment and editorial equipment.
- Production services: motion picture and video processing, printing, editing, duplicating, animation, graphics, special effects, negative cutting, format conversions, stock footage, sound mixing, rerecording, sound sweetening, sound looping, sound effects and automatic dialog replacement.
- Form REV 27 0023: the exemption covers state and local sales tax, and for vehicles used in production it also covers the additional sales tax on rental cars.
- Use tax: also exempt for production equipment the business acquired and used in another state more than 90 days before it entered Washington.
Not covered
- Purchases of production equipment. DOR: "The exemption does not extend to the purchase of production equipment."
- Any rental or service sold to a business engaged to any degree in producing erotic material.
- Productions made for the producer's own exhibition, sale or broadcast. The definition requires exhibition, sale or broadcast by a person other than the producer.
- Equipment and services not on the statutory lists. The statute defines both terms by list ("means the following").
What the buyer gives
Either DOR form. The dedicated Motion Picture and Video Production Business Exemption Certificate, form REV 27 0023 (5/25/21), asks for the vendor/seller's name, the renter/buyer's name, address, phone, Account ID/UBI and email, a list of production equipment rented and production services purchased, and the name, signature and date of the person authorized by the buyer. By signing, the buyer certifies it is a motion picture or video production business not engaged, to any extent, in producing erotic material. DOR also accepts the Buyer's Retail Sales Tax Exemption Certificate, form REV 27 0032 (6/17/25), line 5b ("Equipment rental and purchase of services for use in motion picture and video production"). The buyer ticks single use or blanket (blanket works while buyer and seller have at least one sale within 12 months), enters the seller's name, mailing address and the date, checks the line named below, lists the items purchased, and completes the certification block: type of entity, type of business, Account ID, buyer name and title, street address, and signature. The form says it is not for resale purchases.
What the seller keeps
RCW 82.08.0315(4): "In order to claim an exemption under this section, the purchaser must provide the seller with an exemption certificate in a form and manner prescribed by the department. The seller shall retain a copy of the certificate for the seller's files." Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith. RCW 82.04.470 governs reseller permits and wholesale sales; it is not the documentation rule for this exempt retail sale.
Common mistakes
- Exempting a camera sale. Only rentals of production equipment are exempt; purchases are not.
- Treating every video maker as a production business. A company making videos for its own use does not meet the definition, which requires exhibition, sale or broadcast by someone else.
- Exempting a general vehicle rental. Vans and trucks qualify only if specially equipped for production or used solely for production activities.
- Listing nothing on the certificate. Form REV 27 0023 asks the buyer to list the equipment rented and the services bought.
Common questions
- Can a production company buy lights tax-free under this exemption?
- No. The exemption covers renting production equipment, not buying it.
- Is sound mixing by a post house exempt?
- Yes, for a qualifying production business; sound mixing is a listed production service. Color grading is not named in the list; it is exempt only if the work is one of the listed services (for example editing or video processing). Ask DOR before treating it as exempt.
- Which form should the production use?
- DOR accepts either the Motion Picture and Video Production Business Exemption Certificate (REV 27 0023) or the Buyer's Retail Sales Tax Exemption Certificate (REV 27 0032), line 5b.
- Does a rental car for the crew qualify?
- Only if it is a vehicle specially equipped for production or used solely for production activities. When it is, form REV 27 0023 says the exemption also covers the additional sales tax on rental cars.
Sources
- RCW 82.08.0315 (1)(a)-(c), (2)-(4)
- RCW 82.12.0315 (1)(a)-(c), (3) use tax
- DOR form REV 27 0023 (5/25/21), Motion Picture and Video Production Business Exemption Certificate Page 1
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 1 single use/blanket; page 3 line 5b; page 6 line 5b instructions; page 4 certification and retention
- DOR Tax incentive programs Sales/Use tax exemption for motion picture and video production companies
- DOR Exemption forms Form list (27 0023, 27 0032)
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- RCW 82.04.470 (1), (7) reseller permits and wholesale sales
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.0315(2)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal