REV 27-0036
Livestock nutrient management equipment and facilities
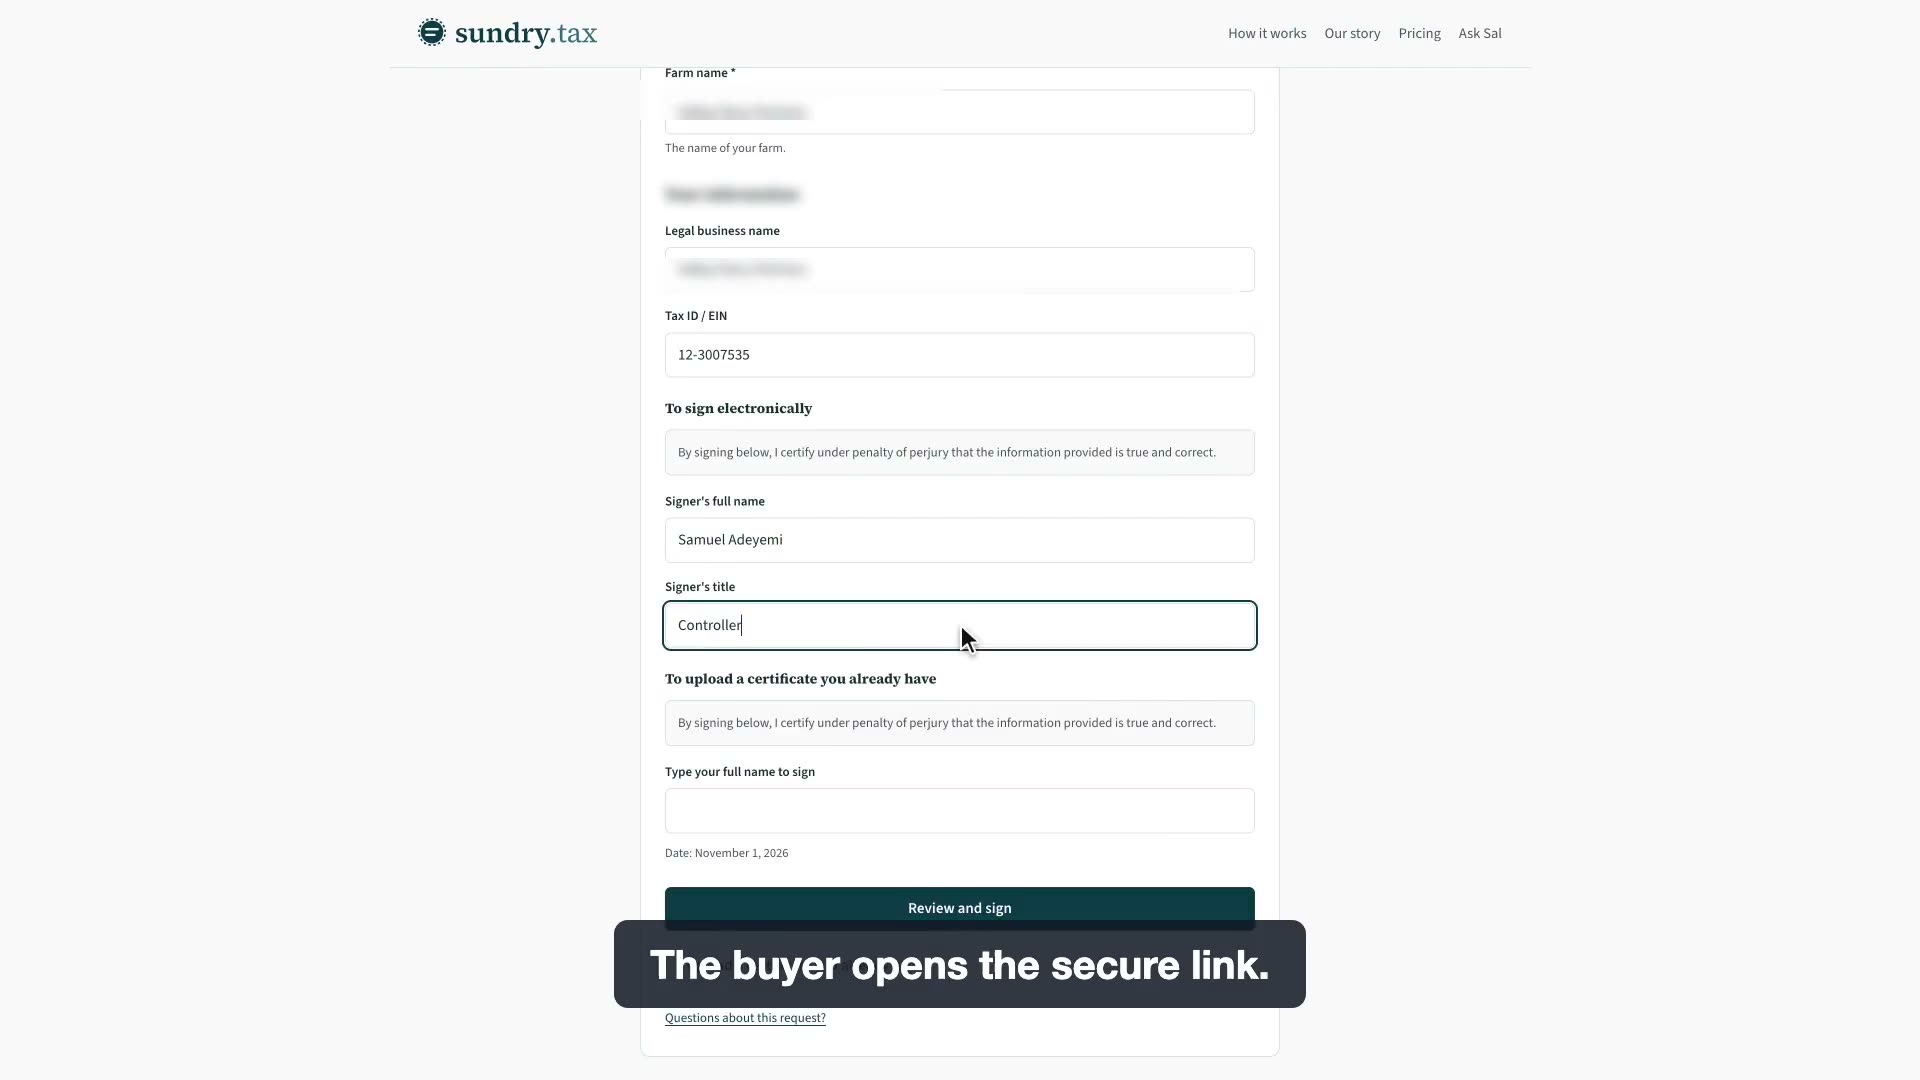
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Dairies and animal feeding operations with a certified or approved nutrient management plan pay no Washington sales or use tax on listed manure-handling equipment, its repair, and repairs to manure facilities such as lagoons and storage tanks. Building a new lagoon or replacing a facility stays taxable, and the equipment must be used only for manure.
Who qualifies
- A person licensed to produce milk under chapter 15.36 RCW with a certified dairy nutrient management plan under chapter 90.64 RCW.
- A person who owns an animal feeding operation and holds a state waste discharge or NPDES permit under chapter 90.48 RCW.
- A person who owns an animal feeding operation with a nutrient management plan approved by a conservation district as meeting NRCS field office technical guide standards, and who qualifies as an eligible farmer under RCW 82.08.855.
- The exemption applies to sales made after the plan is certified or approved.
- "Animal feeding operation": a lot or facility where animals are confined and fed for 45 days or more in any 12-month period and crops or forage are not sustained over any part of it in the normal growing season.
What qualifies
- Listed equipment for exclusive use in handling and treating livestock manure, with its repair and replacement parts: aerators, agitators, augers, conveyers, gutter cleaners, hard-hose reel traveler irrigation systems, lagoon and pond liners and floating covers, loaders, manure composting devices, manure spreaders, manure tank wagons, manure vacuum tanks, poultry house cleaners, flame sterilizers and washers, poultry litter saver machines, pipes, pumps, scrapers, separators, slurry injectors and hoses, and wheelbarrows, shovels and pitchforks.
- Labor and services to install, repair, clean, alter or improve that equipment.
- Labor, services and materials to repair, clean, alter or improve qualifying facilities used exclusively for manure: flush systems, lagoons, liquid manure storage structures such as concrete or glass-lined steel tanks, and structures used solely for dry manure storage, including roofed stacking facilities.
Not covered
- Labor and materials to construct new, or replace existing, nutrient management facilities.
- Equipment not used exclusively for handling and treating manure, such as a loader also used for feed or hay.
- Applying manure through pivot or linear traveling irrigation systems; that is outside "handling and treatment of livestock manure."
- Purchases before the plan is certified or approved.
- Equipment not on the statutory list.
What the buyer gives
Form REV 27 0036 (revision 7/13/23), Section B line 7: "Livestock nutrient management equipment and facilities." In place of the certificate, a seller may capture the relevant data elements as allowed under the streamlined sales and use tax agreement. The Department of Agriculture provides the department with lists of dairy and permitted operations on request, and conservation districts keep lists of operations with approved plans so the department can check eligibility. The signature block asks for Account ID (if applicable), type of entity, name of buyer, farm name, mailing address, authorized signature, date, title and phone number. By signing, the buyer states it qualifies, that it "must keep records to verify the exempt nature of the sale," and that misuse "will result in taxes due, applicable interest, and possible penalties." The form has no field for the seller's name. The buyer ticks single use or blanket; a blanket certificate stays valid while there is at least one sale within 12 months. Cannabis growers and producers cannot use the form.
What the seller keeps
RCW 82.08.890(3)(b): "The seller must retain a copy of the certificate or the data elements for the seller's files." Form REV 27 0036 says the seller "must retain the original of this certificate for their records" and must not send a copy to the Department, and: "A seller who accepts this completed certificate is relieved of the responsibility to collect retail sales or use tax unless the seller fraudulently fails to collect the tax or solicits the purchaser to participate in unlawfully claiming the exemption." The certificate does not expire while buyer and seller have at least one sale within twelve consecutive months; after a longer gap the seller must obtain a new form. WAC 458-20-210(10): "Without proper documentation, sellers are liable for payment of the retail sales tax on sales claimed as exempt." RCW 82.32.070(1) requires records to be kept for five years, and RCW 82.08.050(7)(a)-(b) gives the 90-day and 120-day windows for obtaining a fully completed certificate.
Common mistakes
- Treating a new lagoon or a replacement storage tank as exempt. Constructing new or replacing previously existing facilities is excluded.
- Buying a general-purpose skid steer on the certificate. Loaders qualify only for exclusive use in handling and treating manure.
- Using the exemption before the plan is certified or approved. It applies only to sales after that date.
- A conservation-district-plan operation that is not an eligible farmer. The third path also requires qualifying for the replacement parts exemption in RCW 82.08.855.
Common questions
- Is a new manure spreader exempt from Washington sales tax for a dairy?
- Yes, if the dairy is licensed to produce milk with a certified dairy nutrient management plan, the spreader is used only for manure, and the dairy gives the seller a completed REV 27 0036 with line 7 checked.
- Is relining our existing lagoon exempt?
- Repairing, altering or improving an existing qualifying facility is exempt, and lagoon liners are listed equipment. Constructing a new lagoon or replacing an existing one is not.
- Does use tax apply to equipment bought out of state?
- Not to qualifying equipment. RCW 82.12.890 exempts the use if the equipment and facilities are used exclusively for activities necessary to maintain a livestock nutrient management plan.
Sources
- RCW 82.08.890 (1)-(4) exemption, timing, lists, records, definitions
- RCW 82.12.890 (1)-(3) matching use tax exemption, exclusive use
- WAC 458-20-210 (9)(m) nutrient management equipment and facilities; (10)
- DOR form REV 27 0036 (7/13/23), Farmer's Certificate for Wholesale Purchases and Sales Tax Exemptions Page 2 line 7; page 2 signature and seller text; page 4 line 7 instructions
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0036: Farmer's Certificate for Wholesale Purchases and Sales Tax Exemptions
- Statute
- RCW 82.08.890
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal