REV 27-0032
Large private airplanes (over 41,000 lb) bought by nonresidents, and their repair
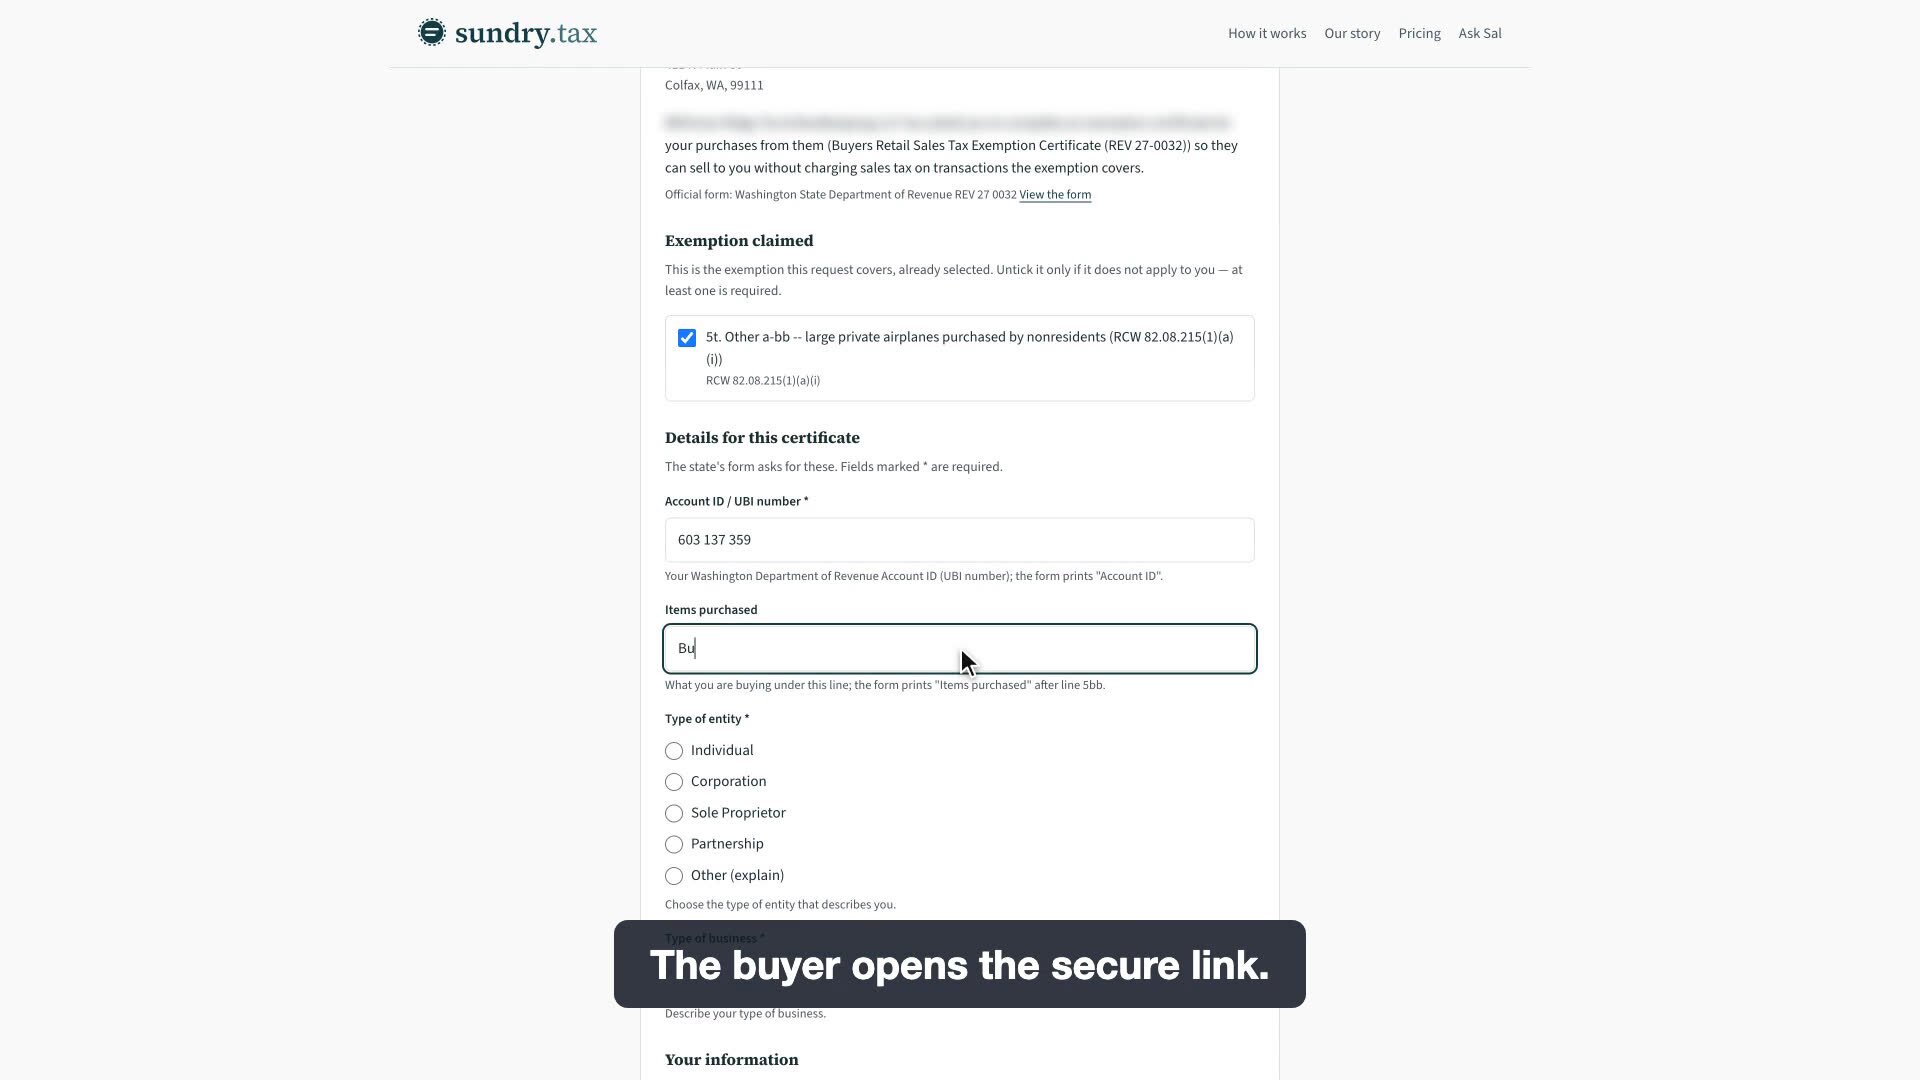
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Nonresidents pay no Washington sales or use tax when they buy a large private airplane (over 41,000 pounds), or pay for repairs, cleaning, alterations or improvements to one they own. The airplane must not be required to register with the Washington State Department of Transportation. The exemption expires July 1, 2031.
Who qualifies
- A nonresident of Washington buying a large private airplane.
- A nonresident owner of a large private airplane buying repair, cleaning, alteration or improvement services for it.
What qualifies
- A "large private airplane": not used in interstate commerce, not owned or leased by a government entity, weighing more than 41,000 pounds, and assigned an FAA test flow management system aircraft weight class A, B, C or D.
- Only when the airplane is not required to be registered with the Department of Transportation under chapter 47.68 RCW.
- Registration does not apply to a nonresident's aircraft that stays in Washington less than 90 days. A large private airplane may stay 90 days or longer only when it is here exclusively for repairs, alterations or reconstruction (including related flight testing) or for continual storage of at least a full calendar year, a facility employee is on board during flight testing, and the nonresident files a written statement with the Department of Transportation within 90 days of first arriving in the calendar year.
Not covered
- Airplanes of 41,000 pounds or less.
- Airplanes used in interstate commerce. The for-hire carrier exemption (RCW 82.08.0262) may apply instead.
- Airplanes owned or leased by a government entity.
- Washington residents.
- Airplanes required to register with the Department of Transportation, for example one kept here 90 days or more for reasons other than the listed repair, alteration, reconstruction or storage.
- Sales on or after July 1, 2031, when RCW 82.08.215 expires.
What the buyer gives
The Buyer's Retail Sales Tax Exemption Certificate, form REV 27 0032 (6/17/25), line 5t: "Large/private airplanes purchased by nonresidents." The buyer ticks single use or blanket (blanket works while buyer and seller have at least one sale within 12 months), enters the seller's name, mailing address and the date, checks the line named below, lists the items purchased, and completes the certification block: type of entity, type of business, Account ID, buyer name and title, street address, and signature. The form says it is not for resale purchases. The owner or lessee must give DOR, on request, a copy of the written statement filed with the Department of Transportation documenting the airplane's registration exemption, and any other information DOR requires.
What the seller keeps
RCW 82.08.215(2): "Sellers making tax-exempt sales under this section must obtain an exemption certificate from the buyer in a form and manner prescribed by the department. The seller must retain a copy of the exemption certificate for the seller's files. In lieu of an exemption certificate, a seller may capture the relevant data elements as allowed under the streamlined sales and use tax agreement." For sellers who file electronically, DOR provides a separate reporting line for these exempt amounts. Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith. RCW 82.04.470 governs reseller permits and wholesale sales; it is not the documentation rule for this exempt retail sale.
Common mistakes
- Exempting a light jet. The airplane must weigh more than 41,000 pounds and carry an FAA weight class A, B, C or D.
- Assuming a long repair stay is fine without the written statement. For 90 days or more, the owner must file it with the Department of Transportation within 90 days of first arrival.
- Using line 5t for an airplane used in interstate commerce. Such airplanes are outside the definition.
- Missing the separate reporting line for these exemptions on the electronic return.
Common questions
- An out-of-state owner's business jet is in our shop for a four-month refit. Is the labor taxable?
- Not if it is a large private airplane (over 41,000 pounds, weight class A-D, not in interstate commerce, not government owned), it is here only for the repairs or alterations, a shop employee is aboard any test flight, and the owner filed the written statement with the Department of Transportation within 90 days of first arrival.
- Does the buyer send the WSDOT statement to the seller?
- The statute requires the owner or lessee to give DOR a copy on request. The seller takes the completed form.
- Is anything changing in the registration law?
- A new version of RCW 47.68.250 takes effect January 1, 2027 and raises the registration fee. The nonresident large private airplane provision in (6)(c)(ii) reads the same.
Sources
- RCW 82.08.215 (1)(a)-(b), (2), (4), (5); reviser's note
- RCW 82.12.215 (1)-(4) use tax
- RCW 47.68.250 (6)(c)(i)-(ii), both versions (effective until and from January 1, 2027)
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 1 single use/blanket; page 3 line 5t; page 7 line 5t instructions; page 4 certification and retention
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- RCW 82.04.470 (1), (7) reseller permits and wholesale sales
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.215(1)(a)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal