REV 27-0055
Kidney dialysis devices
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
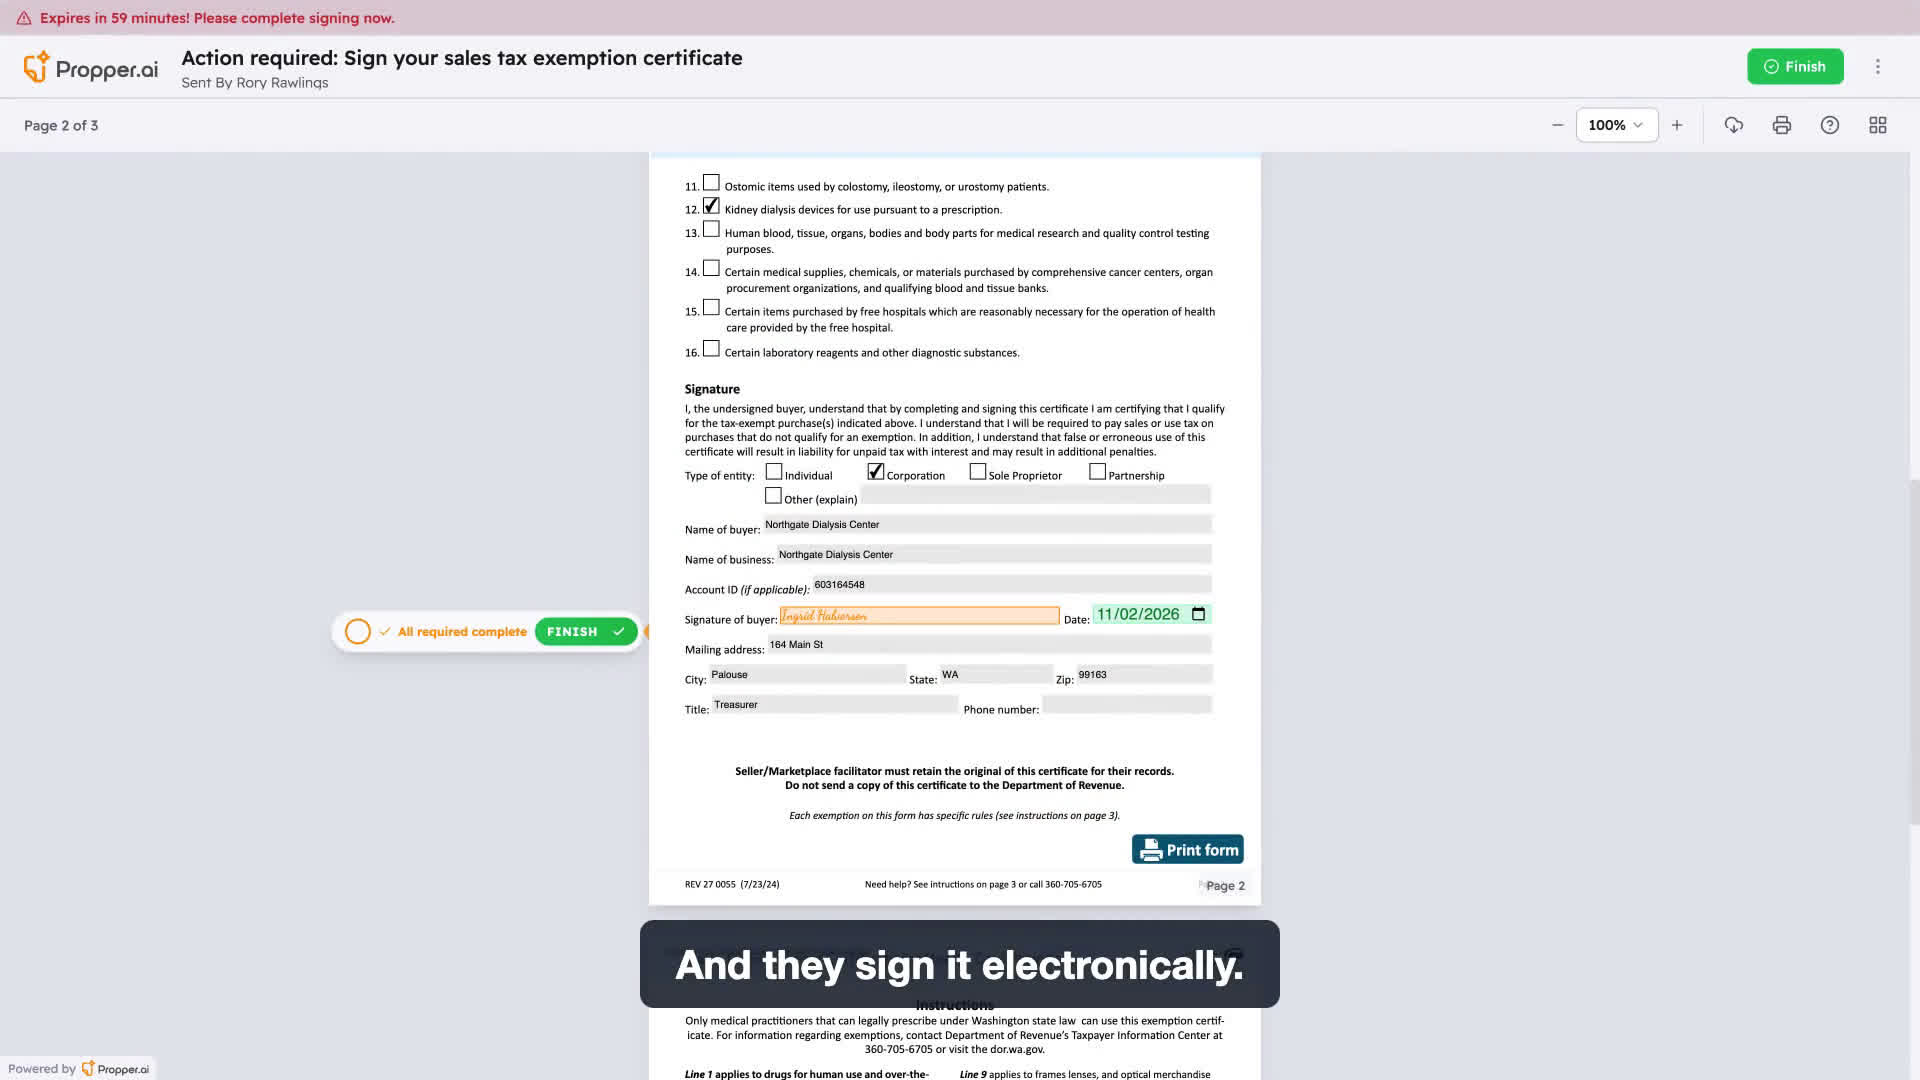
Kidney dialysis devices for human use under a prescription are exempt from Washington sales and use tax, and so are their repair and replacement parts and the labor to repair, clean, alter or improve them. Only the device that actually dialyzes the blood qualifies; equipment used alongside it does not.
Who qualifies
- Buyers of kidney dialysis devices for human use under a prescription. Health care providers buying them use form REV 27 0055, which is limited to practitioners licensed to prescribe.
What qualifies
- A kidney dialysis device: WAC 458-20-18801 defines it as a device that physically performs the dialyzing or separating process on blood.
- Repair and replacement parts for the device.
- Labor and services to repair, clean, alter or improve kidney dialysis devices (RCW 82.08.945).
- The matching use tax exemption is RCW 82.12.945.
Not covered
- Other equipment or tools used with a dialysis device. WAC example: a dedicated backup generator that powers the dialysis device during an outage is not a dialysis device.
- Devices not for human use or not under a prescription.
What the buyer gives
Form REV 27 0055, Sales Tax Exemption Certificate for Health Care Providers (revision 7/23/24), line 12, "Kidney dialysis devices for use pursuant to a prescription." The buyer ticks single use or blanket (valid while buyer and seller have at least one sale within 12 months), names the seller and the date, ticks the line for the exemption, and completes the signature block: type of entity, name of buyer, name of business, Account ID if any, signature, date, mailing address, title and phone. Only practitioners who can legally prescribe under Washington law may use the form; the form names chiropractors, East Asian medicine practitioners and massage practitioners as unable to use it.
What the seller keeps
Form REV 27 0055 says the seller or marketplace facilitator "must retain the original of this certificate for their records" and not send a copy to the Department of Revenue. WAC 458-20-18801(304): sellers to medical practitioners, nursing homes and hospitals must obtain an approved exemption form, capture the streamlined sales tax data elements, or otherwise meet RCW 82.08.050(7) for any exempt sale. A repair shop servicing the device can treat its labor as exempt under the same certificate; separately priced items that are not part of the device stay taxable. RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when the department asks; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Including generators, chairs or other supporting equipment on line 12.
- Charging sales tax on repair labor for the device. Repair, cleaning, altering and improving labor is exempt.
Common questions
- Is repair labor on a dialysis machine taxable in Washington?
- No. RCW 82.08.945 exempts labor and services to repair, clean, alter or improve kidney dialysis devices, as well as repair and replacement parts.
- Is a backup generator for a dialysis machine exempt?
- No. The WAC example says a dedicated backup generator does not perform dialysis and is not a dialysis device.
Sources
- RCW 82.08.945 Whole section
- RCW 82.12.945 Use tax
- WAC 458-20-18801 (304); (403)(o) Example 15
- DOR form REV 27 0055 (7/23/24), Sales Tax Exemption Certificate for Health Care Providers Line 12; page 3 instructions, line 12
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0055: Sales Tax Exemption Certificate for Health Care Providers
- Statute
- RCW 82.08.945
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal