REV 27-0050
Standard financial information bought by qualifying international investment management companies
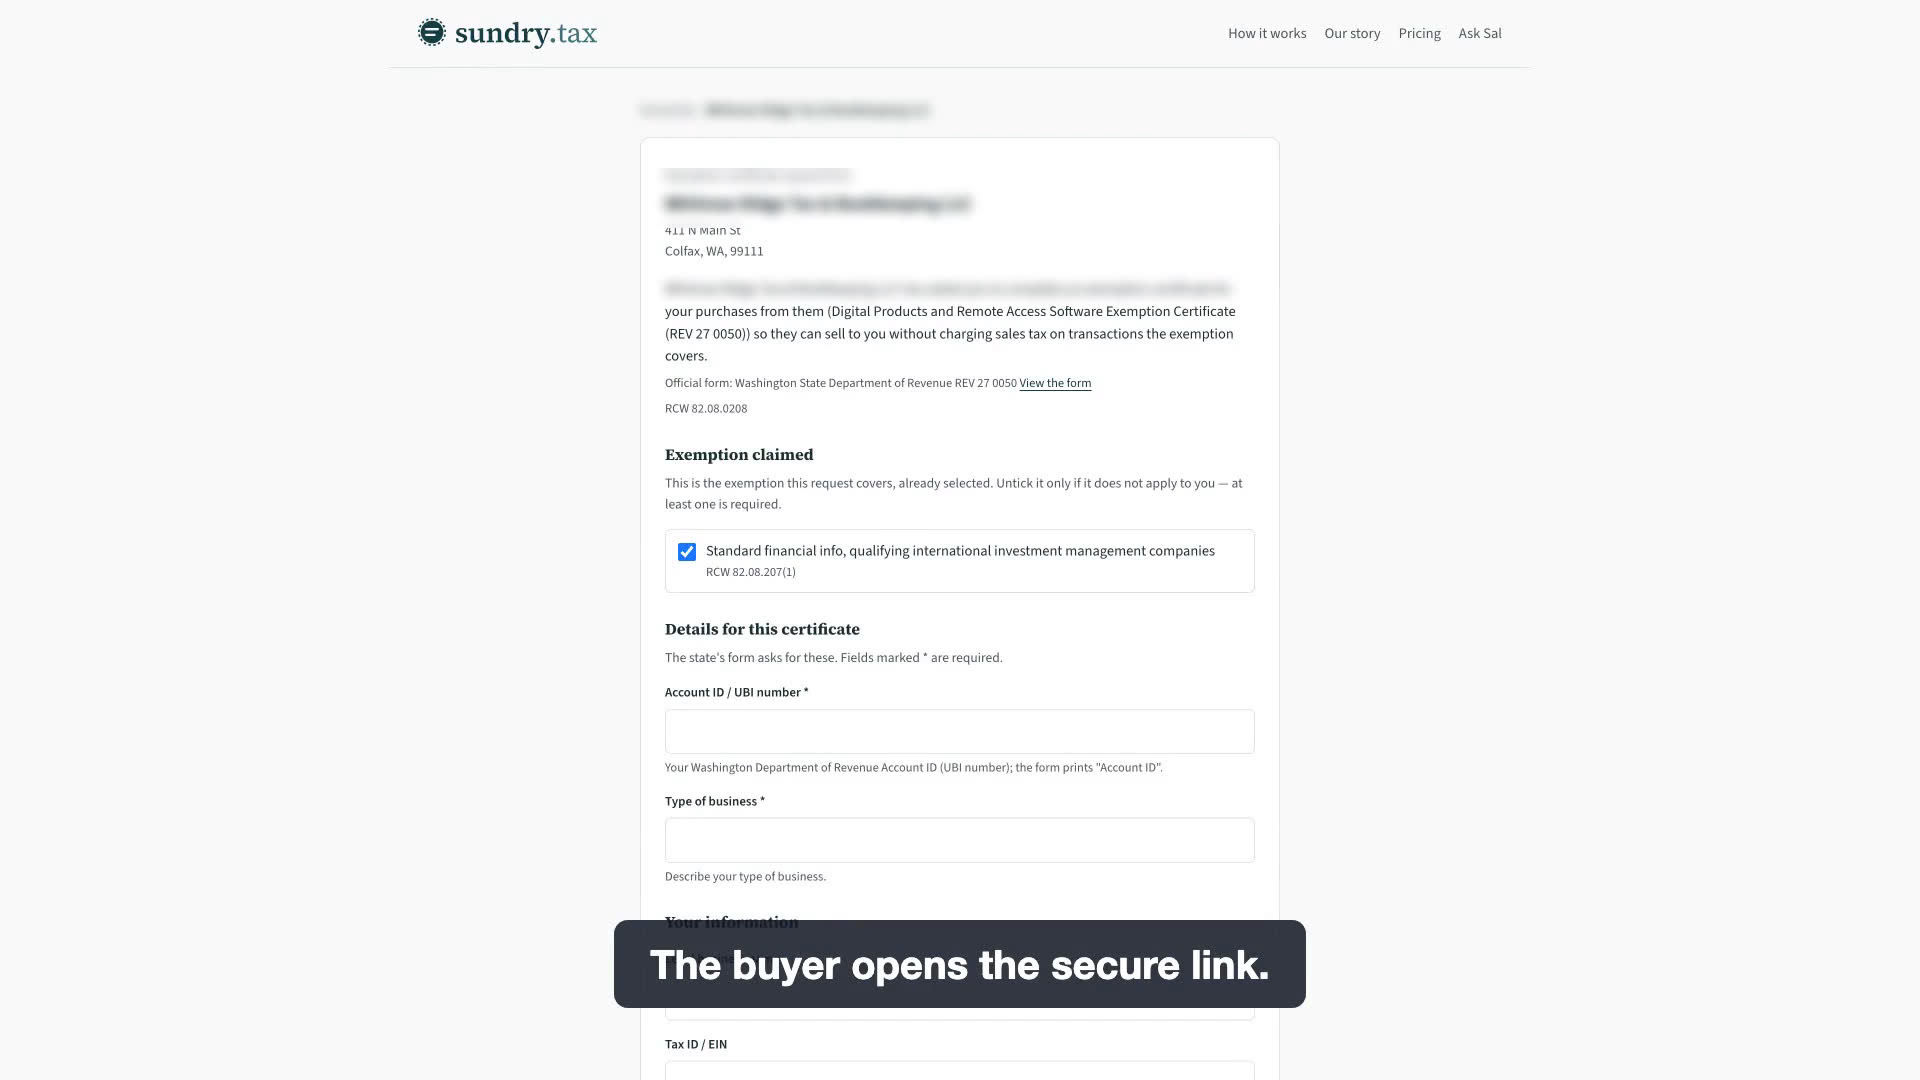
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Standard financial information, such as market data, bond and credit ratings, and loan or mortgage reports, is exempt from Washington sales and use tax when bought by a qualifying international investment management company or its affiliates, up to $15 million of purchases in a calendar year. Very few firms meet the size tests. The exemption expires July 1, 2031.
Who qualifies
- A "qualifying international investment management company": a person eligible for the B&O rate in RCW 82.04.290(1), or a person affiliated with one.
- Under RCW 82.04.293(1) the firm must be primarily in the business of investment management; earn at least 10 percent of its gross income managing collective investment funds domiciled outside the United States or with at least 10 percent of their investments outside the United States; and have more than 25 percent of its employees in Washington.
- Its affiliated group must have 10 or more offices in at least eight foreign countries, at least 500 full-time employees worldwide, worldwide gross revenue over $400 million, and average assets under management over $200 billion, in the current or preceding calendar year.
- An affiliate counts if it is primarily engaged in portfolio management, fund administration, fund distribution or transfer agent services for such funds and meets the Washington employee test.
What qualifies
- "Standard financial information": financial data, facts, information or information services not generated, compiled or developed only for a single customer.
- Examples in the statute: financial market data, bond ratings, credit ratings, and deposit, loan or mortgage reports.
- "Financial market data" means pricing for securities, commodities and derivatives; corporate actions such as dividend schedules and reorganizations; corporate attributes such as domicile, currencies and exchanges; and currency information.
- The format does not matter: paper, a tangible storage medium such as a DVD or USB drive, or electronic delivery.
Not covered
- Information generated, compiled or developed only for a single customer, such as custom research.
- Purchases after the buyer has bought more than $15 million of standard financial information in the calendar year with the exemption claimed.
- Investment advisers and financial firms that do not meet every RCW 82.04.293 test.
- Any purchase after July 1, 2031, when RCW 82.08.207 and 82.12.207 expire.
What the buyer gives
Form REV 27 0050, Digital Products and Remote Access Software Exemption Certificate (revision 11/10/25), with the box "Purchases of standard financial information delivered electronically by qualifying international investment management companies" ticked. The buyer ticks a single purchase (with the invoice or purchase order number) or a blanket certificate, valid while buyer and seller have at least one sale within twelve consecutive months; enters the seller's or marketplace facilitator's business name; gives its own business name, address, Account ID, phone, email and type of business; and signs with a printed name and date. The certification says misuse brings taxes, interest and possible penalties. The form cannot be used for purchases for personal use. The buyer may also have to report the amount of tax preference received to DOR, unless the benefit is under $1,000 a year or the buyer files an annual return (WAC 458-20-15503(506)(f)).
What the seller keeps
RCW 82.08.207(2): the seller "must obtain an exemption certificate from the buyer in a form and manner prescribed by the department" and retain a copy, or capture the streamlined sales and use tax data elements instead. Sellers who file electronically report the exempt amount on a separate line DOR provides. Under RCW 82.08.207(3) the seller is not responsible for policing the $15 million limit and is not assessed for uncollected tax on sales after the buyer exceeds it, except as provided in RCW 82.08.050(4) and (5). Form REV 27 0050: keep a copy and do not send it to the Department. RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when the department asks; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- A local investment adviser claiming the exemption. The size and international tests in RCW 82.04.293 are cumulative.
- Including reports produced only for this client. Custom work is not standard financial information.
- Continuing to claim it after $15 million of exempt purchases in the year. The buyer must stop; the seller does not track the limit.
- Using the general business purpose box instead. The business purpose exemption covers digital goods only, while this one covers standard financial information in any format.
Common questions
- Can a market data vendor sell to an investment firm in Washington without charging sales tax?
- Only if the buyer is a qualifying international investment management company or its affiliate and gives a completed REV 27 0050. Most investment firms do not meet the RCW 82.04.293 tests, which include $200 billion of average assets under management across the affiliated group.
- Does the exemption apply to printed reports, or only electronic data?
- The statute covers paper, tangible media and electronic delivery. Note that the form's checkbox reads "delivered electronically"; for paper deliveries, confirm with DOR which certificate to use.
- When does this exemption end?
- RCW 82.08.207 and RCW 82.12.207 expire July 1, 2031.
Sources
- RCW 82.08.207 (1)-(5)
- RCW 82.12.207 (1)-(3)
- RCW 82.04.293 (1)-(2)
- WAC 458-20-15503 (506)(a)-(f)
- DOR form REV 27 0050 (11/10/25), Digital Products and Remote Access Software Exemption Certificate Section 1 standard financial information box; page 3 section 6
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0050: Digital Products and Remote Access Software Exemption Certificate
- Statute
- RCW 82.08.207(1)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal