REV 27-0036
Replacement parts and repair services for qualifying farm machinery and equipment
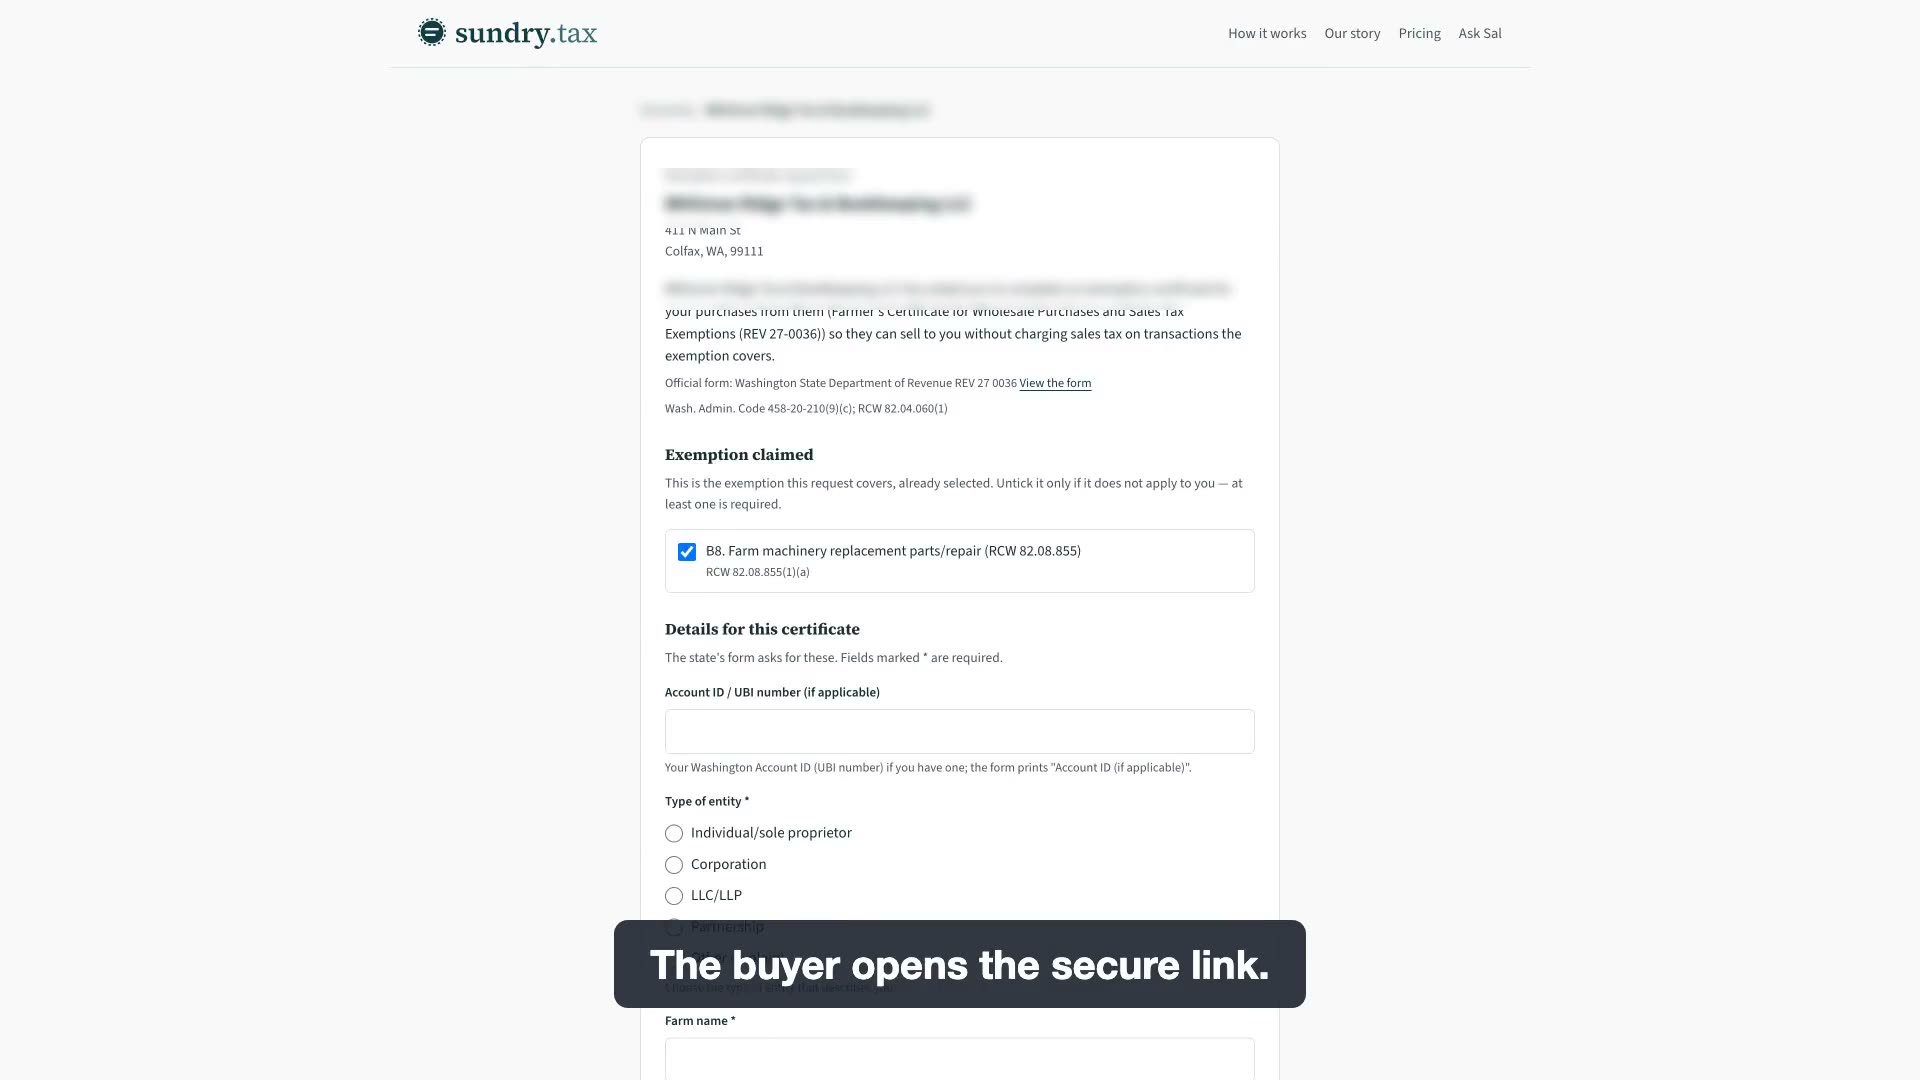
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
An eligible farmer, one with at least $10,000 a year in sales or harvested value, pays no Washington sales or use tax on replacement parts for qualifying farm machinery and equipment, or on the labor to install them and repair the machine. The new machine itself, shop supplies, hand tools and most road vehicles stay taxable.
Who qualifies
- An "eligible farmer": a farmer whose gross sales or harvested value of agricultural products, or gross sales of bee pollination services, was at least $10,000 in the immediately preceding tax year.
- A farmer that sold or harvested nothing last year but whose agricultural products had an estimated value of at least $10,000.
- A farmer that only changed identity or form of ownership with no change in beneficial ownership, where the combined amounts met the test.
- A farmer new to farming or newly returned to farming. The exemption is conditional: if the farmer does not reach $10,000 in sales or harvested value (or estimated value) in its first full tax year, the exempted taxes are due within 30 days after that year ends, with interest.
What qualifies
- "Qualifying farm machinery and equipment": machinery and equipment used primarily by an eligible farmer to grow, raise or produce agricultural products or provide bee pollination services, including farm tractors, farm vehicles and other farm implements.
- "Replacement parts": parts that replace an existing part, or that are essential to maintain the working condition, of qualifying machinery or equipment.
- Labor and services to install replacement parts.
- Labor and services to repair qualifying machinery, if nothing other than replacement parts is installed or becomes a component during the repair.
- Paint, fuel, oil, hydraulic fluids, antifreeze and similar items, only when installed during the installation of replacement parts or a qualifying repair.
Not covered
- Vehicles other than farm tractors, farm vehicles and farm implements. Lawn tractors and all-terrain vehicles are not farm implements.
- Aircraft.
- Hand tools and hand-powered tools.
- Property with a useful life of less than one year.
- Paint, fuel, oil, hydraulic fluids and antifreeze bought on their own, outside a parts installation or repair.
- The machinery itself. WAC 458-20-210 says sales of farming equipment such as machinery are retail sales unless specifically exempt; this exemption covers replacement parts and labor.
What the buyer gives
Form REV 27 0036 (revision 7/13/23), Section B line 8: "Replacement parts and repair services for qualifying farm machinery and equipment." In place of the certificate, RCW 82.08.855(3)(a) lets a seller "capture the relevant data elements as allowed under the streamlined sales and use tax agreement." The buyer must keep the records the department needs to verify eligibility. The signature block asks for Account ID (if applicable), type of entity, name of buyer, farm name, mailing address, authorized signature, date, title and phone number. By signing, the buyer states it qualifies, that it "must keep records to verify the exempt nature of the sale," and that misuse "will result in taxes due, applicable interest, and possible penalties." The form has no field for the seller's name. The buyer ticks single use or blanket; a blanket certificate stays valid while there is at least one sale within 12 months. Cannabis growers and producers cannot use the form.
What the seller keeps
RCW 82.08.855(3)(a): "The seller must retain a copy of the certificate or the data elements for the seller's files." On a mixed repair ticket, the labor exemption applies only if the seller separately itemizes the exempt labor and that charge does not exceed its usual and customary charge (RCW 82.08.855(2)). Form REV 27 0036 says the seller "must retain the original of this certificate for their records" and must not send a copy to the Department, and: "A seller who accepts this completed certificate is relieved of the responsibility to collect retail sales or use tax unless the seller fraudulently fails to collect the tax or solicits the purchaser to participate in unlawfully claiming the exemption." The certificate does not expire while buyer and seller have at least one sale within twelve consecutive months; after a longer gap the seller must obtain a new form. WAC 458-20-210(10): "Without proper documentation, sellers are liable for payment of the retail sales tax on sales claimed as exempt." RCW 82.32.070(1) requires records to be kept for five years, and RCW 82.08.050(7)(a)-(b) gives the 90-day and 120-day windows for obtaining a fully completed certificate.
Common mistakes
- Accepting the certificate from a hobby farm. The statute requires an eligible farmer with at least $10,000 in sales, harvested value or estimated value, which is narrower than the form's word "farmers."
- Lumping labor into one repair price. If the job mixes exempt and taxable services, the exempt labor must be separately itemized at no more than the usual charge.
- Exempting an oil change. Oil, fluids and antifreeze qualify only when installed during a replacement-part installation or a qualifying repair.
- Exempting parts for the farm pickup or an ATV. Vehicles other than farm tractors, farm vehicles and farm implements are excluded, and ATVs are not farm implements.
Common questions
- Are tractor repair parts exempt from Washington sales tax?
- Yes, for an eligible farmer. A farm tractor used primarily to produce agricultural products is qualifying machinery, so its replacement parts and the labor to install them are exempt when the farmer gives a completed REV 27 0036 with line 8 checked.
- I just started farming. Can I use the exemption?
- Yes, conditionally. If you do not reach $10,000 in sales or harvested value (or estimated value, if you sell or harvest nothing) in your first full tax year, you must repay the exempted taxes within 30 days after that year ends, with interest but no penalties if paid on time.
- What if I stop farming after buying parts tax-free?
- RCW 82.12.855(5): apart from the new-farmer rule, the department may not assess use tax against a person who no longer qualifies if the person was an eligible farmer when it first put the parts or services to use in Washington.
- Are hand tools for the shop exempt?
- No. Hand tools and hand-powered tools are excluded from qualifying farm machinery and equipment.
Sources
- RCW 82.08.855 (1)-(4) exemption, itemized labor, records, eligible farmer, definitions
- RCW 82.12.855 (1)-(5) matching use tax exemption
- RCW 82.04.213 (1) agricultural product; (3) farmer
- WAC 458-20-210 (7)(e) farming equipment; (9)(q) replacement parts; (10)
- DOR form REV 27 0036 (7/13/23), Farmer's Certificate for Wholesale Purchases and Sales Tax Exemptions Page 2 line 8; page 2 signature and seller text; page 4 line 8 instructions
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0036: Farmer's Certificate for Wholesale Purchases and Sales Tax Exemptions
- Statute
- RCW 82.08.855
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal