REV 27-0032
Battery-powered electric marine propulsion systems and vessels equipped with them (over 15 kW)
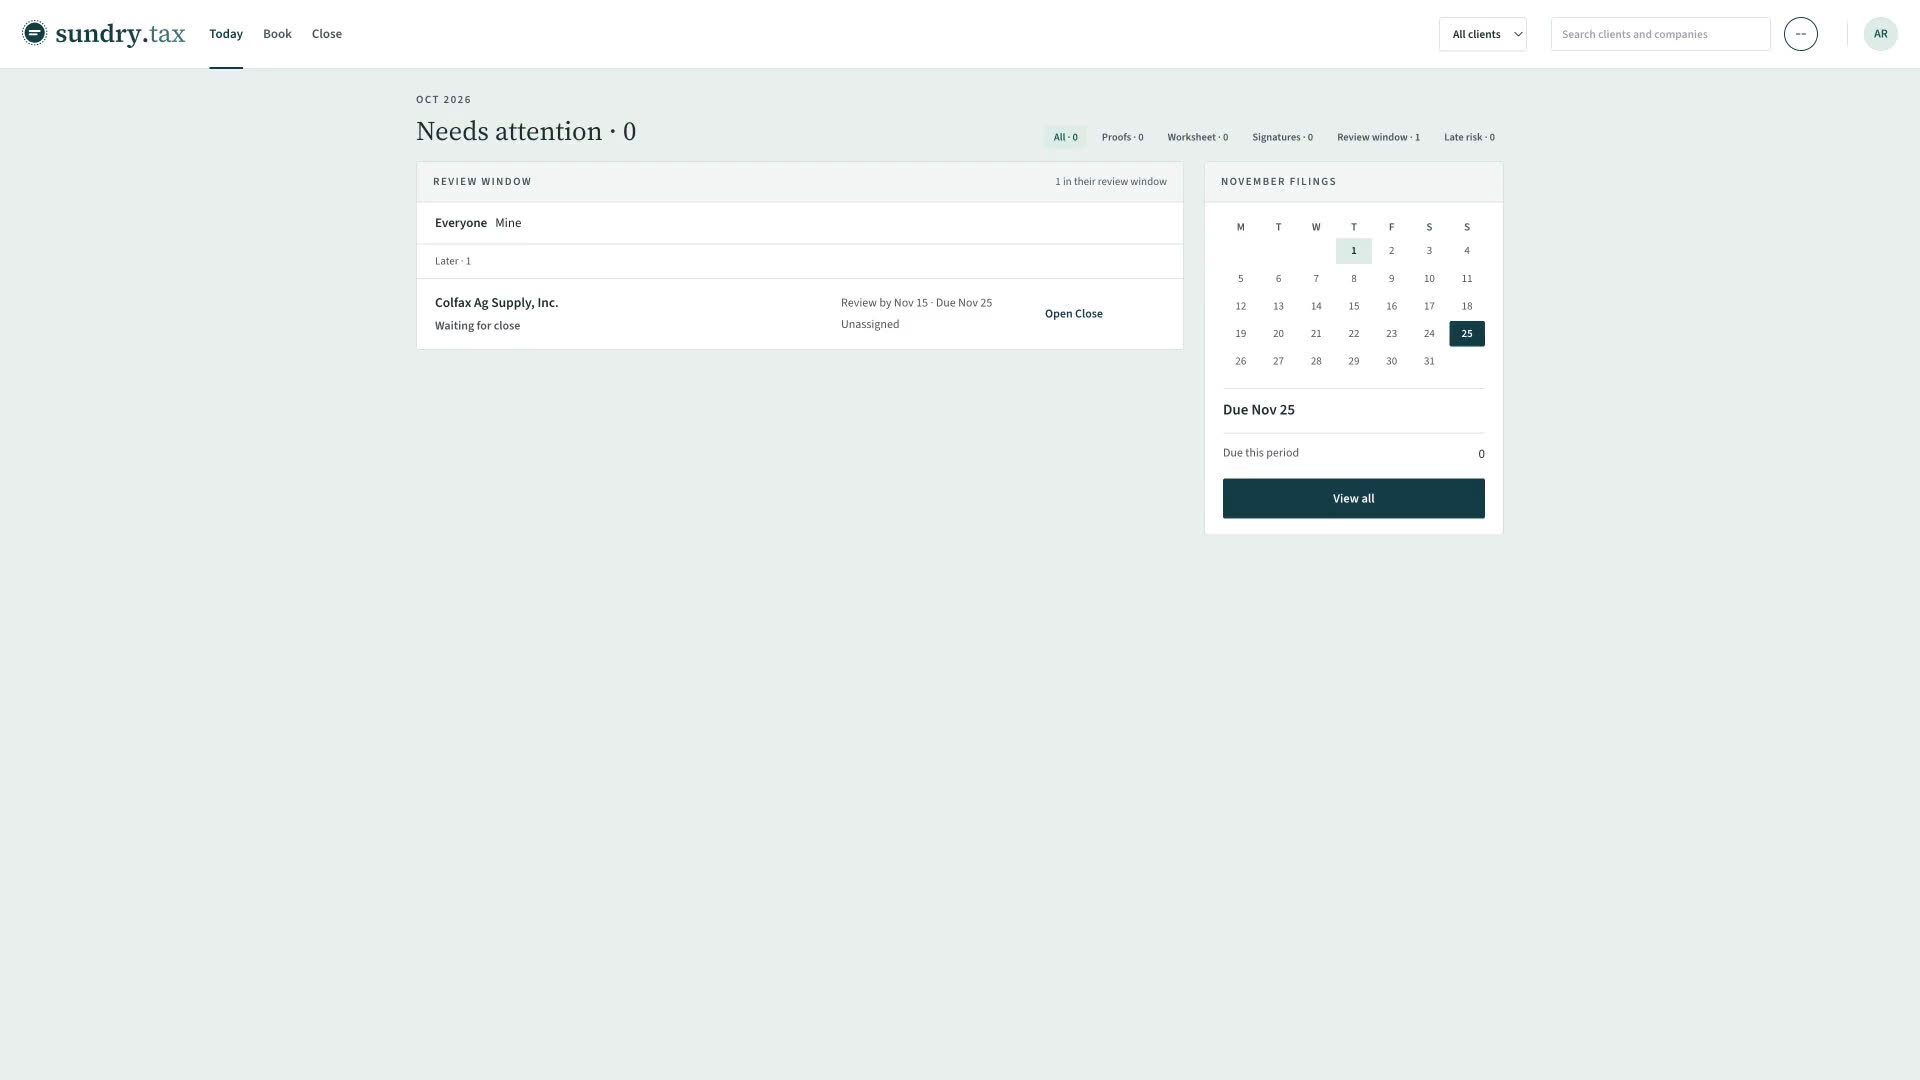
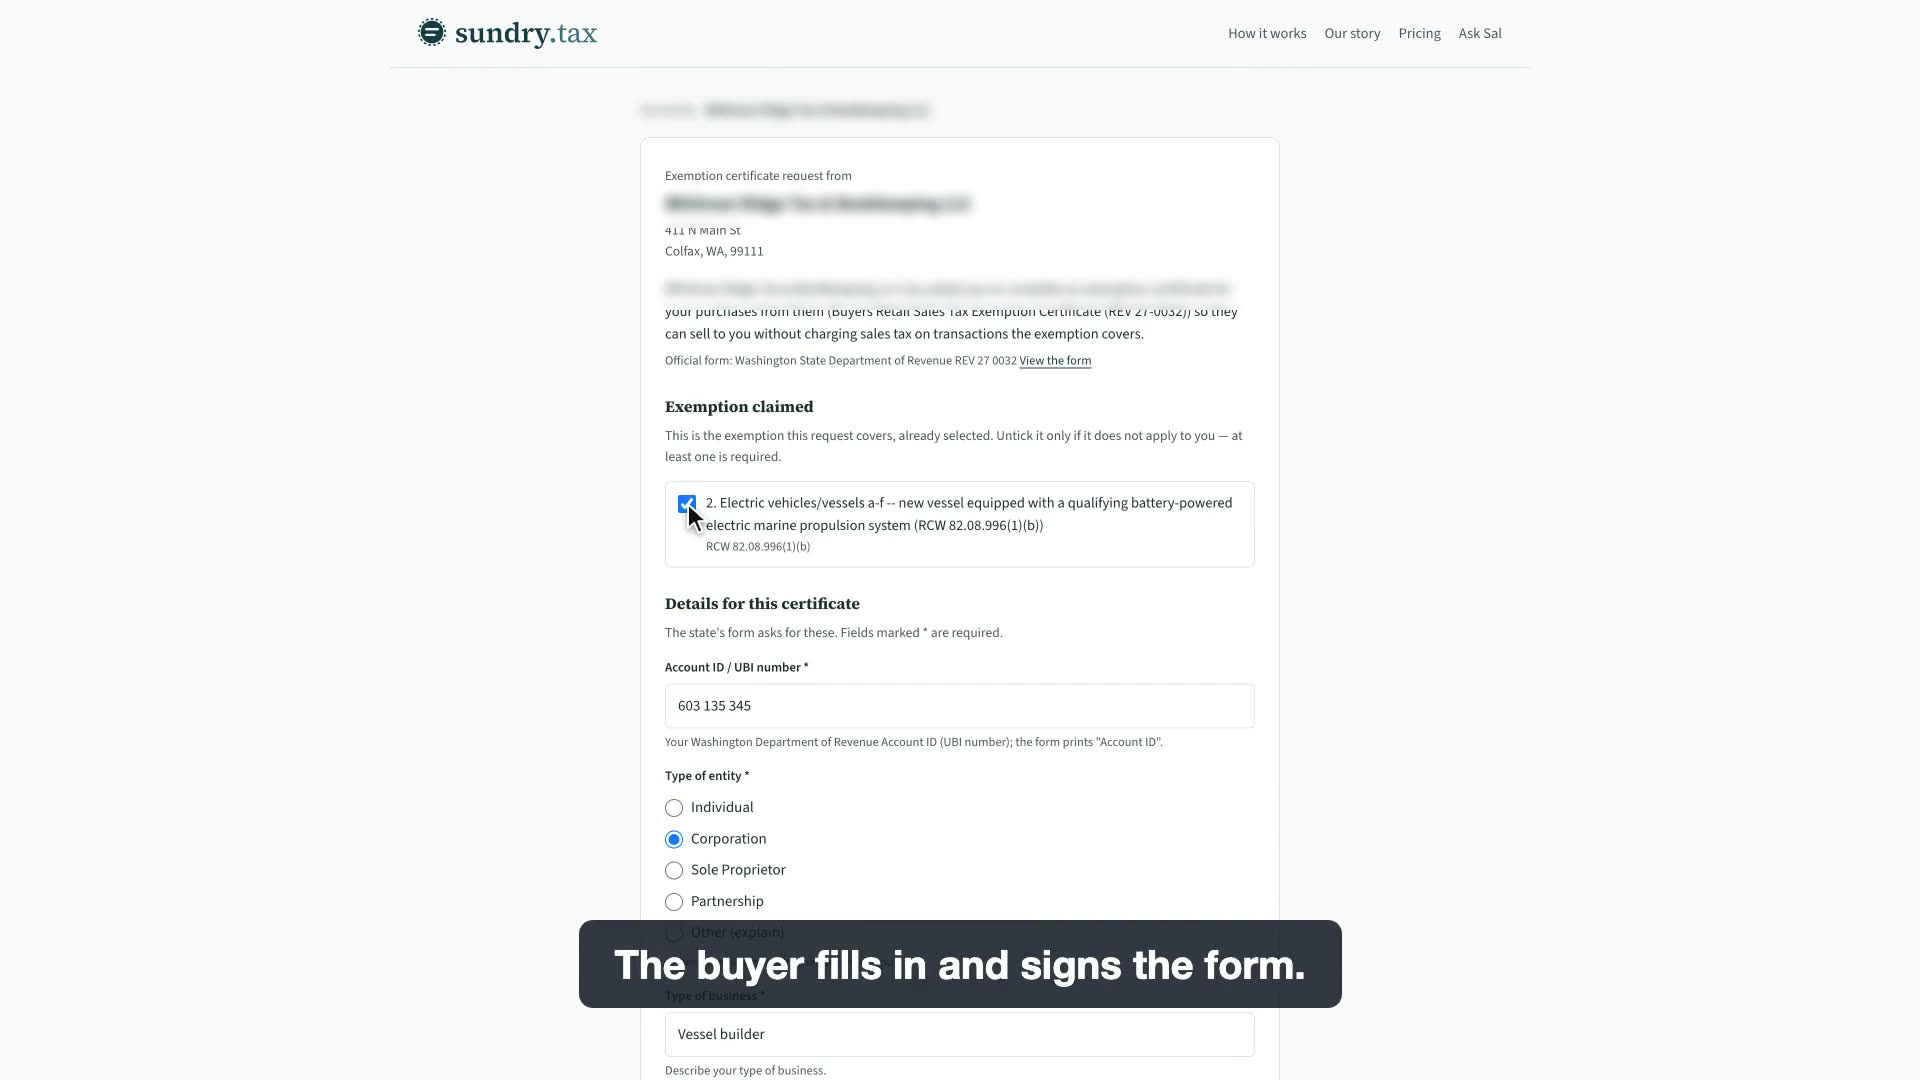
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
Propulsion systems
Vessels equipped with propulsion
New fully electric, battery-powered marine propulsion systems with continuous power over 15 kW are exempt from Washington sales and use tax, and so are new vessels equipped with them. The exemption runs to July 1, 2030.
Who qualifies
- DOR: anyone buying qualifying new vessels or qualifying new marine propulsion systems, business or individual.
What qualifies
- New battery-powered electric marine propulsion systems with continuous power greater than 15 kilowatts. Such a system is a fully electric outboard or inboard motor whose sole source of propulsive power is energy stored in battery packs, and it includes required accessories such as throttles, displays and battery packs.
- New vessels equipped with such a propulsion system. A "vessel" is any watercraft, other than a seaplane, used or capable of being used as a means of transportation on water.
- DOR: purchases beginning August 1, 2019.
Not covered
- Used vessels and used propulsion systems. The statute says "new."
- Systems with continuous power of 15 kW or less.
- Hybrid propulsion. A qualifying system's sole source of propulsive power must be battery energy. (Batteries for hybrid systems are covered separately on line 2e.)
- Seaplanes.
- Purchases on or after July 1, 2030, when RCW 82.08.996 expires.
What the buyer gives
The Buyer's Retail Sales Tax Exemption Certificate, form REV 27 0032 (6/17/25), line 2d: "Vessels equipped with battery-powered electric marine propulsion systems or the systems themselves with continuous power greater than 15kW." The buyer ticks single use or blanket (blanket works while buyer and seller have at least one sale within 12 months), enters the seller's name, mailing address and the date, checks the line named below, lists the items purchased, and completes the certification block: type of entity, type of business, Account ID, buyer name and title, street address, and signature. The form says it is not for resale purchases. The "Items purchased" field on page 4 is where the buyer lists the vessel or system. DOR: a registered business must also complete the buyer's tax preference addendum in My DOR when filing its excise tax return.
What the seller keeps
RCW 82.08.996(2): "Sellers may make tax exempt sales under this section only if the buyer provides the seller with an exemption certificate in a form and manner prescribed by the department. The seller must retain a copy of the certificate for the seller's files." DOR: report these sales with the deduction "Sales of New Electric Vessels and Marine Propulsion Systems." Form REV 27 0032 says: "Seller must retain the original of this certificate for their records. Do not send a copy of this certificate to the Department of Revenue." RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when asked; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith. RCW 82.04.470 governs reseller permits and wholesale sales; it is not the documentation rule for this exempt retail sale.
Common mistakes
- Exempting a hybrid boat under line 2d. The propulsion system must be fully electric.
- Using peak rather than continuous power. The statute's threshold is continuous power greater than 15 kW.
- Exempting a used electric boat. Only new vessels and new systems qualify.
- Using the battery deduction line. Propulsion systems and vessels have their own deduction.
Common questions
- Is a new electric outboard with a 25 kW continuous rating exempt?
- Yes, if it is fully electric and battery-powered. Its required accessories, such as the throttle, display and battery packs, are part of the system.
- Does a hybrid diesel-electric workboat qualify?
- Not under line 2d. The system's sole source of propulsive power must be battery energy. Its propulsion batteries may qualify under line 2e.
- Can an individual boater use this certificate?
- Yes. DOR lists anyone buying qualifying new vessels or propulsion systems. The addendum applies to registered businesses.
Sources
- RCW 82.08.996 (1)(a)-(b), (2), (3)(c)-(d), (3)(g), (4)
- RCW 82.12.996 (1)(a)-(b), (2)-(4) use tax
- DOR form REV 27 0032 (6/17/25), Buyer's Retail Sales Tax Exemption Certificate Page 1 single use/blanket; page 2 line 2d; page 5 line 2d instructions; page 4 certification and retention
- DOR Tax incentive programs Renewable Energy/Green Incentives: Electric vessel and marine propulsion system sales/use tax exemption
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- RCW 82.04.470 (1), (7) reseller permits and wholesale sales
- Form
- REV 27-0032: Buyers Retail Sales Tax Exemption Certificate
- Statute
- RCW 82.08.996(1)(a); RCW 82.08.996(1)(b)
- Category
- Use
- How the buyer provides it
- Signs the state form in the buyer portal