Department-issued
Sales and use tax deferral certificate: solar canopy project (RCW 82.90)
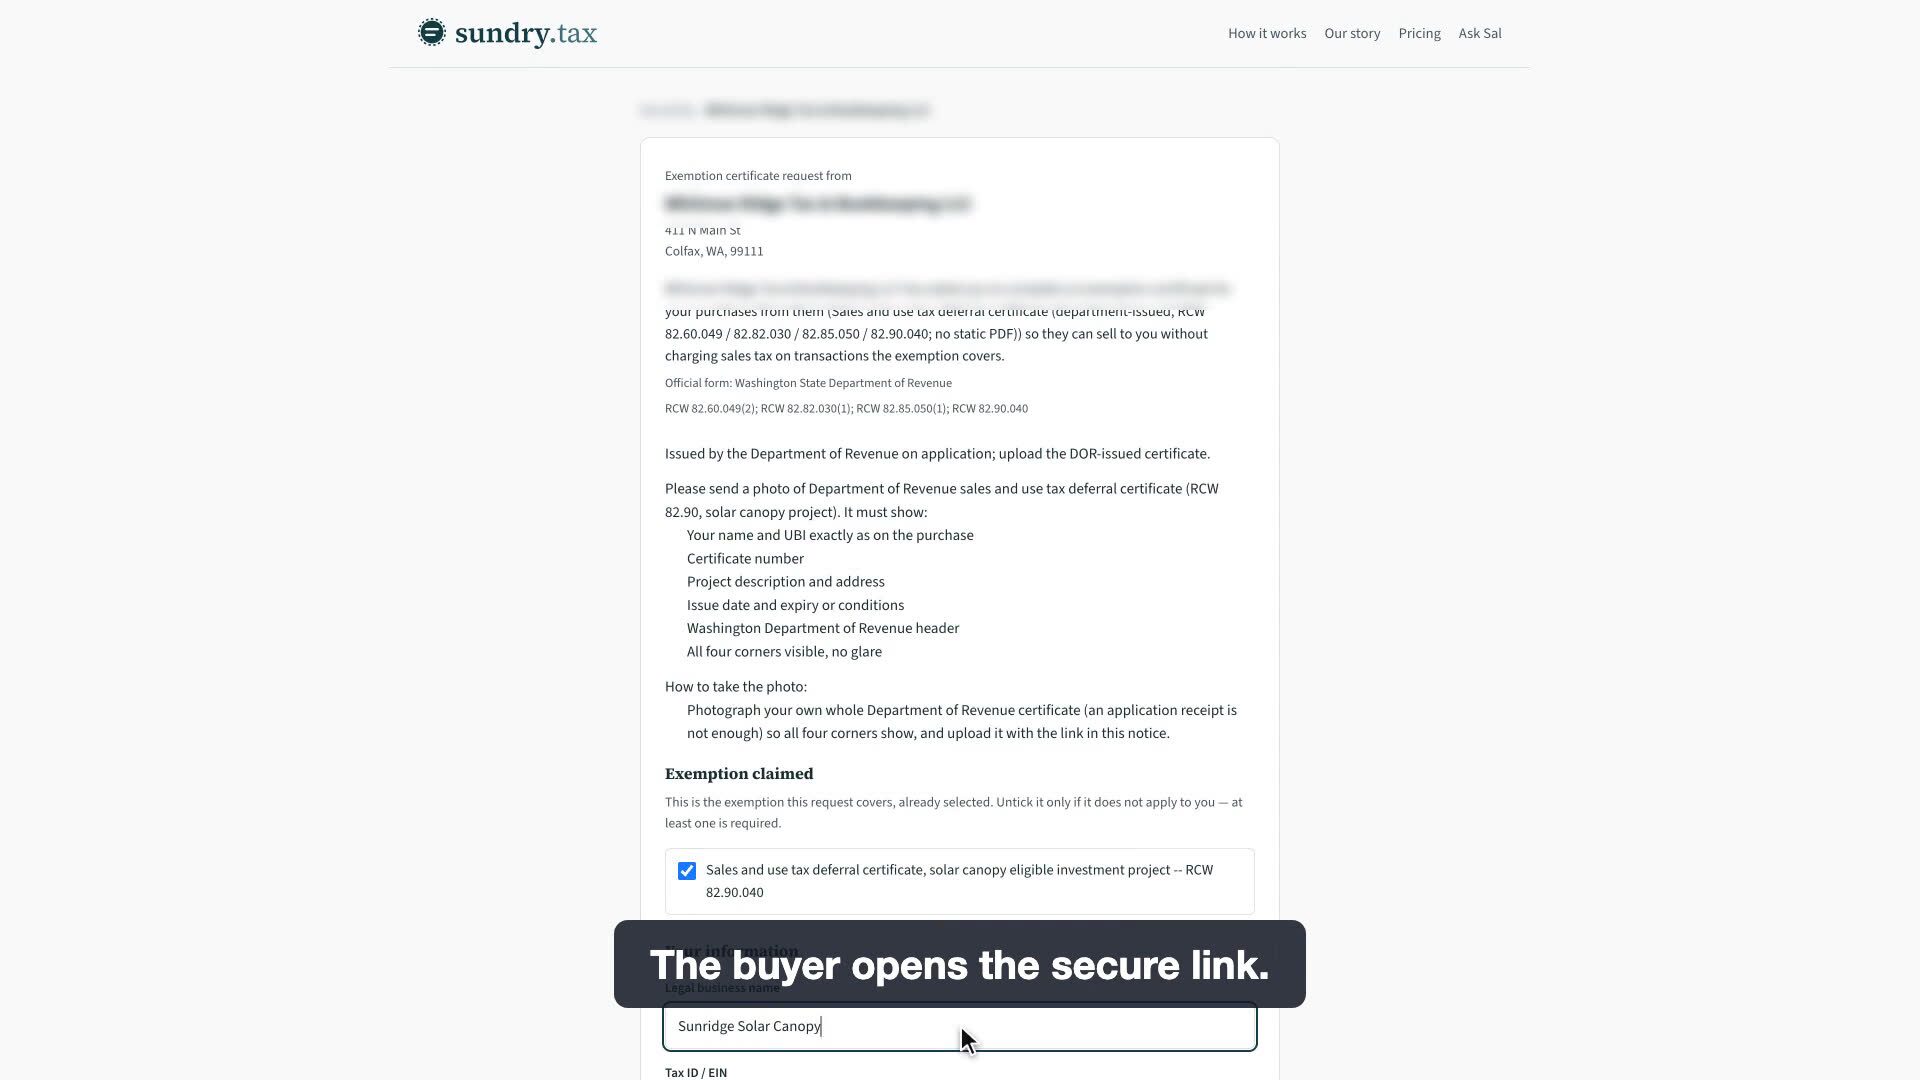
A firm asks a customer for the Department-issued certificate, the buyer uploads a photo of it from the emailed link, and Sundry shows it received and checked.
A chapter 82.90 deferral certificate lets the owner of a qualifying commercial center defer state and local sales and use tax on building a new solar canopy over a parking area: at least 50,000 square feet and at least one megawatt AC. This program is open: DOR takes applications until June 30, 2032. The tax is repaid in eight installments unless L&I labor-standard certification reduces it. The seller keeps a copy of the DOR certificate.
Who qualifies
- A person holding a deferral certificate DOR issued under RCW 82.90.040 for a solar canopy project at a qualifying commercial center: property used for retail, industrial, office or other commercial purposes with a parking or other area for both vehicles and the canopy.
- The canopy is new, covers at least 50,000 square feet, and carries a solar energy system of at least one megawatt of alternating current.
- The application must be filed before initiation of construction (the building permit date), and the holder must begin meaningful construction within one year of the certificate, unless delayed by circumstances beyond the holder's control (lack of funding does not count) (RCW 82.90.050(1)).
- A lessor qualifies only if it owns the canopy outright or passes the full economic benefit to the lessee by written contract.
What qualifies
- The investment project: the qualified solar canopy, including the solar energy system, power lines and equipment needed to connect it to the grid.
- Labor and services rendered in planning, installing and constructing the project.
- DOR's application instructions: the certificate "is valid only for qualifying purchases by the Certificate Holder at the investment project. The Certificate Holder and approved address are both stated on the certificate. Other purchases do not qualify."
Not covered
- Purchases for any other site, or by anyone other than the certificate holder.
- Rooftop arrays or canopies under 50,000 square feet or under one megawatt AC.
- Work bought before the application was filed; the application must come before initiation of construction.
- A certificate whose holder did not begin meaningful construction within one year, unless delayed by circumstances beyond the holder's control (lack of funding does not count) (RCW 82.90.050(1)), is invalid, and the deferred taxes are due.
What the buyer gives
A copy of the sales and use tax deferral certificate DOR issued for the canopy project. The buyer applies to DOR on REV 81 1039 (or REV 81 1034 for a lessor), by mail or email to DOR's Refund & Deferral Unit, before construction begins; DOR issues the certificate, which states the holder and the project address. There is no buyer-completed form for each purchase.
What the seller keeps
Chapter 82.90 RCW has no seller-specific rule. Keep a copy of the certificate as proper records of a non-taxable sale (RCW 82.08.050(4)) for five years (RCW 82.32.070(1)), and check that the buyer and delivery or job address match the certificate. DOR's rule for the chapter 82.60 deferral (WAC 458-20-24001(9)) shows its approach: the seller keeps a copy and still owes B&O tax.
Common mistakes
- Shipping to a different address. The certificate is good only at the approved project address.
- Exempting a subcontractor's purchases on the owner's certificate. The certificate is for the certificate holder's purchases.
- Telling the owner the tax is forgiven. It is repaid at 12.5 percent a year for eight years, starting December 31 of the second calendar year after completion, unless L&I certifies labor standards that reduce it by 50, 75 or 100 percent.
Common questions
- Is there a sales tax break for parking lot solar canopies in Washington?
- Yes, a deferral under chapter 82.90 RCW for new canopies of at least 50,000 square feet and one megawatt AC at commercial centers. DOR accepts applications until June 30, 2032.
- When must the application be filed?
- Before initiation of construction, which the statute ties to the date the building permit is issued.
- Can the deferred tax be reduced?
- Yes. RCW 82.90.060 reduces repayment by 50, 75 or 100 percent if L&I certifies the project met specified labor standards; DOR says to apply to L&I after receiving the deferral certificate number and before construction starts.
- What if the canopy is not finished within two years?
- RCW 82.90.070(3): if it is not operationally complete within two calendar years of the certificate, deferred taxes become due on a schedule, with interest but not penalties.
Sources
- RCW 82.90.020 (3)-(12) definitions
- RCW 82.90.030 (1)-(2) applications; none after June 30, 2032
- RCW 82.90.040 Tax deferral certificates
- RCW 82.90.050 (1)-(4) meaningful construction; reports
- RCW 82.90.060 (1) reductions
- RCW 82.90.070 (1)-(5) repayment
- RCW 82.90.080 Conditions for lessors
- DOR form REV 81 1039 (3/12/24), Solar Canopies Application for Sales and Use Tax Deferral General instructions (Certificate use, Filing, Repayment); What to do next
- DOR Deferral forms List of current deferral applications
- DOR Tax incentive programs Renewable Energy/Green Incentives: Solar canopy sales and use tax deferral
- DOR Special Notice (July 1, 2022): Solar canopy retail sales and use tax deferral What qualifies?; Applying; Deferral program requirements
- WAC 458-20-24001 (9) (chapter 82.60 deferral; shown for DOR practice)
- RCW 82.08.050 (4), (7)(a)-(c)
- RCW 82.32.070 (1) five-year record retention
- Form
- Sales and use tax deferral certificate
- Statute
- RCW 82.90.040
- Category
- Department-issued
- How the buyer provides it
- Uploads a photo of the Department-issued certificate