Department-issued
Data center (King, Pierce, Snohomish): eligible server equipment
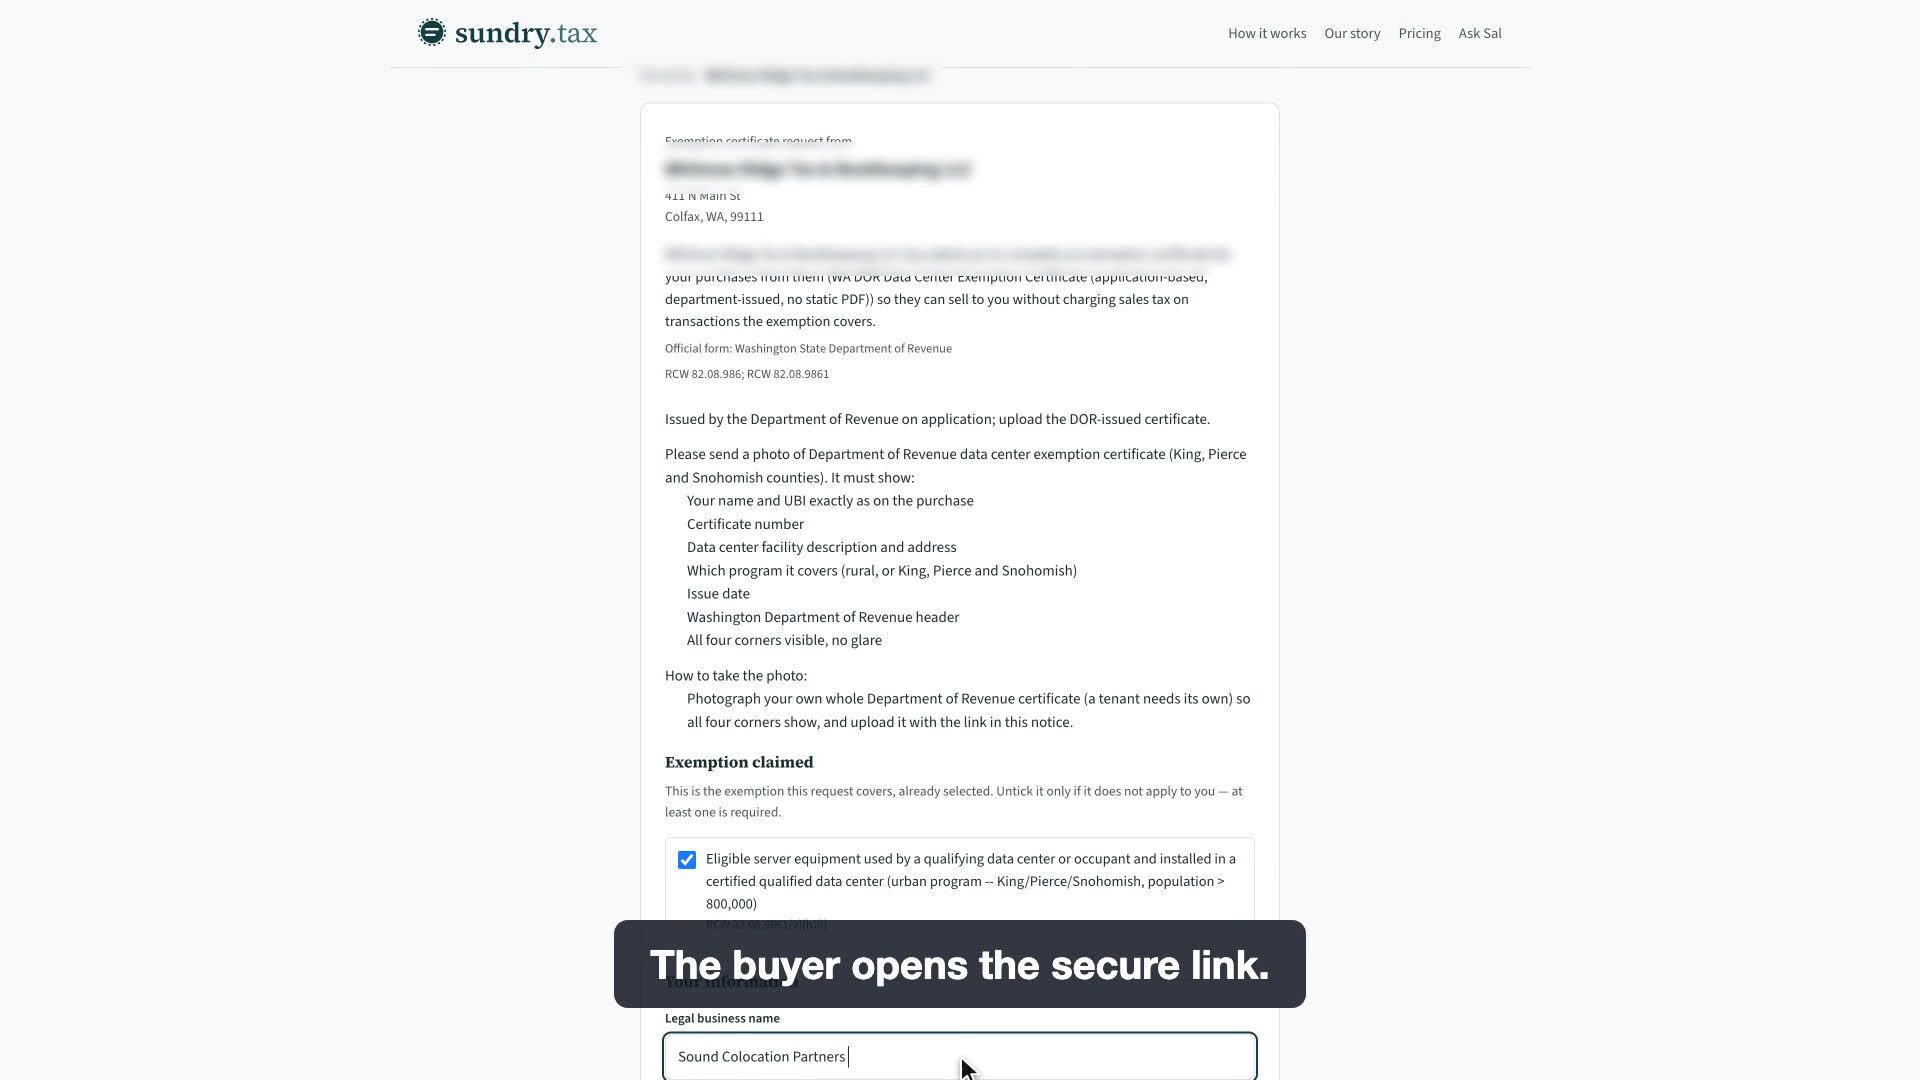
A firm asks a customer for the Department-issued certificate, the buyer uploads a photo of it from the emailed link, and Sundry shows it received and checked.
The owner of an eligible data center in a county with more than 800,000 people (DOR lists King, Pierce and Snohomish), and qualifying tenants, can buy original server equipment free of Washington sales and use tax, plus installation labor. Owner equipment must be installed on or after June 9, 2022; tenant equipment within 10 years of that date. DOR issues the certificate; the seller keeps a copy.
Who qualifies
- A qualifying business (for-profit owner) in a county over 800,000 population with at least 1.5 megawatts of available power, holding one of the limited DOR certificates; or a qualifying tenant with at least 150 kilowatts of contracted capacity and its own certificate.
- The center has at least 20,000 square feet for working servers in a facility of at least 100,000 square feet with backup power, fire suppression and enhanced physical security, such as restricted access, continuous on-site security guards, video surveillance or keycard and biometric entry.
What qualifies
- For the owner: original server equipment installed in the eligible data center on or after June 9, 2022.
- For a tenant: original server equipment installed in its leased space "on or within 10 years of June 9, 2022."
- Server equipment is hardware used exclusively for electronic data storage and data management services (storage and backup, processing power, hosting software and websites, email, search, media and other online services), plus the software needed to run it.
- Labor and services to install eligible server equipment. Use tax is exempt if first used before July 1, 2038.
Not covered
- Equipment in stand-alone, prefabricated or modular units, including shipping containers; these are not eligible data centers.
- Data centers refurbished on or after July 1, 2026.
- Personal computers, racks and peripherals are excluded "unless used within the eligible computer data center"; this differs from the rural statute, which excludes them outright. Ask DOR before treating racks as exempt.
- Tenant equipment installed after the 10-year window from June 9, 2022.
- Purchases before the certificate's issue date.
What the buyer gives
A copy of the DOR-issued Certificate for Sales Tax Exemption for Purchases by Data Centers. Owners apply on REV 40 2448 and tenants on REV 40 2451 through My DOR under the Data Centers topic, before purchasing. DOR issues the certificate; the buyer presents a copy to each seller and later files the Buyer's Sales and Use Tax Preference Addendum and the Annual Tax Performance Report.
What the seller keeps
RCW 82.08.9861(2)(b): the buyer "must present the seller with an exemption certificate in a form and manner prescribed by the department. The seller must retain a copy of the certificate for the seller's files." DOR's urban data center page: present the certificate to the seller, "who must keep a copy for their files." Only purchases on or after the certificate's issue date qualify ((2)(d)); a certificate expires two years after issue unless construction has begun ((2)(e)). RCW 82.32.070(1) requires five years of records, and RCW 82.08.050(4) requires proper records of exempt sales.
Common mistakes
- Using the rural rules. The urban dates (June 9, 2022), power thresholds and certificate caps are different, and the urban definition treats racks and peripherals differently.
- Exempting servers for a container deployment.
- Selling to a tenant on the owner's certificate. The tenant needs its own.
- Missing the claim year: the exemption must be claimed in the tax year the tax would have been due unless an extension is filed (RCW 82.08.9861(6)).
Common questions
- Are servers for a Snohomish County data center exempt from sales tax?
- They can be, if the owner or tenant holds a DOR certificate under RCW 82.08.9861 and the servers are original equipment installed after June 9, 2022 (owners) or within 10 years of that date (tenants).
- How many urban data center certificates can DOR issue?
- Six owner applications in the first calendar year and six in each of years three through six. DOR's table shows 6, 0, 6, 6, 6, 6 for 2022 through 2027, and no new certificates may be issued on or after July 1, 2028.
- Can a colocation tenant buy servers tax-free?
- Yes, with its own certificate: it needs at least 150 kilowatts of contracted electrical capacity in a qualifying urban data center and applies on REV 40 2451.
- What does the seller keep?
- A copy of the buyer's DOR-issued certificate (RCW 82.08.9861(2)(b)).
Sources
- RCW 82.08.9861 (1)(a), (2)(a)-(f), (6), (9)(d), (e), (f), (h), (l)
- RCW 82.12.9861 (1)-(5) use tax
- DOR Tax incentive programs Data Centers: Urban data centers (limit on certificates, application process, approval and reporting)
- DOR form REV 40 2448 (6/25/26), Owner Application for Sales Tax Exemption for Purchases by Data Centers - Urban; and REV 40 2451 (12/9/25), Tenant Application - Urban Sections 1-6 (tenant form: https://dor.wa.gov/sites/default/files/2022-06/40%202451.pdf)
- RCW 82.08.050 (4), (7)(a)-(c)
- RCW 82.32.070 (1) five-year record retention
- Form
- WA DOR Data Center Exemption Certificate
- Statute
- RCW 82.08.9861(9)(h)(i)
- Category
- Department-issued
- How the buyer provides it
- Uploads a photo of the Department-issued certificate