Department-issued
Data center (rural counties): eligible power infrastructure
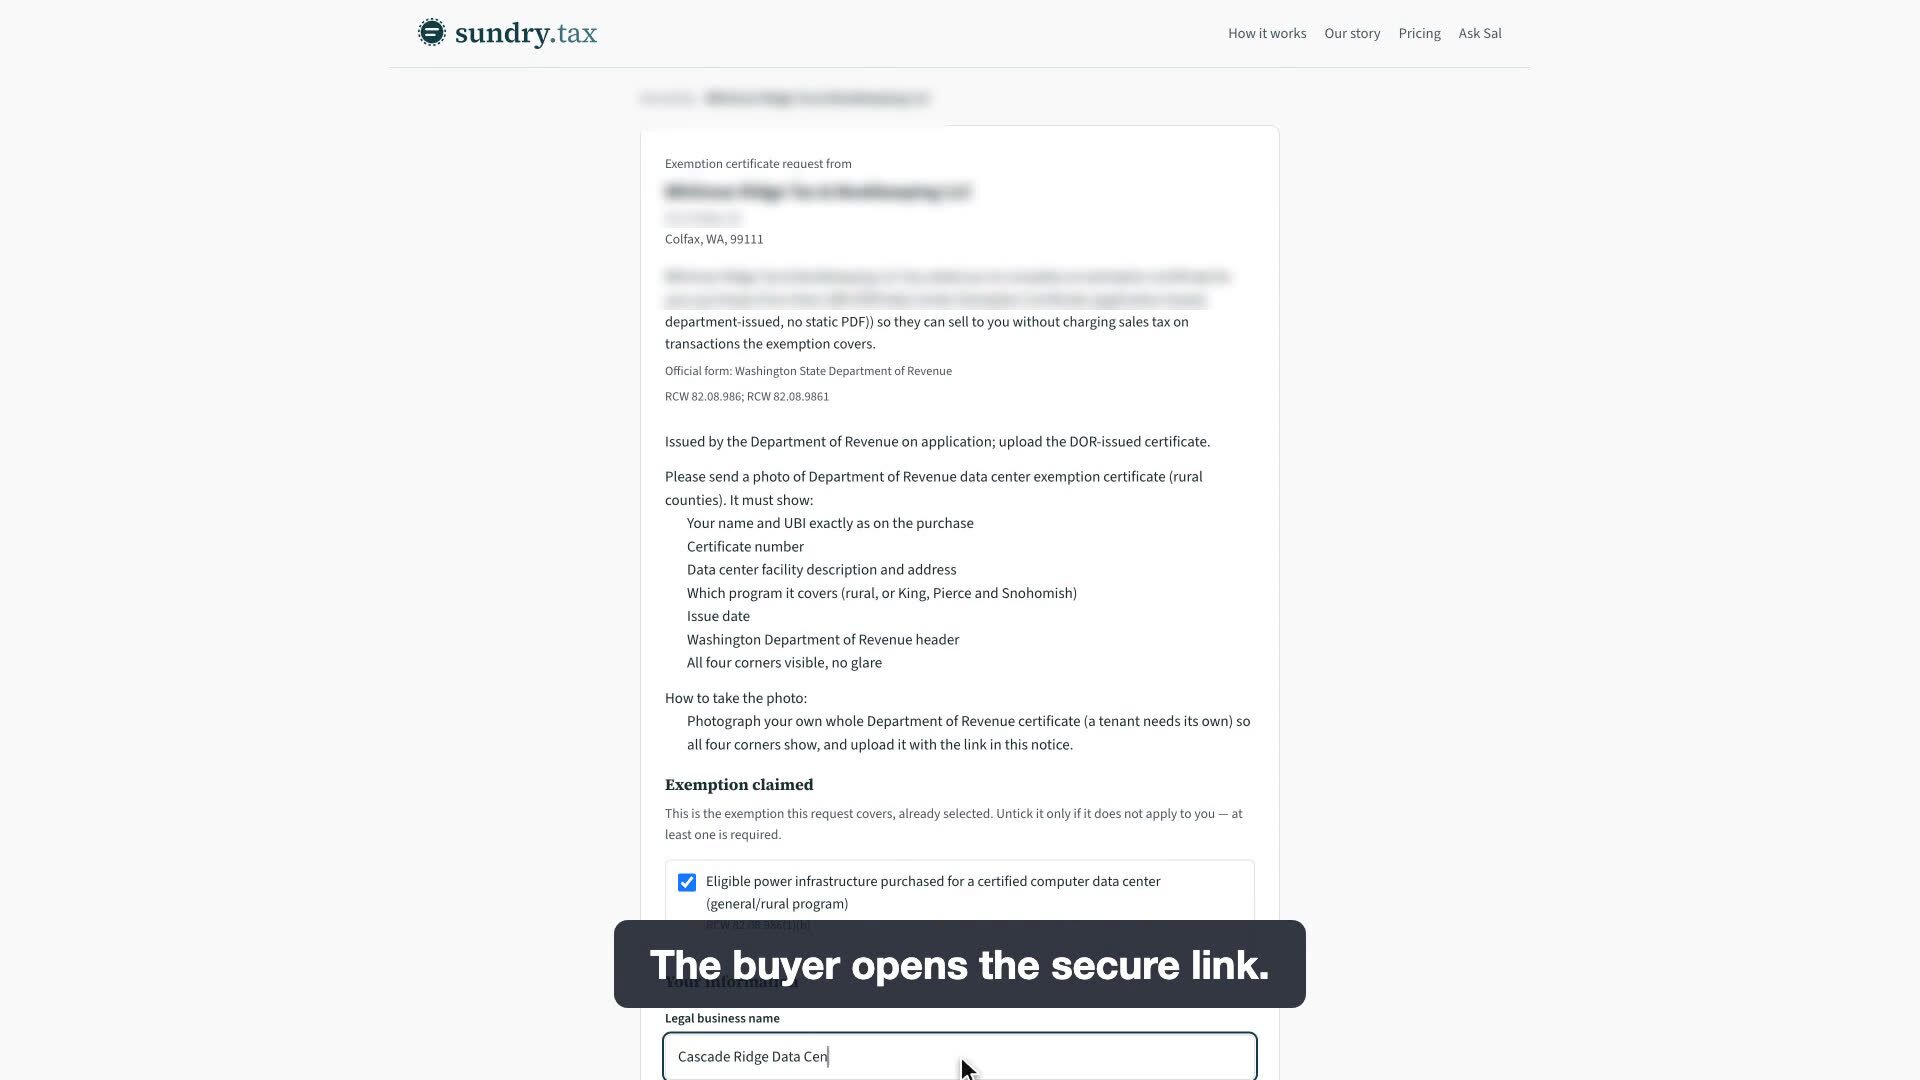
A firm asks a customer for the Department-issued certificate, the buyer uploads a photo of it from the emailed link, and Sundry shows it received and checked.
The owner of an eligible data center in a rural county, and its qualifying tenants, can buy eligible power infrastructure free of Washington sales and use tax: generators, wiring, switches, batteries and similar equipment that transforms, distributes or manages the electricity the servers need, plus labor to build, install, repair, alter or improve it. The buyer applies to DOR and gets a certificate from DOR; the seller keeps a copy.
Who qualifies
- A qualifying business: a for-profit business that owns an eligible computer data center. Governments, tribal governments and public corporations are excluded.
- A qualifying tenant: a for-profit business leasing space from a qualifying business in the data center (with exclusions for certain affiliated lessees).
- An eligible computer data center is in a rural county (RCW 82.14.370) when the application is received, has at least 20,000 square feet for working servers, is part of a facility of at least 100,000 square feet with backup power, fire suppression and enhanced physical security, and its construction began in one of the statute's windows (the current one: after June 30, 2015 and before July 1, 2035).
- The business must hold a certificate DOR issued for that data center. DOR: submit the owner or tenant application through My DOR (Data Centers topic) before buying.
- Afterward the holder must meet the family wage job targets within six years. For certificates issued on or after June 9, 2022, the operator of a newly constructed data center must also certify a green building standard within three years of going into service; if not, previously exempted taxes may be immediately due, with an additional 10 percent penalty. DOR may grant extensions for circumstances beyond the holder's control (RCW 82.08.986(3)(d), (4)(a), (4)(c)).
What qualifies
- "Eligible power infrastructure": all fixtures and equipment owned by the qualifying business or tenant and necessary to transform, distribute or manage the electricity required to operate eligible server equipment in the data center.
- The statute names generators, wiring, cogeneration equipment, and associated fixtures and equipment such as electrical switches, batteries, and distribution, testing and monitoring equipment.
- Labor and services to construct, install, repair, alter or improve that infrastructure, so repair work on a qualifying generator is covered.
- Use tax is exempt on the same items (RCW 82.12.986(1)(b), until July 1, 2048).
Not covered
- Substations (excluded by the definition).
- Equipment the qualifying business or tenant does not own, for example utility-owned gear.
- Purchases made before the certificate's issue date; the statute allows no refunds for them.
- Data centers that qualify only through refurbishment: that route ended July 1, 2026, with no new refurbishment certificates from that date.
- Server equipment itself is a separate part of the same exemption (see the server equipment guide); electrical gear for offices or other non-server uses is not "required to operate eligible server equipment."
What the buyer gives
A copy of the Certificate for Sales Tax Exemption for Purchases by Data Centers that DOR issued to it. There is no fill-in form: the buyer applies to DOR (owners on REV 40 2428 with the building permit or certificate of occupancy, site plan and proof of ownership; tenants on REV 40 2449 with the owner's certificate and the lease), DOR issues the certificate and may give it a unique number, and the buyer presents it to each seller. The application also asks the applicant to certify that the work will be built under community workforce or project labor agreements with area standard prevailing wages and apprenticeship use.
What the seller keeps
RCW 82.08.986(2)(b): the buyer "must present the seller with an exemption certificate in a form and manner prescribed by the department. The seller must retain a copy of the certificate for the seller's files." DOR's data center page says the same: present the certificate to the seller, "who must keep a copy for their files." Check the certificate's issue date: under (2)(d) only purchases on or after that date qualify, and certificates expire two years after issue unless construction has begun ((2)(e)). RCW 82.32.070(1) requires five years of records, and RCW 82.08.050(4) requires proper records of exempt sales.
Common mistakes
- Exempting a substation. The definition of eligible power infrastructure excludes substations.
- Selling tax-free before the certificate exists. The certificate is effective on the date DOR receives the application; earlier purchases stay taxable and no refund is allowed.
- Exempting equipment for a data center that qualified only through refurbishment after July 1, 2026. DOR's notice says that exemption expired.
- Assuming a tenant can use the owner's certificate. A tenant applies separately and gets its own certificate (REV 40 2449 asks for the owner's certificate number).
Common questions
- Are backup generators for a Washington data center exempt from sales tax?
- Yes, for a qualifying owner or tenant of an eligible rural data center holding a DOR certificate. RCW 82.08.986(8)(g) lists generators as eligible power infrastructure.
- Is repair labor on data center power equipment exempt?
- Yes. RCW 82.08.986(1)(b) covers labor and services to construct, install, repair, alter or improve eligible power infrastructure.
- How does a data center get its DOR-issued certificate?
- It sends the owner or tenant application and documents to DOR through My DOR under the Data Centers topic. DOR aims to process applications within 30 business days and issues the certificate if the business qualifies.
- Does the seller need anything besides a copy of the certificate?
- The statute asks the seller to keep a copy of the certificate. Check that the sale date is on or after the certificate's issue date.
Sources
- RCW 82.08.986 (1)(b), (1)(e), (2)(a)-(e), (3), (4), (8)(d), (f), (g), (i), (j)
- RCW 82.12.986 (1)-(4) use tax
- DOR Tax incentive programs Data Centers: Rural data centers (application process, approval and reporting)
- DOR form REV 40 2428 (6/25/26), Owner Application for Sales Tax Exemption for Purchases by Data Centers - Rural; and REV 40 2449 (12/9/25), Tenant Application - Rural Sections 1-6 (tenant form: https://dor.wa.gov/sites/default/files/2022-06/40%202449.pdf)
- DOR Special Notice (June 3, 2026): Modification to sales and use tax exemption for rural data centers Refurbishment and replacement server equipment changes, effective July 1, 2026
- RCW 82.08.050 (4), (7)(a)-(c)
- RCW 82.32.070 (1) five-year record retention
- Form
- WA DOR Data Center Exemption Certificate
- Statute
- RCW 82.08.986(1)(b)
- Category
- Department-issued
- How the buyer provides it
- Uploads a photo of the Department-issued certificate