REV 27-0055
Medical supplies bought by cancer centers, organ procurement organizations and blood and tissue banks
A firm asks a customer for this certificate, the buyer fills in and signs the form from the emailed link, and Sundry shows it signed and Verified by Sundry.
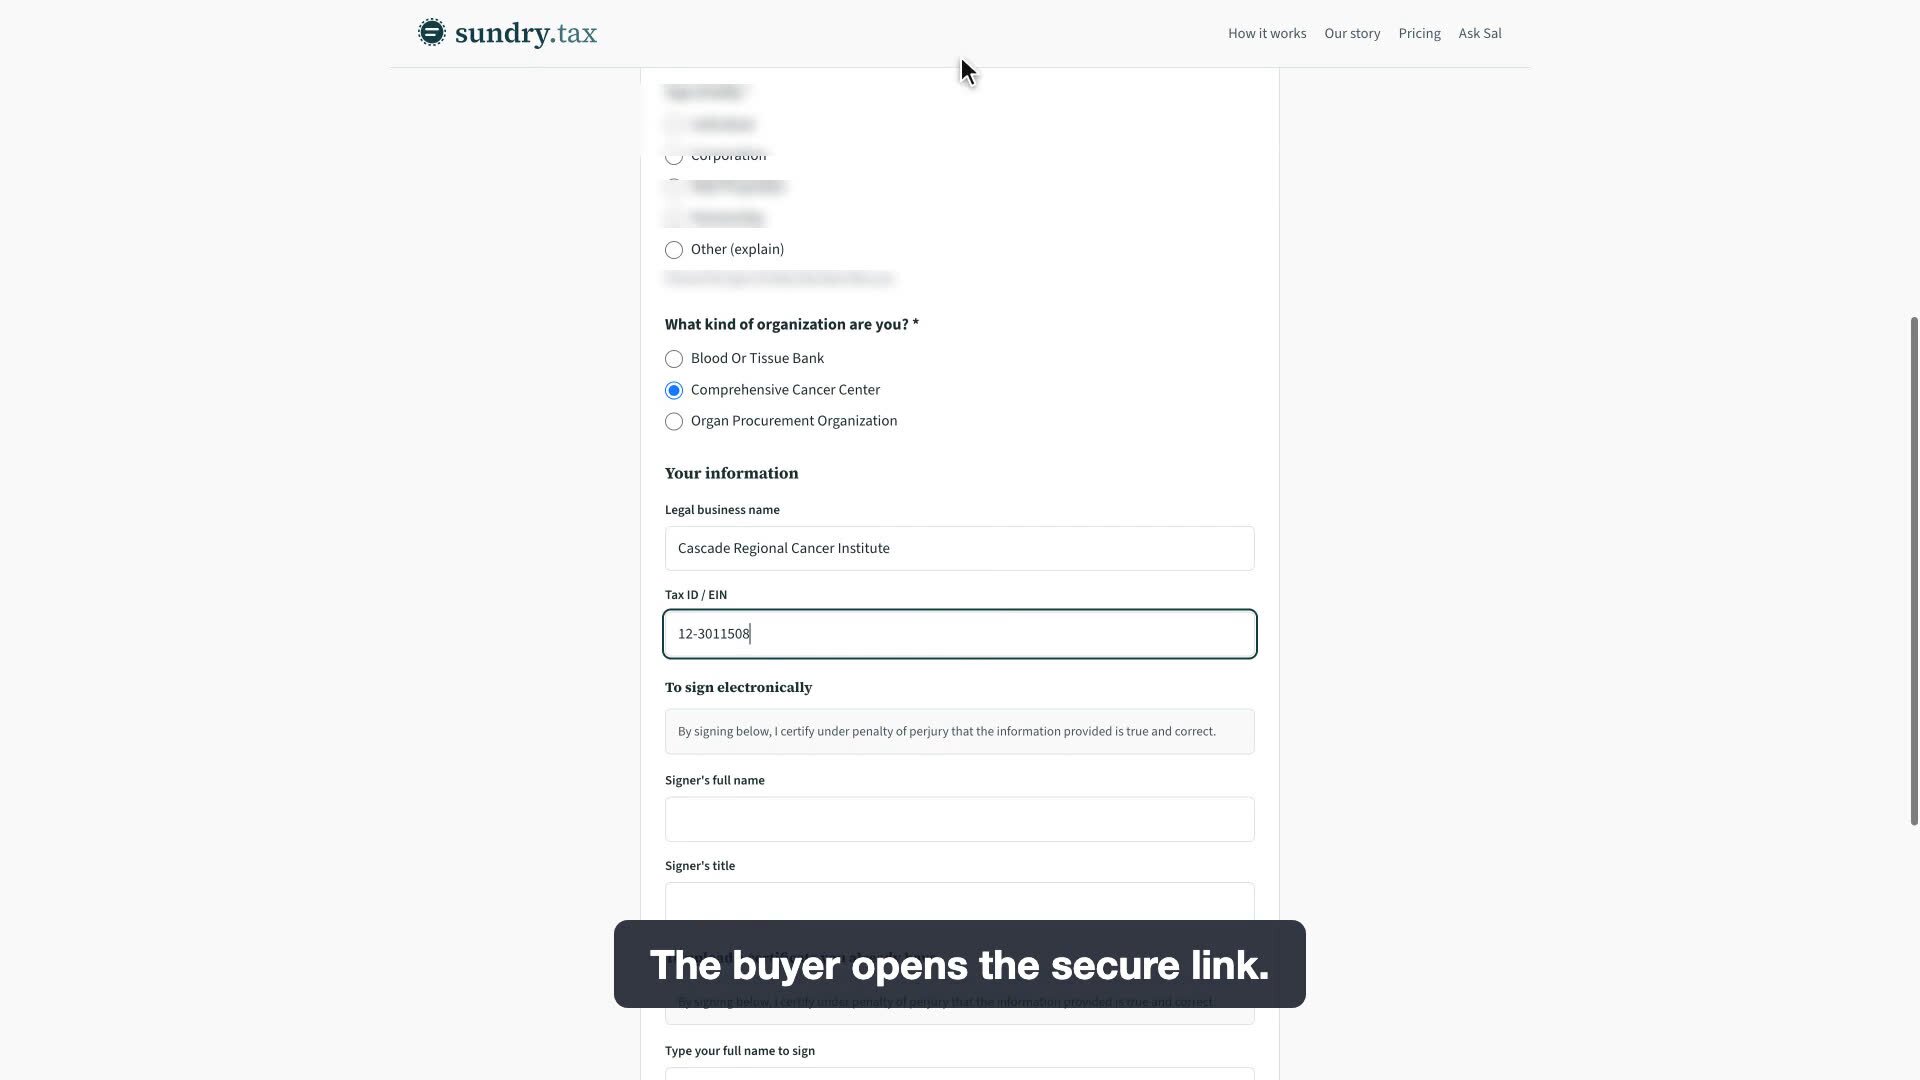
Comprehensive cancer center
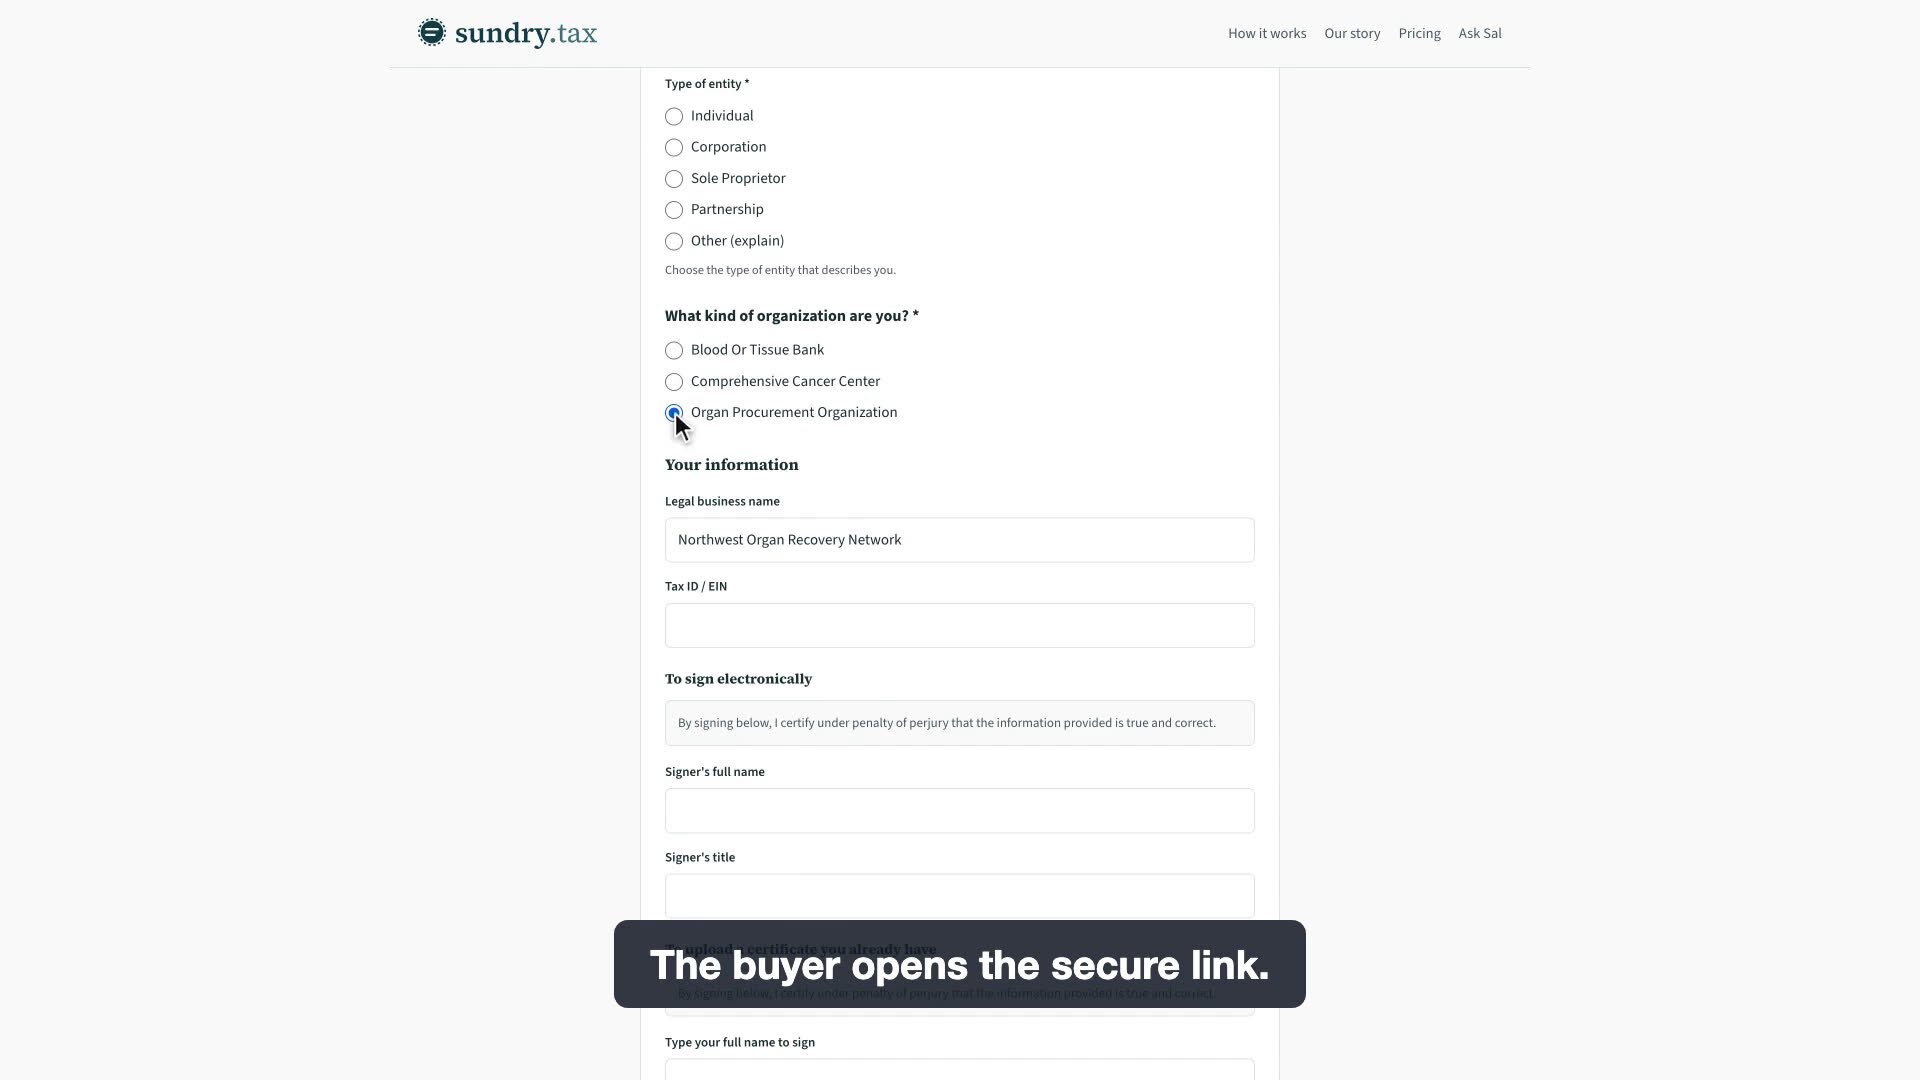
Organ procurement organization
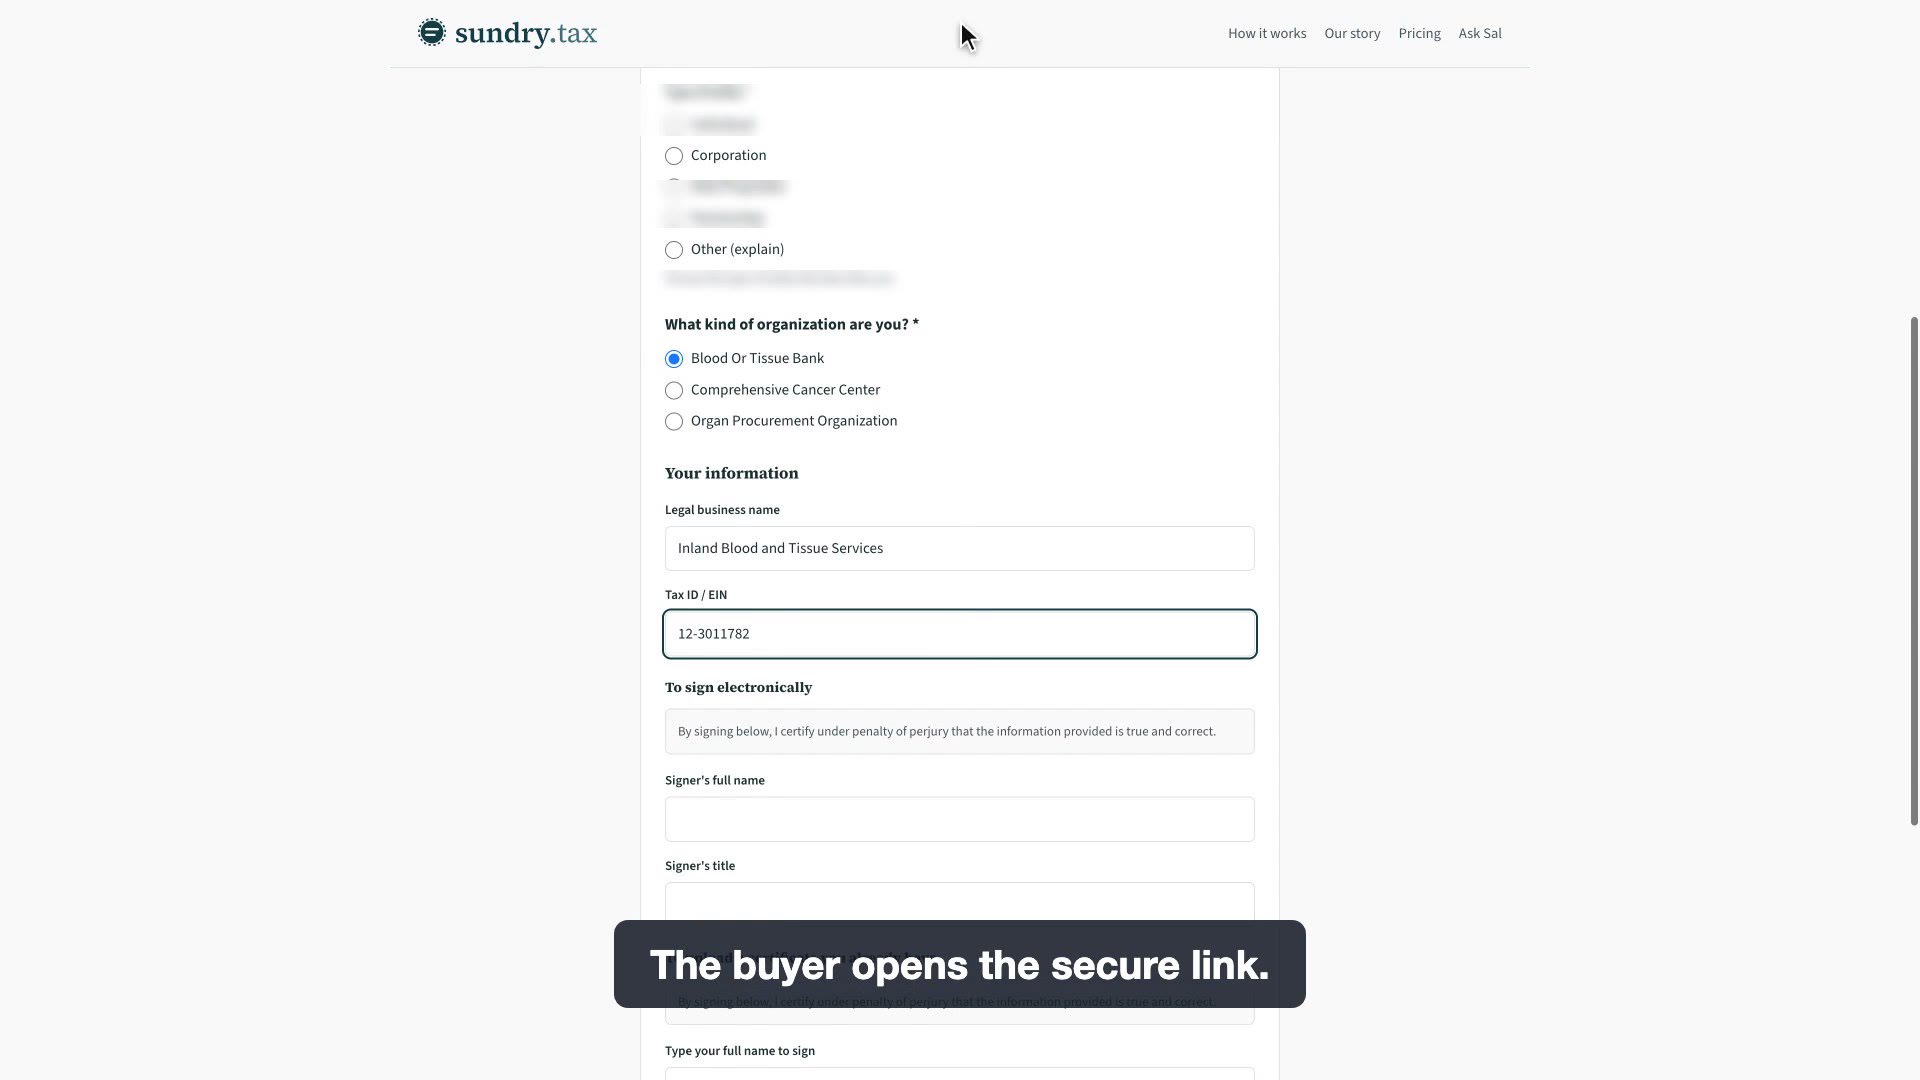
Blood or tissue bank
Medical supplies, chemicals and materials bought by a comprehensive cancer center, an organ procurement organization or a qualifying blood, tissue, or blood and tissue bank pay no Washington retail sales tax when they are used for research on, or the handling of, blood, bone or tissue. Construction materials, office and building equipment, administrative supplies and vehicles stay taxable.
Who qualifies
- A comprehensive cancer center: a cancer center with written confirmation that the National Cancer Institute recognizes it as a comprehensive cancer center, and that qualifies as a 501(c)(3) exempt organization (RCW 82.04.4265(2)).
- An organ procurement organization exempt under RCW 82.04.326, meaning a qualified organ procurement organization under 42 U.S.C. 273(b) whose amounts are exempt from federal income tax.
- A qualifying blood bank, qualifying tissue bank, or qualifying blood and tissue bank, as defined in RCW 82.04.324.
What qualifies
- Medical supplies: tangible personal property, including repair and replacement parts, used for research on, procuring, testing, processing, storing, packaging, distributing or using blood, bone or tissue.
- That includes property used to give preparatory treatment of blood, bone or tissue; to control, guide, measure, tune, verify, align, regulate, test or physically support it; and to protect the health and safety of employees or others present during that work.
- Chemicals: any catalyst, solvent, water, acid, oil or other additive that physically or chemically interacts with blood, bone or tissue.
- Materials: tangible personal property such as bags, packs, collecting sets, filtering materials, testing reagents, antisera and refrigerants, used or consumed in that work.
Not covered
- Construction materials, office equipment, building equipment, administrative supplies and vehicles.
- Items the buyer does not use for research on, or the handling of, blood, bone or tissue.
- Buyers that are not one of the three kinds of organization above, even if they are health care providers. They use the other lines of the form.
What the buyer gives
Form REV 27 0055, Sales Tax Exemption Certificate for Health Care Providers, line 14, "Certain medical supplies, chemicals, or materials purchased by comprehensive cancer centers, organ procurement organizations, and qualifying blood and tissue banks." The buyer ticks single use or blanket (valid while buyer and seller have at least one sale within 12 months), names the seller and the date, ticks the line for the exemption, and completes the signature block: type of entity, name of buyer, name of business, Account ID if any, signature, date, mailing address, title and phone. REV 27-0055 is DOR's Health Care Providers certificate, and DOR puts these buyers' line 14 on it (RCW 82.08.808, 82.08.02807, 82.08.02805). The form's general note limits the form to practitioners who can legally prescribe and excludes chiropractors, East Asian medicine practitioners and massage practitioners.
What the seller keeps
Form REV 27 0055 says the seller or marketplace facilitator "must retain the original of this certificate for their records" and not send a copy to the Department of Revenue. WAC 458-20-18801(304): sellers to medical practitioners, nursing homes and hospitals must obtain an approved exemption form, capture the streamlined sales tax data elements, or otherwise meet RCW 82.08.050(7) for any exempt sale. RCW 82.32.070(1) requires taxpayers to "keep and preserve, for a period of five years, suitable records as may be necessary to determine the amount of any tax for which the taxpayer may be liable." Under RCW 82.08.050(4) a seller is not relieved of the tax unless it keeps proper records of exempt sales and provides them when the department asks; (7)(a) relieves a seller that obtains a fully completed certificate within 90 days after the sale, and (7)(b) allows 120 days after a department request to prove the sale was not taxable or obtain a fully completed certificate taken in good faith.
Common mistakes
- Using line 14 for an organization that is not a comprehensive cancer center, an organ procurement organization or a qualifying blood or tissue bank.
- Putting office equipment, building equipment, administrative supplies or vehicles on the certificate. The statutes exclude them.
- Treating any purchase by a qualifying organization as exempt. The items must be used for research on, or the handling of, blood, bone or tissue.
Common questions
- Does a comprehensive cancer center pay sales tax on its laboratory reagents?
- No, when the reagents are materials used or consumed in research on, or the handling of, blood, bone or tissue (RCW 82.08.808).
- Are an organ procurement organization's vehicles exempt?
- No. RCW 82.08.02807 does not apply to construction materials, office equipment, building equipment, administrative supplies or vehicles.
- Which statutes does line 14 rest on?
- RCW 82.08.808 for comprehensive cancer centers, RCW 82.08.02807 for organ procurement organizations, and RCW 82.08.02805 for qualifying blood, tissue, and blood and tissue banks.
Sources
- RCW 82.08.808 (1), (2)(a)-(e)
- RCW 82.08.02807 (1), (2)(a)-(c)
- RCW 82.08.02805 (1), (2)(a)-(e)
- RCW 82.04.4265 (2) comprehensive cancer center
- RCW 82.04.326 Qualified organ procurement organizations
- DOR form REV 27 0055 (7/23/24), Sales Tax Exemption Certificate for Health Care Providers Line 14; page 3 instructions, line 14
- RCW 82.08.050 (4), (7)(a)-(c) seller records and certificate timing
- RCW 82.32.070 (1) five-year record retention
- Form
- REV 27-0055: Sales Tax Exemption Certificate for Health Care Providers
- Statute
- RCW 82.08.808; RCW 82.08.02807; RCW 82.08.02805
- Category
- Entity
- How the buyer provides it
- Signs the state form in the buyer portal